
Carmignac P. EM Debt: Letter from the Fund Managers
Carmignac P. EM Debt gained +1.42% (for the FW Eur Acc share net of fees) in the first quarter of 2024, while its reference indicator1 rose by only +0.88%.
Market environment
The initial excitement surrounding sovereign rates at the end of 2023 turned out to be short-lived. Starting from the first weeks of January, the strength of economic activity, particularly in the United States where growth remains above its potential, the surge in risky assets driven by the acceleration of the artificial intelligence theme, and the significant issuance of bonds to finance public deficits that are normalizing at a slow pace, led to higher global rates (returning to levels close to the average for 2023). This also dashed hopes for continued disinflation in the United States, although this seems to be less of a concern in Europe. In fact, in the Eurozone, headline inflation continued to decline in March to +2.4% YoY, and producer prices also fell more than expected at -1% MoM. However, services inflation has remained stubbornly high at 4% for the past three months.
Given these circumstances, the possibility of a coordinated interest rate cut trajectory between the European Central Bank and the Federal Reserve appears to be diminishing. Additionally, the Bank of Japan ended its negative interest rate policy by raising rates from -0.1% to a range of 0%-0.1%.
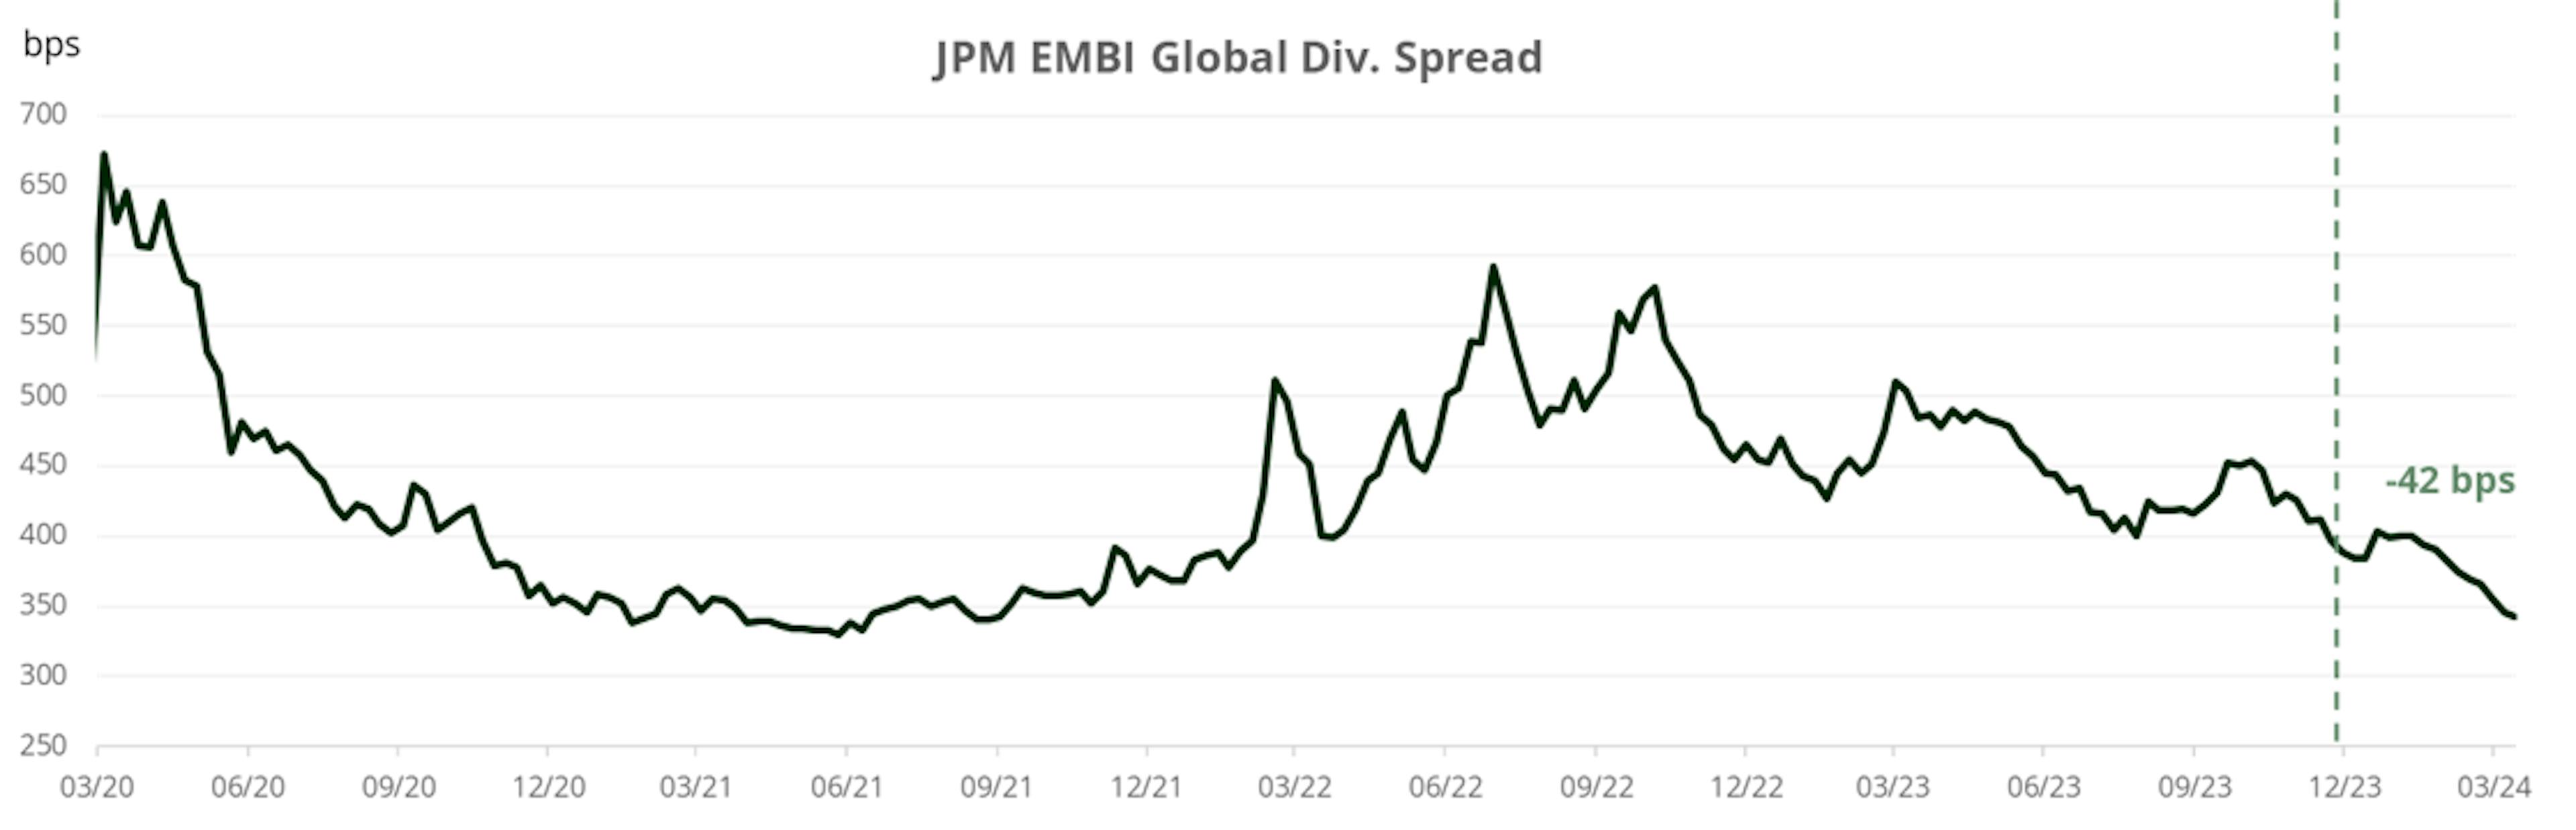
Turning to emerging countries, we also witnessed a significant number of central bank meetings during the quarter. We observed that many of them have adopted a slightly more restrictive tone compared to before. While some central banks in the Latin American region continued their cycle of interest rate cuts, their outlook for the future has changed somewhat. Most central banks in emerging countries are now reducing the magnitude of their interest rate cuts or adopting a pause stance. As a result, the performance of the local debt index (expressed in euros) has been relatively neutral this quarter. However, despite the upward movement of rates in developed countries, local rates have once again proven to be less sensitive and more resilient. On the other hand, the emerging debt market in hard currencies has continued to perform exceptionally well, primarily due to a tightening of spreads (-42 bps since the beginning of the year, as shown in the chart below).
Among the notable events during the period, we highlight:
- China continued its stimulus yet that seems insufficient to boost its economy or improve its real estate sector for the moment.
- The Egyptian central bank, which raised the deposit rate to 27.25% (by 600 basis points) and allowed the currency to float, resulting in an immediate devaluation of -38%. As a result, the IMF increased its aid program to the country from 3 to 8 billion dollars. This was accompanied by additional multilateral support from the World Bank and the European Union. As a result, we have witnessed a strong appreciation of Egyptian external debt.
- Banxico (maxico’s Central Bank) started cutting rated with a shy -25 bps that in the end confirmed that the first cut was a hawkish cut.
- EM disinflation is nearing its final stage, as the boost from commodity prices, supply chain stabilization, and base effects has already passed.
What have we done in this context?
The fund recorded a positive performance in the first quarter, above its benchmark. Our selection of emerging market debt in hard currency continued to generate positive performance. It is interesting to note that the fundamentals of high-yielding EM issuers have generally improved, supporting the recent tightening of spreads. Among the main contributors to the performance of the strong currency debt, we can notably mention Argentina, Ecuador, Ukraine, Romania, and Ghana to name a few.
As for emerging market debt denominated in local currency, its contribution was more neutral, with Poland being among the main contributors to the fund's performance. However, our long positioning in South African weighed on the performance of the fund, in fact the South African central bank is among those central banks that have adopted a pausing posture.
Corporate credit also continued to contribute positively to the fund's performance, thanks to the ongoing tightening of spreads in this sector. However, we maintain a high level of protection given the historically low credit spreads. In addition, our relative underweight in terms of interest rate sensitivity contributed positively to our performance compared to our benchmark. We maintained a cautious position in terms of overall duration throughout the period, with an interest rate sensitivity of approximately 3.9 at the end of the period. Ultimately, our currency strategies negatively impacted the fund's performance, particularly our long position in the Japanese yen. However, the Euro, the Indian rupee and the Kazakh tenge contributed positively to the fund's absolute performance.
Outlook for the next months
The latest macroeconomic indicators suggest that the low point of manufacturing activity is behind us in the United States, the eurozone, and China. This situation particularly supports our optimism regarding commodities such as copper and oil. This should benefit emerging market debt and currencies of commodity-producing emerging market countries. We have a positive view on the Brazilian real. In fact, with a dovish Fed and strong performance of risky assets in the backdrop of a "soft-to-no landing" global economy, high carry in select emerging markets, particularly in Latin America, remains favorable (whether it be in the currency, loclal rates).
We also maintain a constructive view on certain Asian currencies such as the Korean won, as their economies are expected to benefit from the rise of artificial intelligence. We also maintain our buying position on the Japanese yen as the Bank of Japan has started its rate hike cycle in March and is fighting against the depreciation of its currency. We also remain buyers of emerging market debt in strong currencies, although we are starting to take profits on our best-performing positions since the beginning of the year.
Regarding local rates, we believe that emerging markets have been less sensitive to the movements of rates in developed countries, with a few exceptions such as Chile or Colombia where inflation has been higher than expected. We particularly appreciate Mexican local rates where we anticipate further rate cuts from the central bank. Additionally, we are also positive on Brazilian rates where we believe the market's terminal rate is still too high. Finally, we continue to appreciate Chinese rates where we expect more accommodative measures.
Regarding hard currency debt, it is interesting to mention that the fundamentals of high-yield issuers have generally improved, which supports the recent tightening of spreads. However, these names remain very attractive in terms of yield. In fact, we have continued to reduce rates in Eastern Europe, particularly Hungarian bonds, as the market has already priced in a number of future rate cuts in the country.
In the current economic context, our interest rate sensitivity is close to 400 basis points, in line with the previous month, while continuing to protect the portfolio through index hedges (credit default swaps).
Past performance is not a reliable indicator of future performance. The return may increase or decrease as a result of currency fluctuations. Performances are net of fees (excluding possible entrance fees charged by the distributor).
Carmignac Portfolio EM Debt
Carmignac Portfolio EM Debt FW EUR Acc
- Recommended minimum investment horizon
- 3 years
- Risk indicator*
- 3/7
- SFDR - Fund Classification**
- Article 8
*Risk Scale from the KID (Key Information Document). Risk 1 does not mean a risk-free investment. This indicator may change over time. **Sustainable Finance Disclosure Regulation (SFDR) 2019/2088. The SFDR classification of the Funds may change over time.
Main risks of the fund
Fees
- Entry costs
- We do not charge an entry fee.
- Exit costs
- We do not charge an exit fee for this product.
- Management fees and other administrative or operating costs
- 1.06% of the value of your investment per year. This estimate is based on actual costs over the past year.
- Performance fees
- There is no performance fee for this product.
- Transaction Cost
- 0.34% of the value of your investment per year. This is an estimate of the costs incurred when we buy and sell the investments underlying the product. The actual amount varies depending on the quantity we buy and sell.
Performance
| Carmignac Portfolio EM Debt | +0.5 | +7.9 | +4.1 | +15.3 | −9.0 | +3.9 | +10.5 | +28.9 | −10.0 | +1.1 |
| Reference Indicator | +2.1 | +8.6 | +4.4 | +8.9 | −5.9 | −1.8 | −5.8 | +15.6 | −1.5 | +0.4 |
| Carmignac Portfolio EM Debt | +6.4% | +3.9% | +5.2% |
| Reference Indicator | +6.3% | +3.6% | +2.5% |
Source: Carmignac at 30 Oct 2026.
Date of 1st NAV : 31/07/2017.
Past performance is not necessarily indicative of future performance. Performances are net of fees (excluding possible entrance fees charged by the distributor). The Fund presents a risk of loss of capital.
The return may increase or decrease as a result of currency fluctuations, for the shares which are not currency-hedged.
Reference Indicator: 50% JPM GBI-EM Global Diversified Composite index + 50% JPM EMBI Global Diversified Hedged index. Rebalancing Frequency: Quarterly