
Our 2025 Sustainable Investment Retrospective: Putting head in sand on ESG - a costly mistake

2025 felt like a whirlwind from a sustainable investment perspective. With no shortage of negative headlines, it is easy to be deceived in thinking it was a uniformly negative year. But scratch beneath the surface, and it becomes clear that the reality is far different. We highlight below the 5 biggest ways ESG issues impacted markets in 2025.
1. ESG created the best performing market?
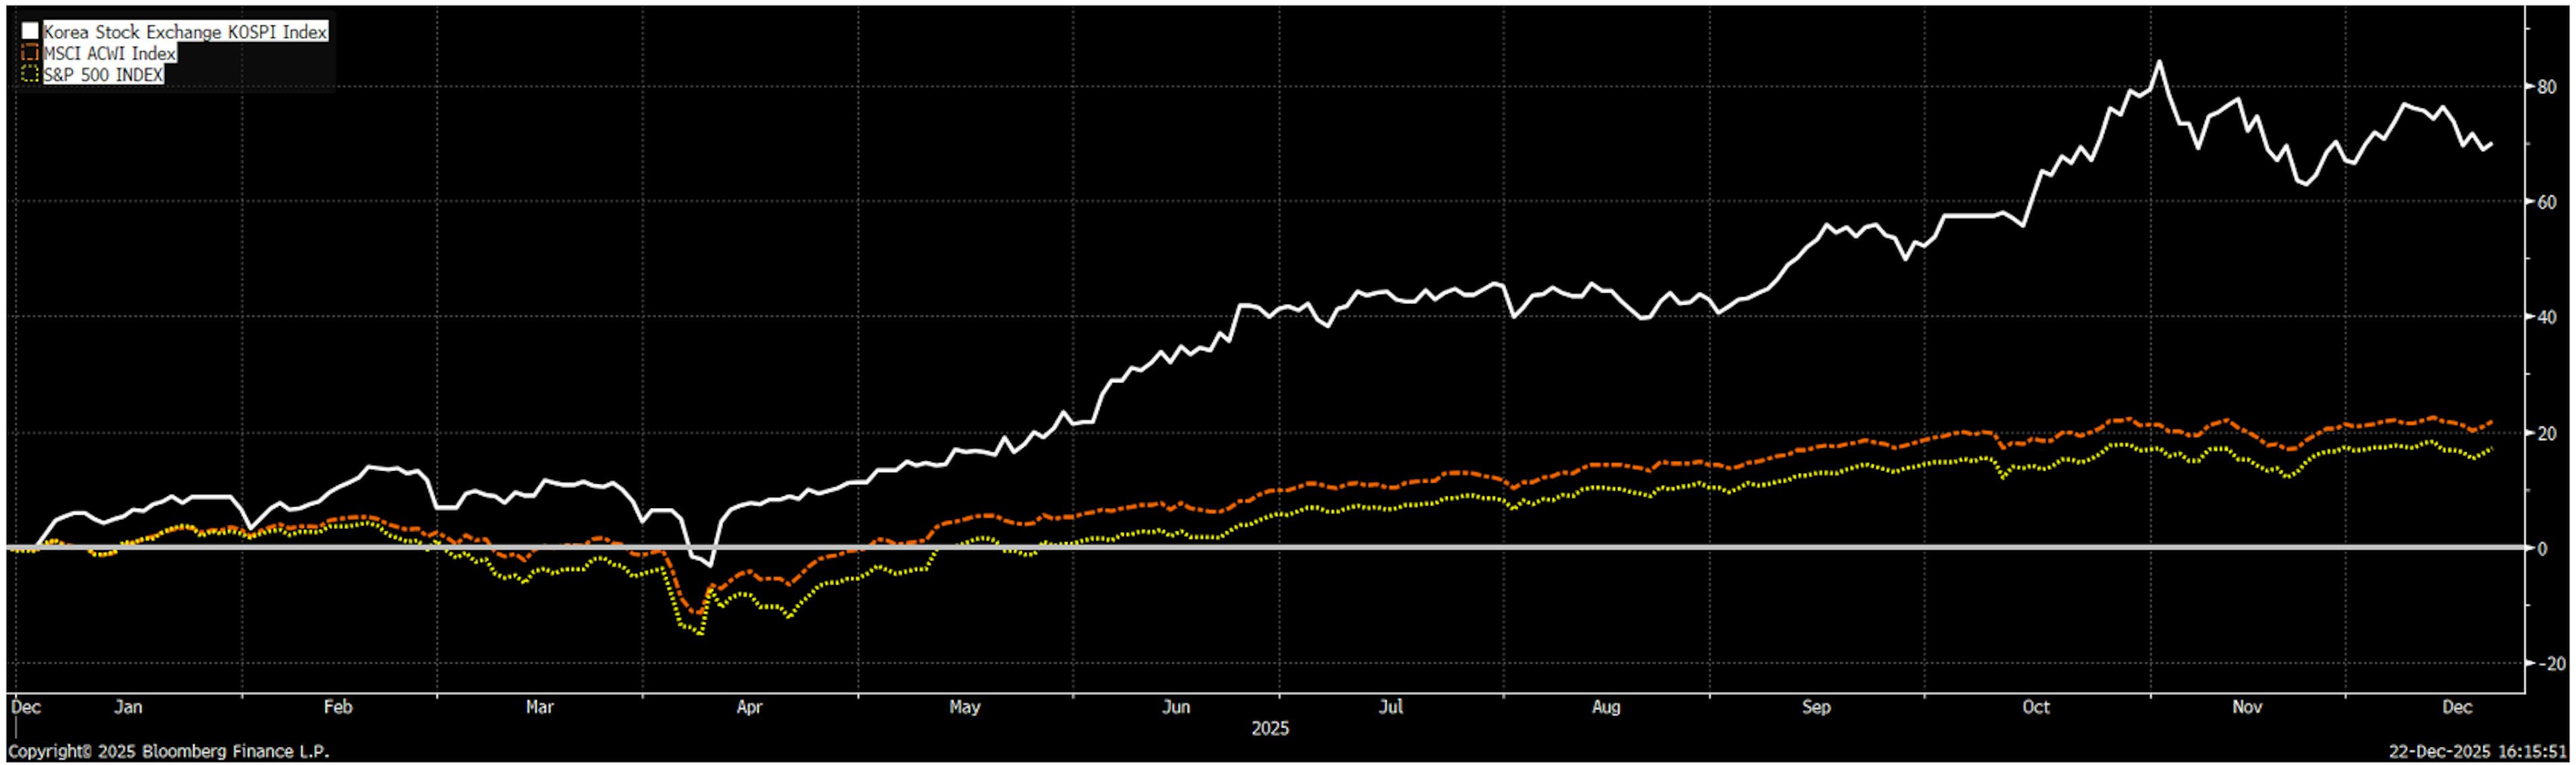
If ever any evidence was needed to show ESG factors can positively impact security prices, look no further than the South Korean market in 2025. It is estimated that the Value-Up programme aimed at improving governance standards causally created 30% of the 74% rise in value this year1. Of course, we recognise that the AI driven semi-conductor giants Samsung Electronics and SK Hynix drove the remaining majority of the gains, but this represents a clear example of governance reform acting as a valuation catalyst and that our lobbying for many years on this front has begun to pay dividends.
This stands in sharp contrast to declining governance standards in the United States, where we observe unconventional policy making and weakening minority shareholder rights. In addition, the “K-shaped” economy and rising inequality is stretching the social contract. These underlying dynamics created a weaker institutional setting which created an amplifying context to the “sell America” trade driven by tariff announcements in April 2025.
2. Environmental concerns continue to shape technology and cash flows
Tightening global regulations on environmental matters leading to innovative challenger technologies continues to be an unavoidable theme for corporates. Returns from clean energy (45%) easily outstripped oil and gas (13%) in 2025, with further good news that the once rigid link between economic growth and carbon emissions is breaking across the vast majority of the world2.

This has been supported by European regulation such as the Carbon Border Adjustment Mechanism providing non-EU countries such as Taiwan, Turkey, India, Brazil and Japan with impetus to introduce their own national carbon markets so as to avoid new environmental import tariffs.
The two biggest environmental shocks during the year were the Spanish grid collapse and “forever chemicals” (PFAS) litigation. Even with Trump hollowing environmental policy support, rising PFAS litigation in the US got chemical companies hot under the collar. With $20bn paid out so far, the total end liability estimate from insurers is $160bn, highlighting the financial dangers of companies selling products that cause harm to human health3.
Furthermore, our investigate trip to Spain after the grid collapse on 28 April revealed that renewables were not to blame despite being optically at the start of the chain of disconnections. Many factors contributed to the chain of events and the root causes were the poor state of grid infrastructure, lack of adequate planning and the slow reactivity of utilities to help with regular grid balancing. This event highlighted the necessity of our grid infrastructure investment theme expressed through holdings such as Prysmian and Siemens.
3. Shifting role of defence in sustainability considerations
With NATO Secretary General Mark Rutte saying that “crazy” ESG rules were harming European defence, many asset managers were on the backfoot reviewing their policies. A quick Bloomberg analysis suggests that the largest defence companies have been able to pay €15bn in dividends, €10bn in share buy-backs, increased cash on their balance sheets by €12bn and paid down debt by €5bn. We observe that these are not the capital allocation decisions of capital constrained companies.
Instead, it is clear that the European defence industry has had a customer problem, with relatively stagnant spending between 2015-2023 and 63% of government defence spending going to US defence companies4. As asset managers re-considered the role of defence in sustainability, several high profile European asset managers scrambled to amend their overly restrictive defence policies, specifically where they were restricting conventional defence in SFDR Article 8 funds. Carmignac did not need to amend its policies during the year, reflecting a balanced approach to defence across our fund range.
4. Social issues debated extensively, but incentives dominated outcomes
The two biggest social issues of the year were the consequences of AI and supply chain standards in the clothing industry. Leaving the energy considerations of AI to one side, the impacts of AI on unemployment, misinformation and critical thinking were heavily debated during the year. The chart below from the Federal Bank of Dallas appropriately demonstrates the broad range of predicted outcomes5.
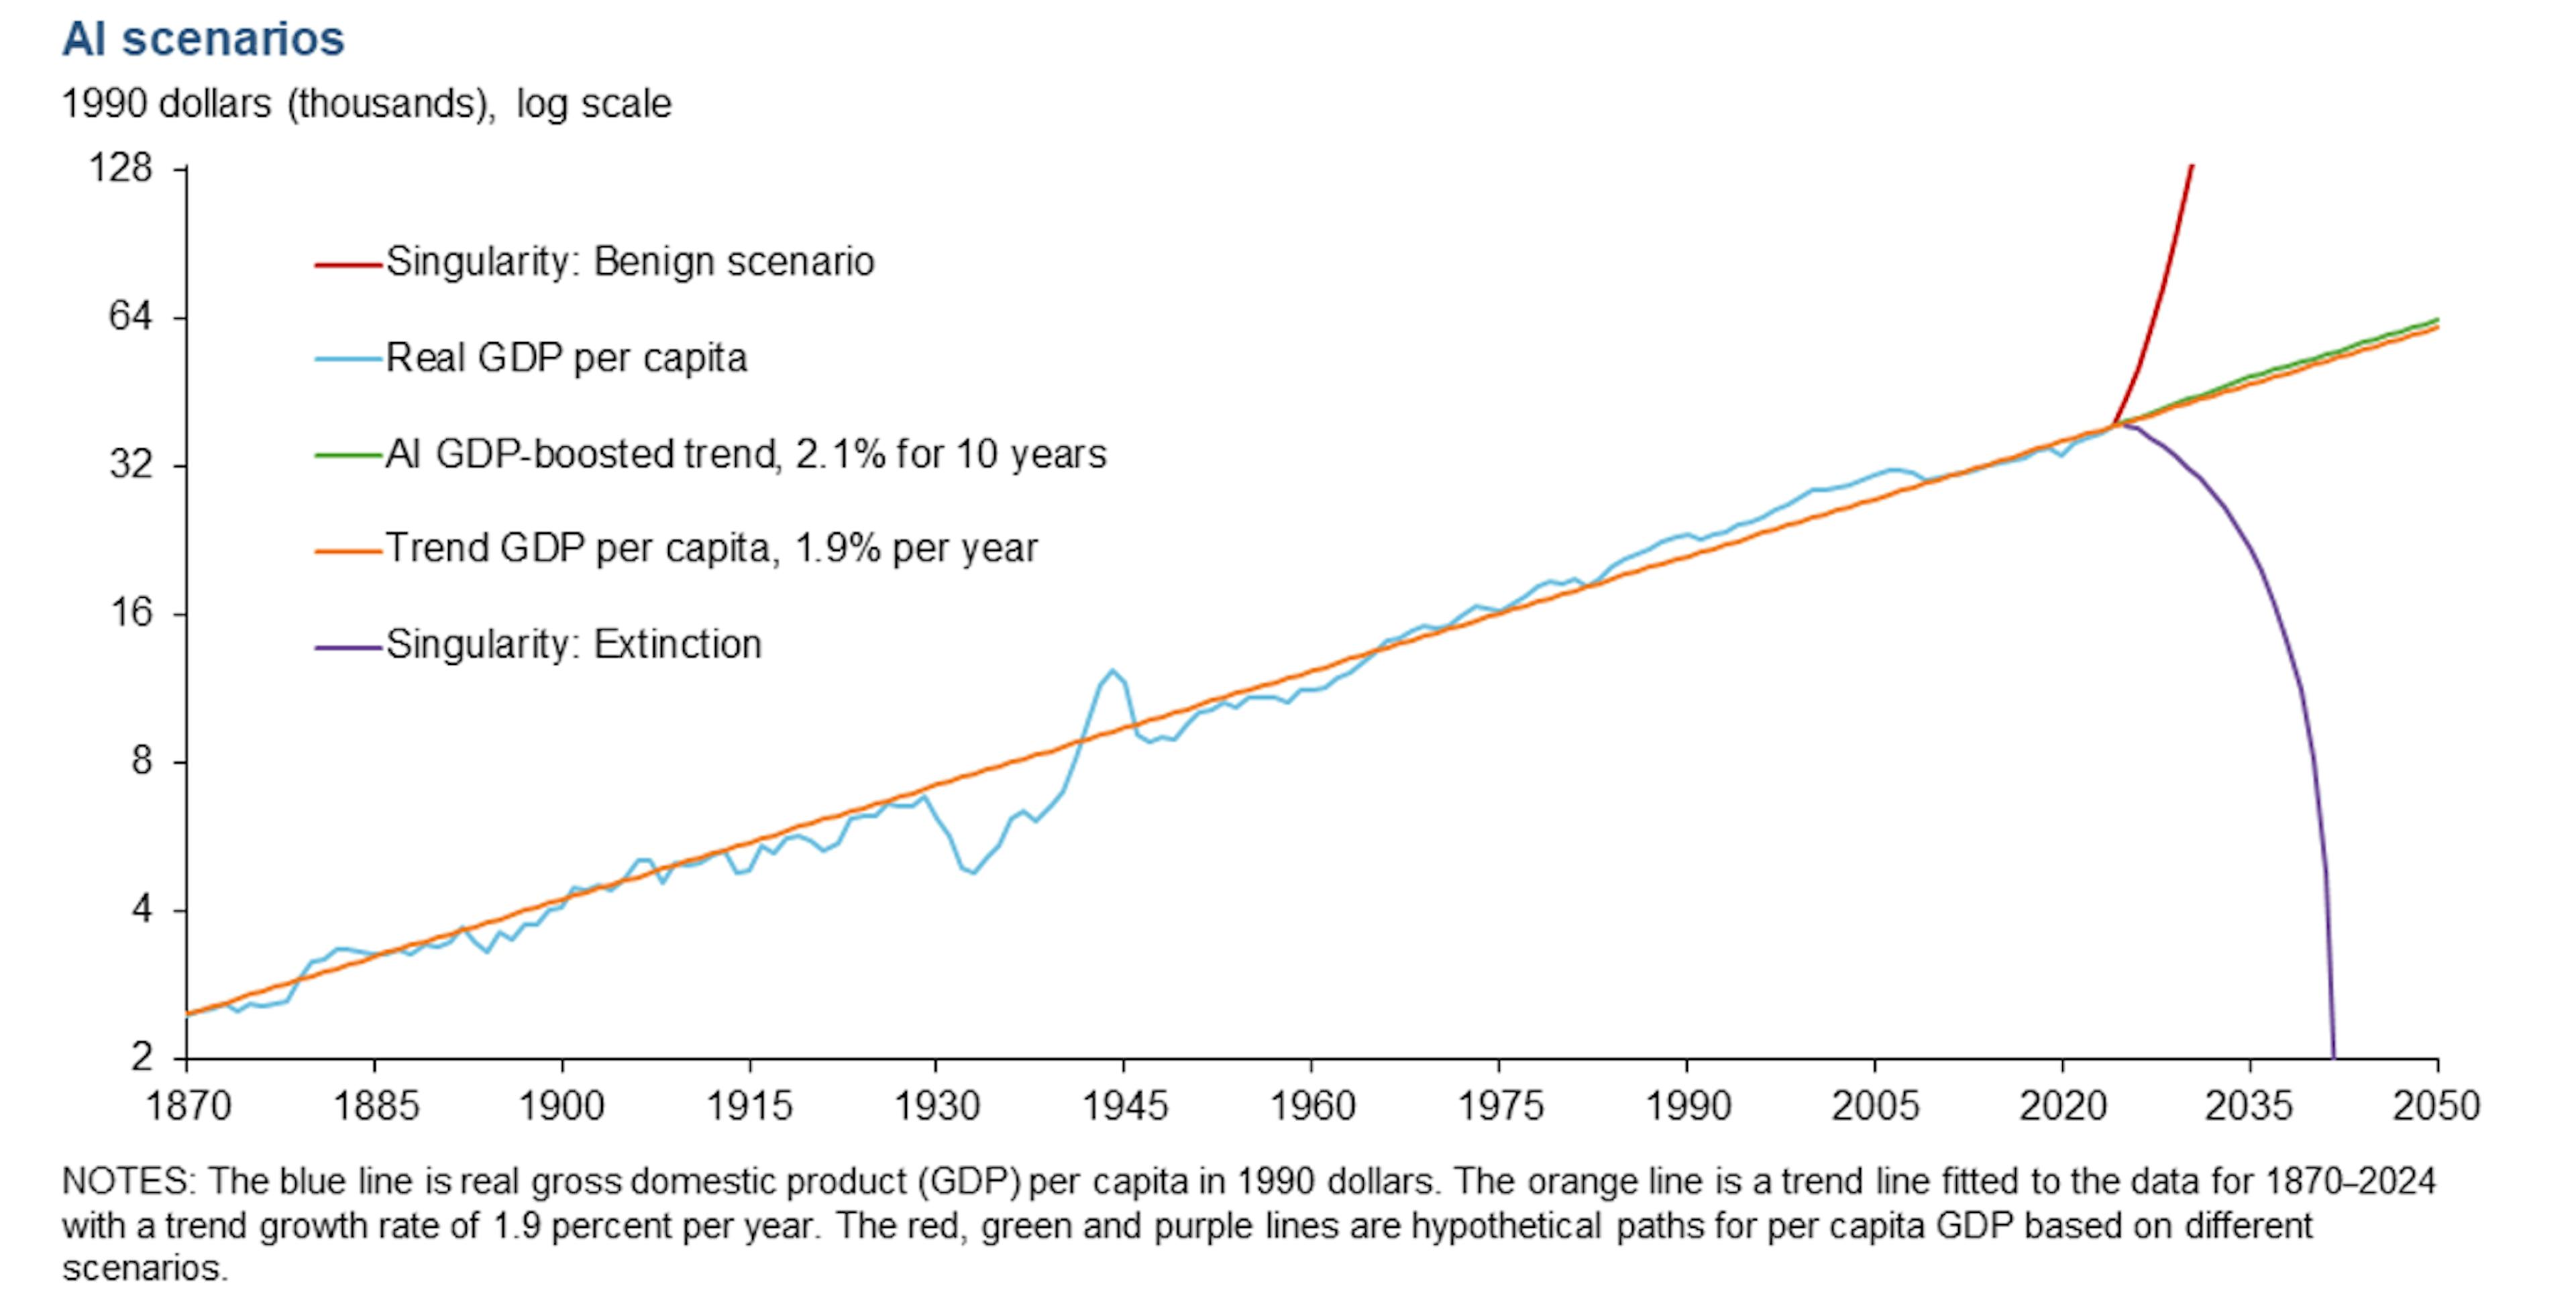
Despite the depth of the debate, in practice, safety remains a topic of secondary importance in the geostrategic race for AI supremacy. We are focussing our corporate engagement efforts on AI governance, where we think a strong framework will help position companies for more durable success.
In the consumer goods sector, low labour standards in the clothing industry were a key topic. Loro Piana, Dior, Valentino, Giorgio Armani, Tods in the luxury sector and Inditex, H&M and Shein in the fast fashion sector all received press coverage for failings in supply chain standards. We are increasingly observing that companies which have vertically integrated supply chains that are centrally organised by head office have a lower likelihood of poor practices due to better visibility and control. Overall, our concerns on supply chain standards contributed to decisions that limited our exposure in fashion.
5. Pricing of negative externalities in security prices
It was an interesting year for traditional “sin stocks”. Tobacco significantly outperformed the MSCI ACWI by 15%, but alcohol underperformed reflecting shifting societal social patterns. The tobacco outperformance was driven by easing menthol cigarette regulation in the US, solid earnings from new non-combustible products, showering investors with dividends and crucially coming off relatively low valuations into the year. While of course other areas of the economy have offered even higher performance, it provided a useful example for investors that human health impacts on share prices are not straight forward.

Another area of environmental impacts being priced into securities is through the labelled bond market. While 2025 was largely a year where the labelled bond market had volume retrenchment and a consolidation of quality, it was also the first year many sustainability-linked bonds (SLB) observation dates / KPI checkpoints became due. Criticised for the targets being too easy at issuance, it was interesting to see many companies fail these targets. Companies like Europcar, Legrand and A2A Eni all missed their targets with coupons rising modestly between 12.5 to 25 basis points. We continue to believe that sustainable linked bonds are an important accountability mechanism, helping to align financial outcomes with sustainability performance.
1Morgan Stanley: Korea’s Value-Up 2.0: Only Half the Story.
210 Years Post-Paris: How emissions decoupling has progressed; Energy and Climate Intelligence Unit.
3PFAS Litigation Could Generate Billions in Ground-Up Losses.
4The future of European competitiveness by Mario Draghi (2024).
5Federal Bank of Dallas (2025); Advances in AI will boost productivity, living standards over time.
