
2024: A rebound in M&A activity after a 3-year down cycle!
Since the end of 2023, headwinds to corporate confidence are reversing and all the drivers of the recovery are already in place for 2024:
Monetary easing on the horizon should enable financial buyers to return to the market.
The slowdown in growth and the gradual return of inflation to the 2% target, so eagerly awaited by the Federal Reserve (Fed), should enable the Fed to lower its key rates from June onwards. Even if rates remain elevated, the recent clarity on Fed cuts is expected to boost M&A activity. This is because it will make it easier and cheaper for companies to secure financing for their deals.Return to mega-deals, 8 deals worth over $10 billion were announced in the 1st quarter of 2024, compared with just 4 in the last quarter of 2023, driven by large US deals in the Energy, Technology and Financial sectors. The number of global operations announced in the first three months of the year totaled 92, up 48% on the same period last year. The return of “mega deals” is a clear sign of confidence among corporate leaders.
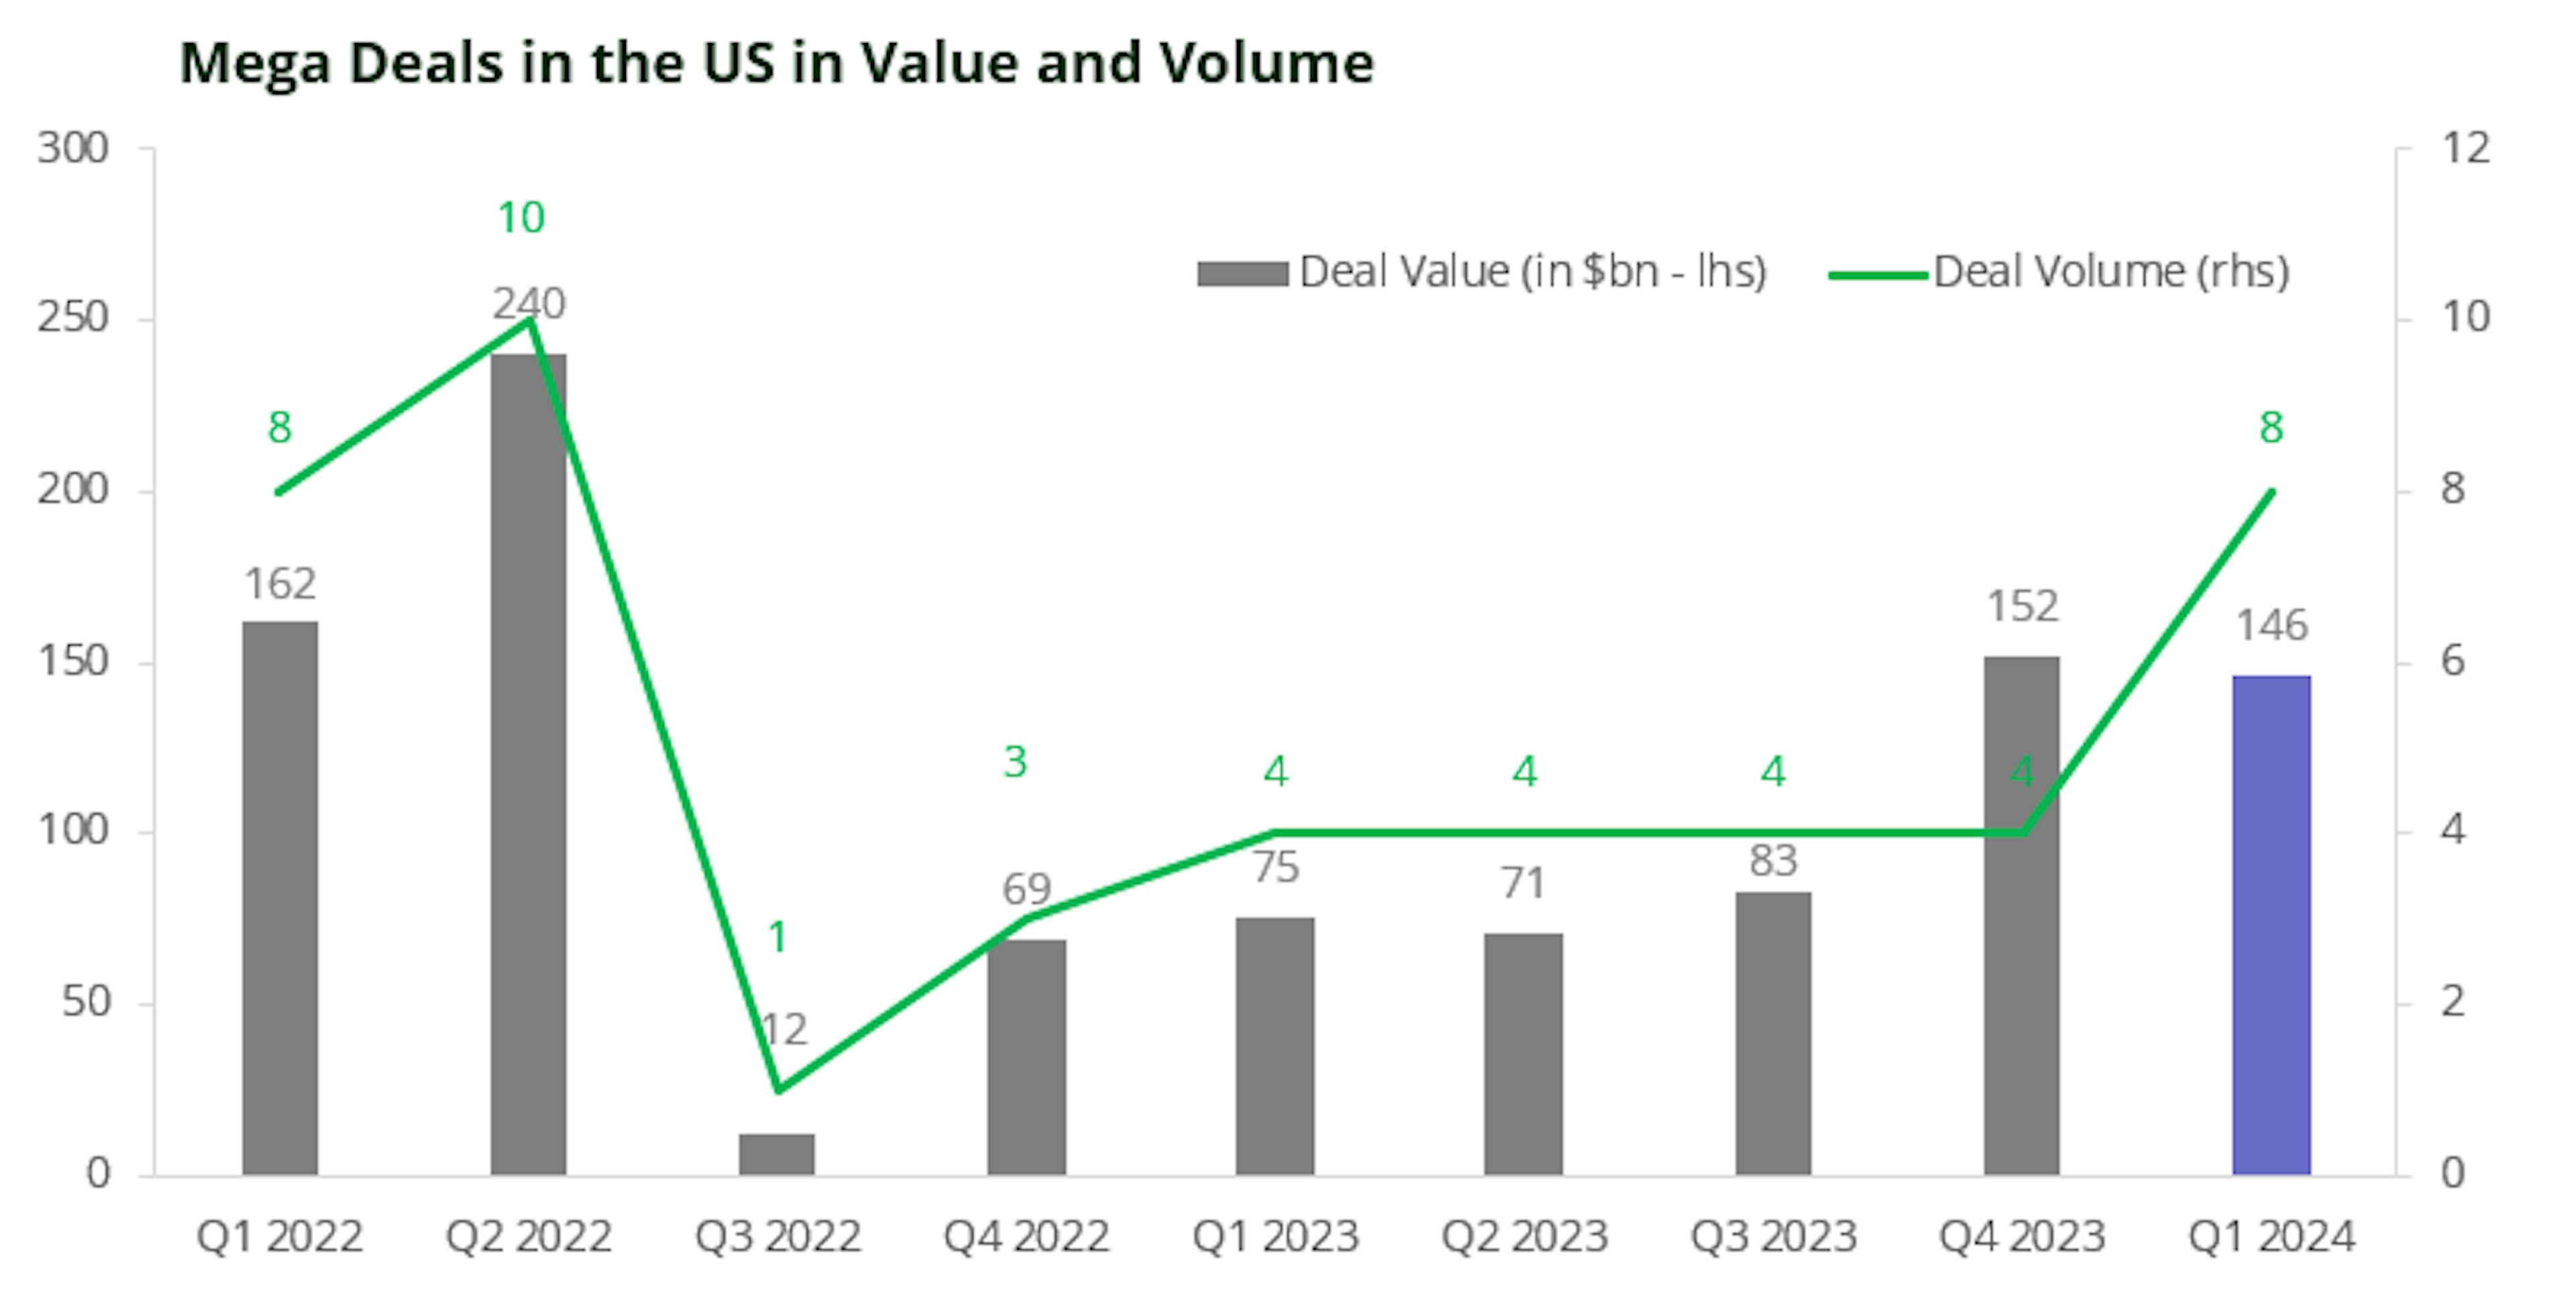
Sectoral shift in M&A activity towards the "old economy" driven by the energy transition, both in Europe and the USA. Three years of weak M&A activity have helped to begin preliminary discussions in strategic sectors such as artificial intelligence, cloud capabilities, clean energy transitions and/or reshoring which should support this cycle too.
New Japanese takeover guidelines, announced in August 2023, should drive business recovery in Asia and thus provide access to a potentially large reservoir of performance.
A higher Merger Arbitrage remuneration…
- We have now more attractive merger arbitrage spreads. Spreads have started to reflect rising rates and repricing of risk premium. The M&A risk premium is the risk that the deal is not completed but note that this risk is idiosyncratic as they are deal specific.
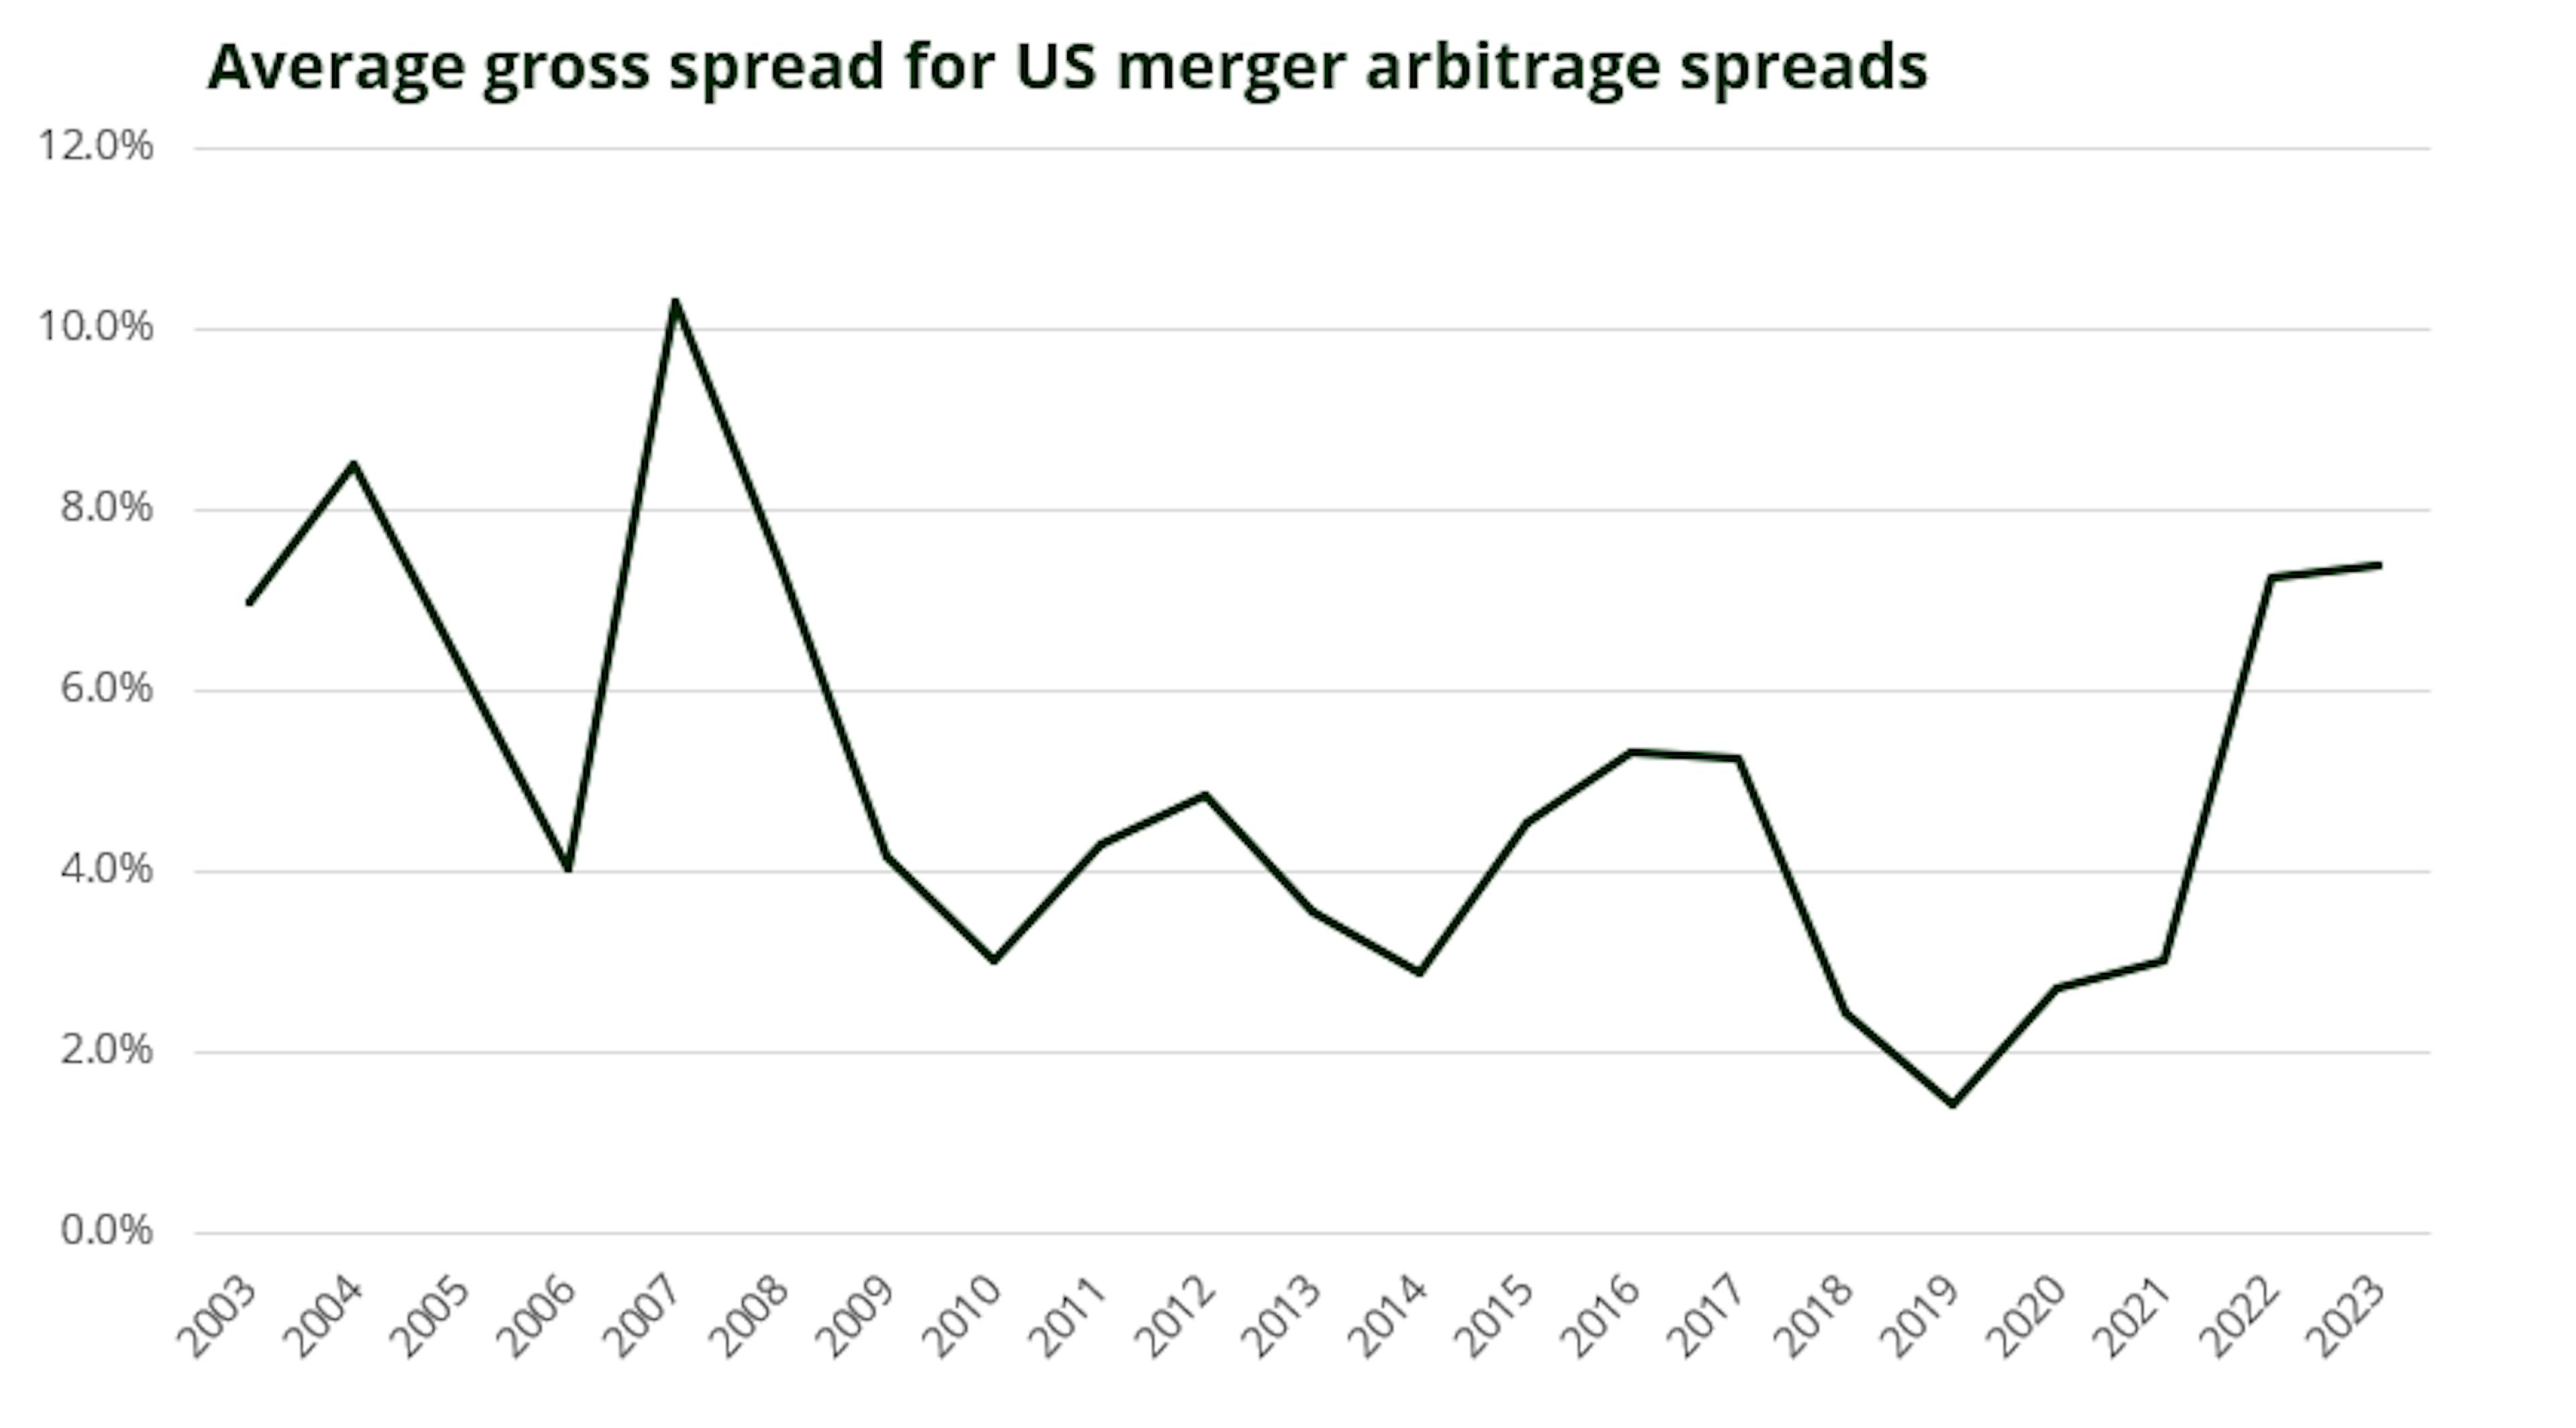
- The advantage of having higher risk-free rates and moving away from a zero/negative rate environment enables better remuneration for each operation.
…along with lower termination rates
We are currently at termination rate levels close to historical lows. In other words, the risk of an M&A deal being abandoned is much lower than in previous years. Hence, this means that we are now better remunerated for less termination risk.
For example, the percentage of a deal failure has been reduced thanks to greater clarity on interpretation of antitrust laws. This greater visibility is crucial in M&A to determine what types of deal will be challenged in the future and the length of time/costs this may entail.
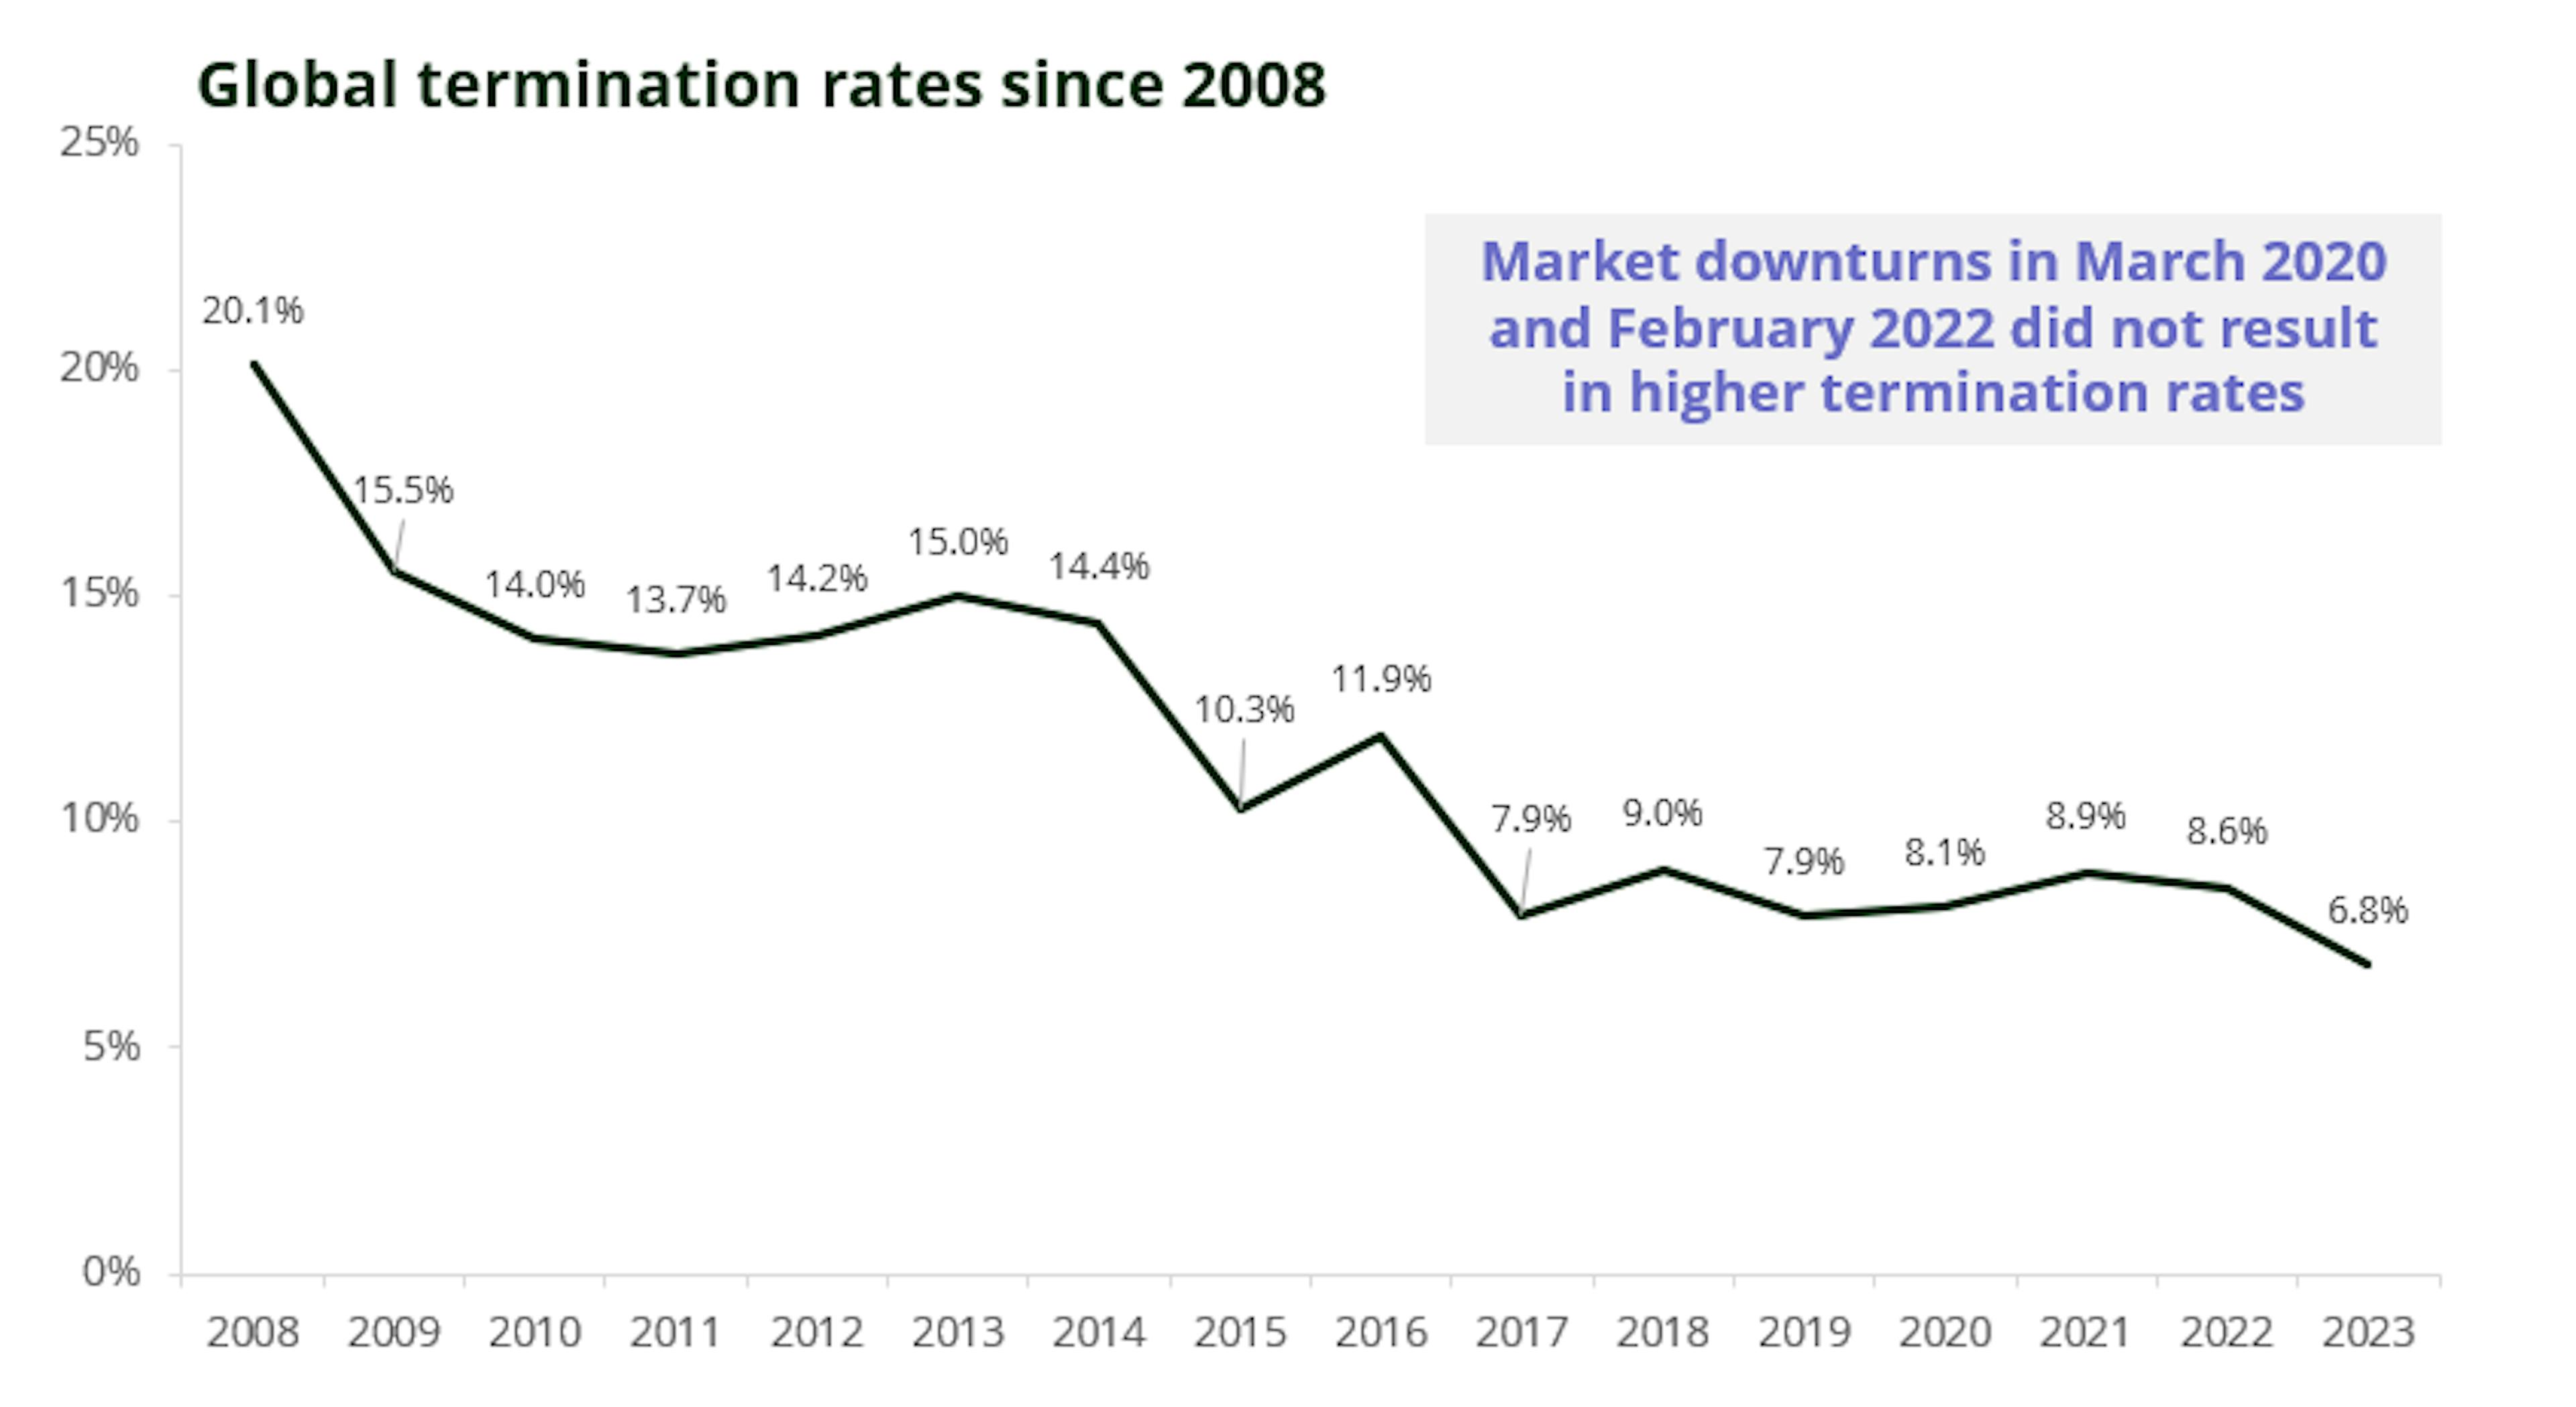
- Finally, now that fear of recession is no longer the central scenario, and we are operating in an environment of lower inflation and resilient growth, the return of investor confidence since the end of 2023 should continue to foster this buoyant environment and maintain low termination rates.
and lastly increased bids are back!
- The first three months of the year have already seen a number of outbids: as an example, in January, the Swedish IT services company Pagero Group was the subject of a battle between three players in the sector (Avalara, Thomson Reuters, Vertex), which resulted in the terms of the offer being improved by almost 39%.
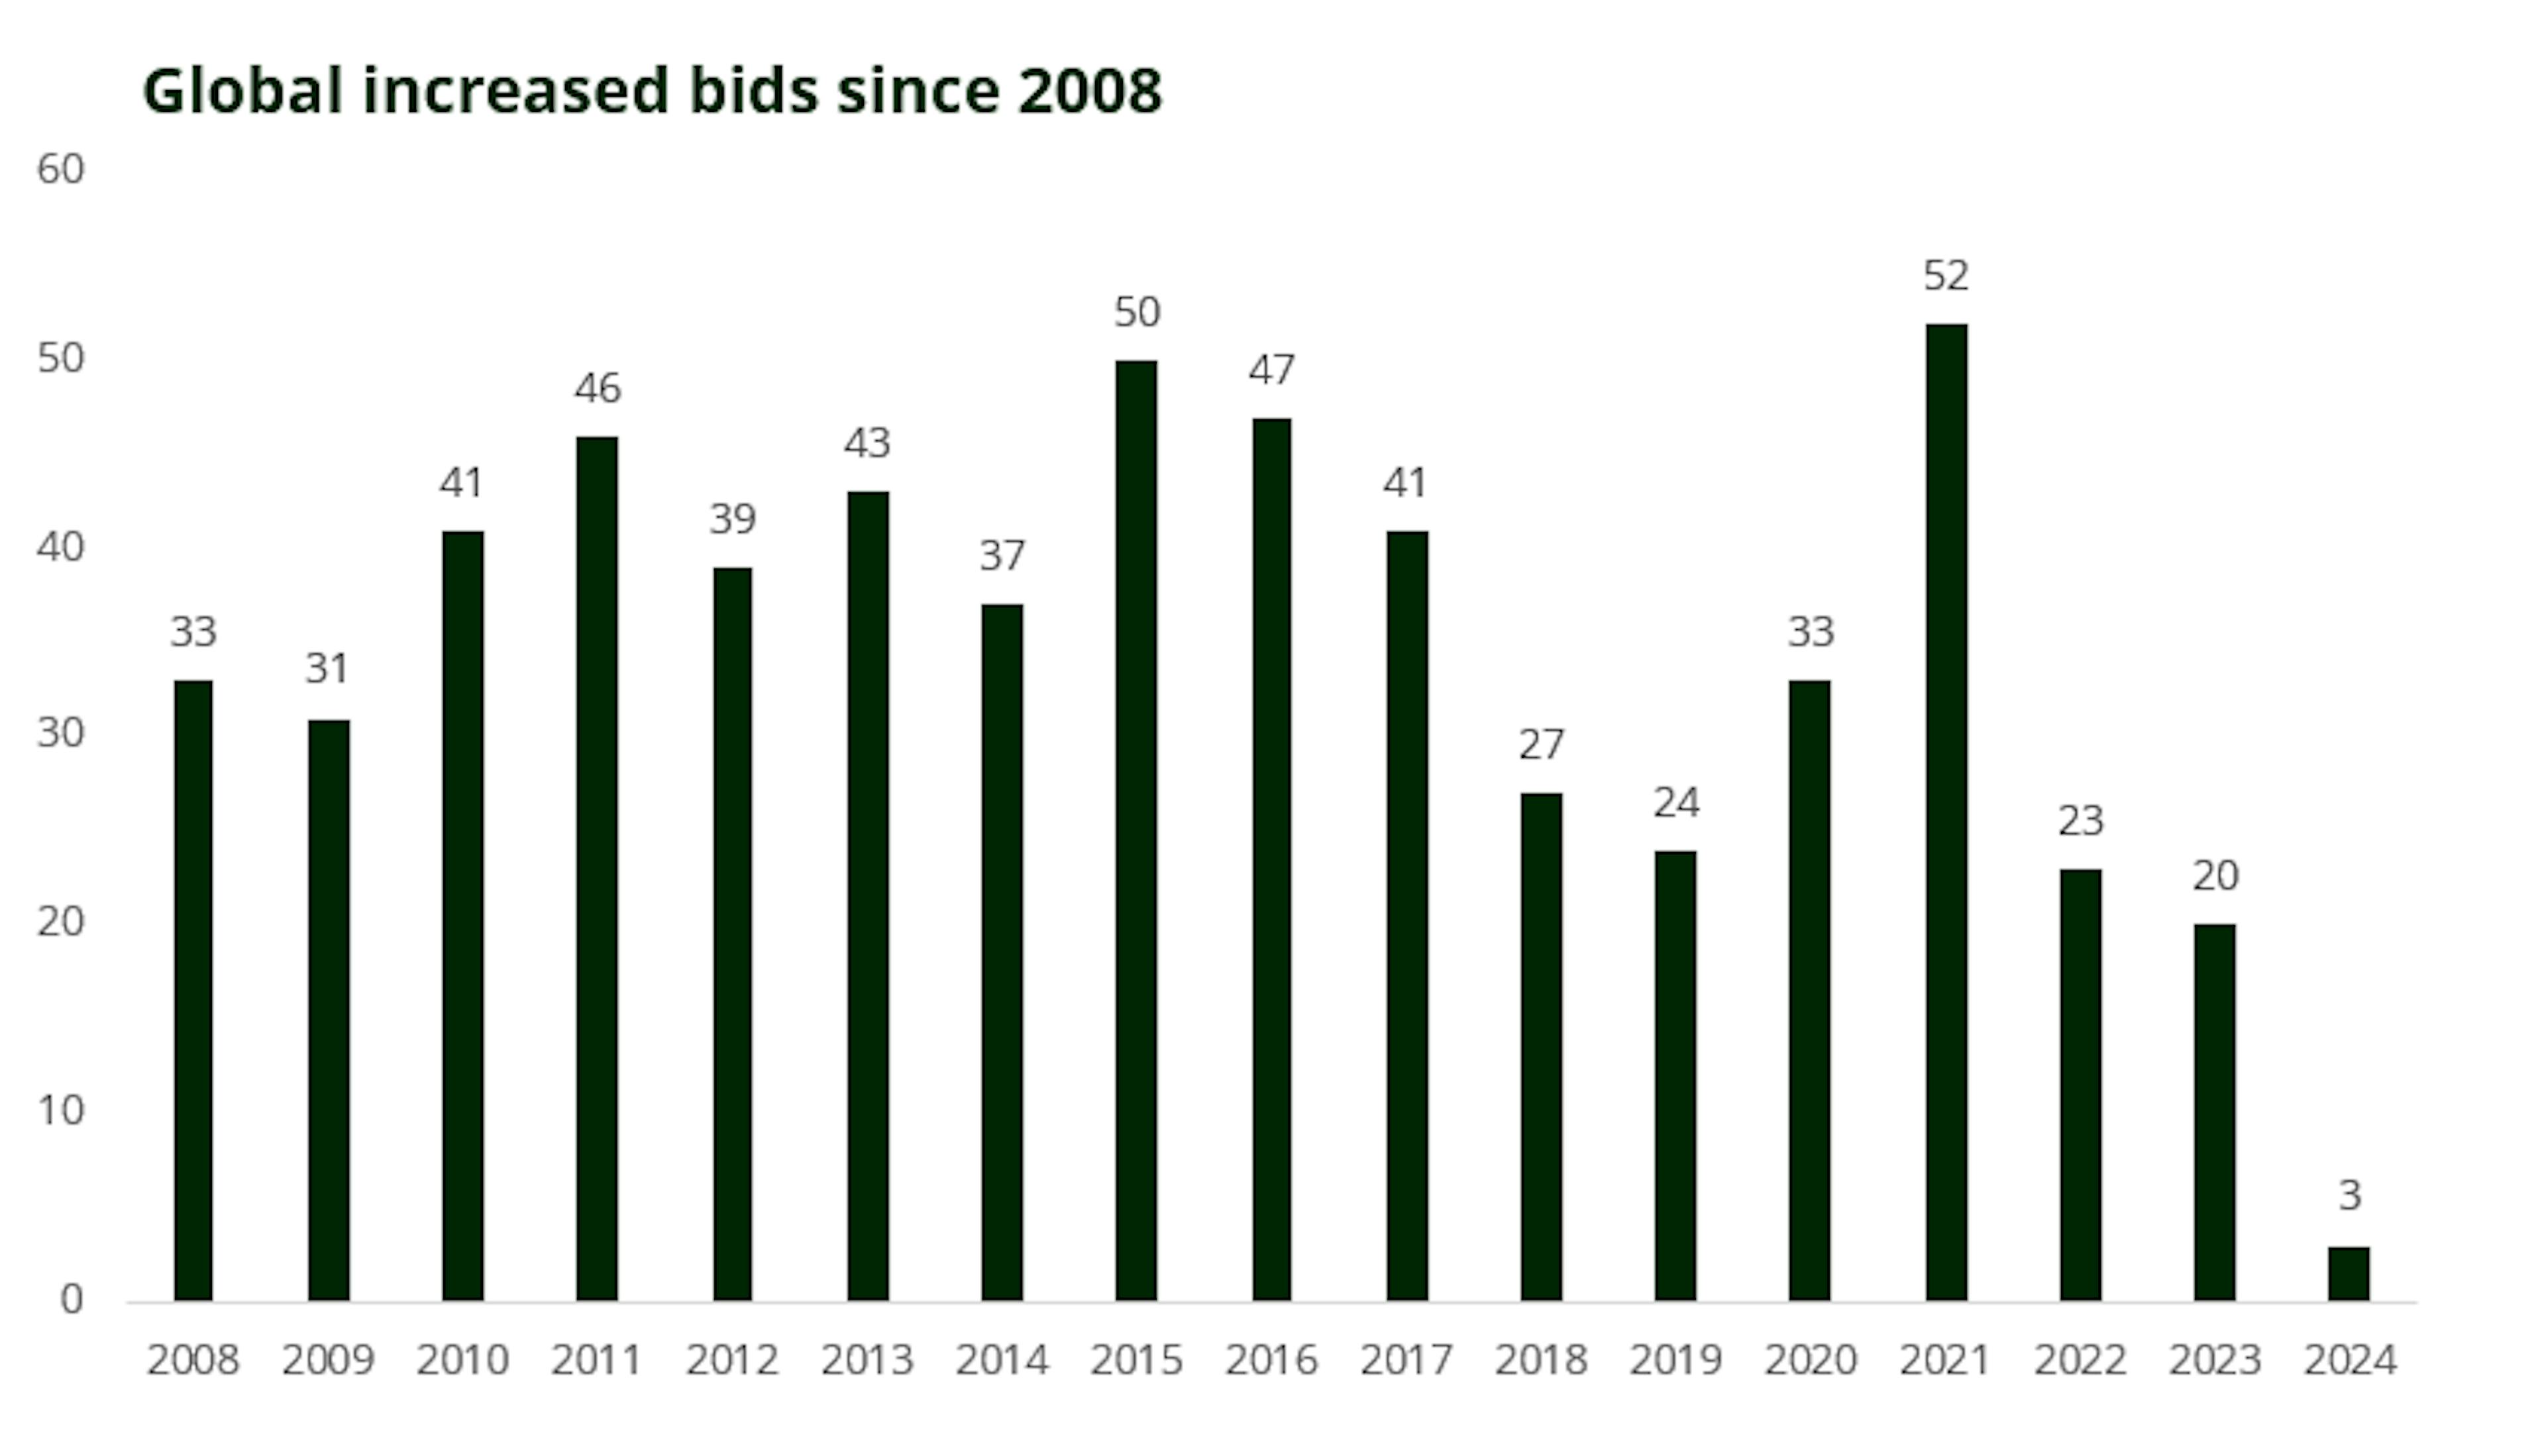
In February, the shipping company CMA CGM saw its bid for the British logistics services company, Wincanton countered by a 37% higher offer from the American company, GXO Logistics.
Finally, still in the UK, equipment manufacturer, Spirent Communications is being coveted by two industry players, Keysight Technologies and Viavi Solutions. The target's shares climbed 12% over the terms of the first offer during March.
Carmignac Portfolio Merger Arbitrage Plus I EUR Acc
- Recommended minimum investment horizon
- 3 years
- Risk indicator*
- 2/7
- SFDR - Fund Classification**
- Article 8
*Risk Scale from the KID (Key Information Document). Risk 1 does not mean a risk-free investment. This indicator may change over time. **Sustainable Finance Disclosure Regulation (SFDR) 2019/2088. The SFDR classification of the Funds may change over time.
Main risks of the fund
Fees
- Entry costs
- We do not charge an entry fee.
- Exit costs
- We do not charge an exit fee for this product.
- Management fees and other administrative or operating costs
- 1,12 % of the value of your investment per year. This estimate is based on actual costs over the past year.
- Performance fees
- 20,00 % max. of the outperformance if the performance is positive and the net asset value exceeds the high-water mark. The actual amount will vary depending on how well your investment performs. The aggregated cost estimation above includes the average over the last 5 years, or since the product creation if it is less than 5 years.
- Transaction Cost
- 0,23 % of the value of your investment per year. This is an estimate of the costs incurred when we buy and sell the investments underlying the product. The actual amount varies depending on the quantity we buy and sell.