
Three years after launch, Carmignac Portfolio Merger Arbitrage Plus has demonstrated its ability to deliver consistent, low volatility returns across different market environments. M&A is back at near-decade highs, corporates are chasing scale, and the positive optionality of competitive bidding is alive. Since inception, the Fund has attained the mark of €245M returning 12.98%1, equating to an annualized performance of 4.20% with a volatility of less than 2%. Its equity beta of 0.03 underscores its minimal sensitivity to market movements, reinforcing its role as a robust, uncorrelated strategy within a diversified portfolio.
3 YEARS IN FOCUS
DEAL FLOW IS THE FUEL OF MERGER ARBITRAGE
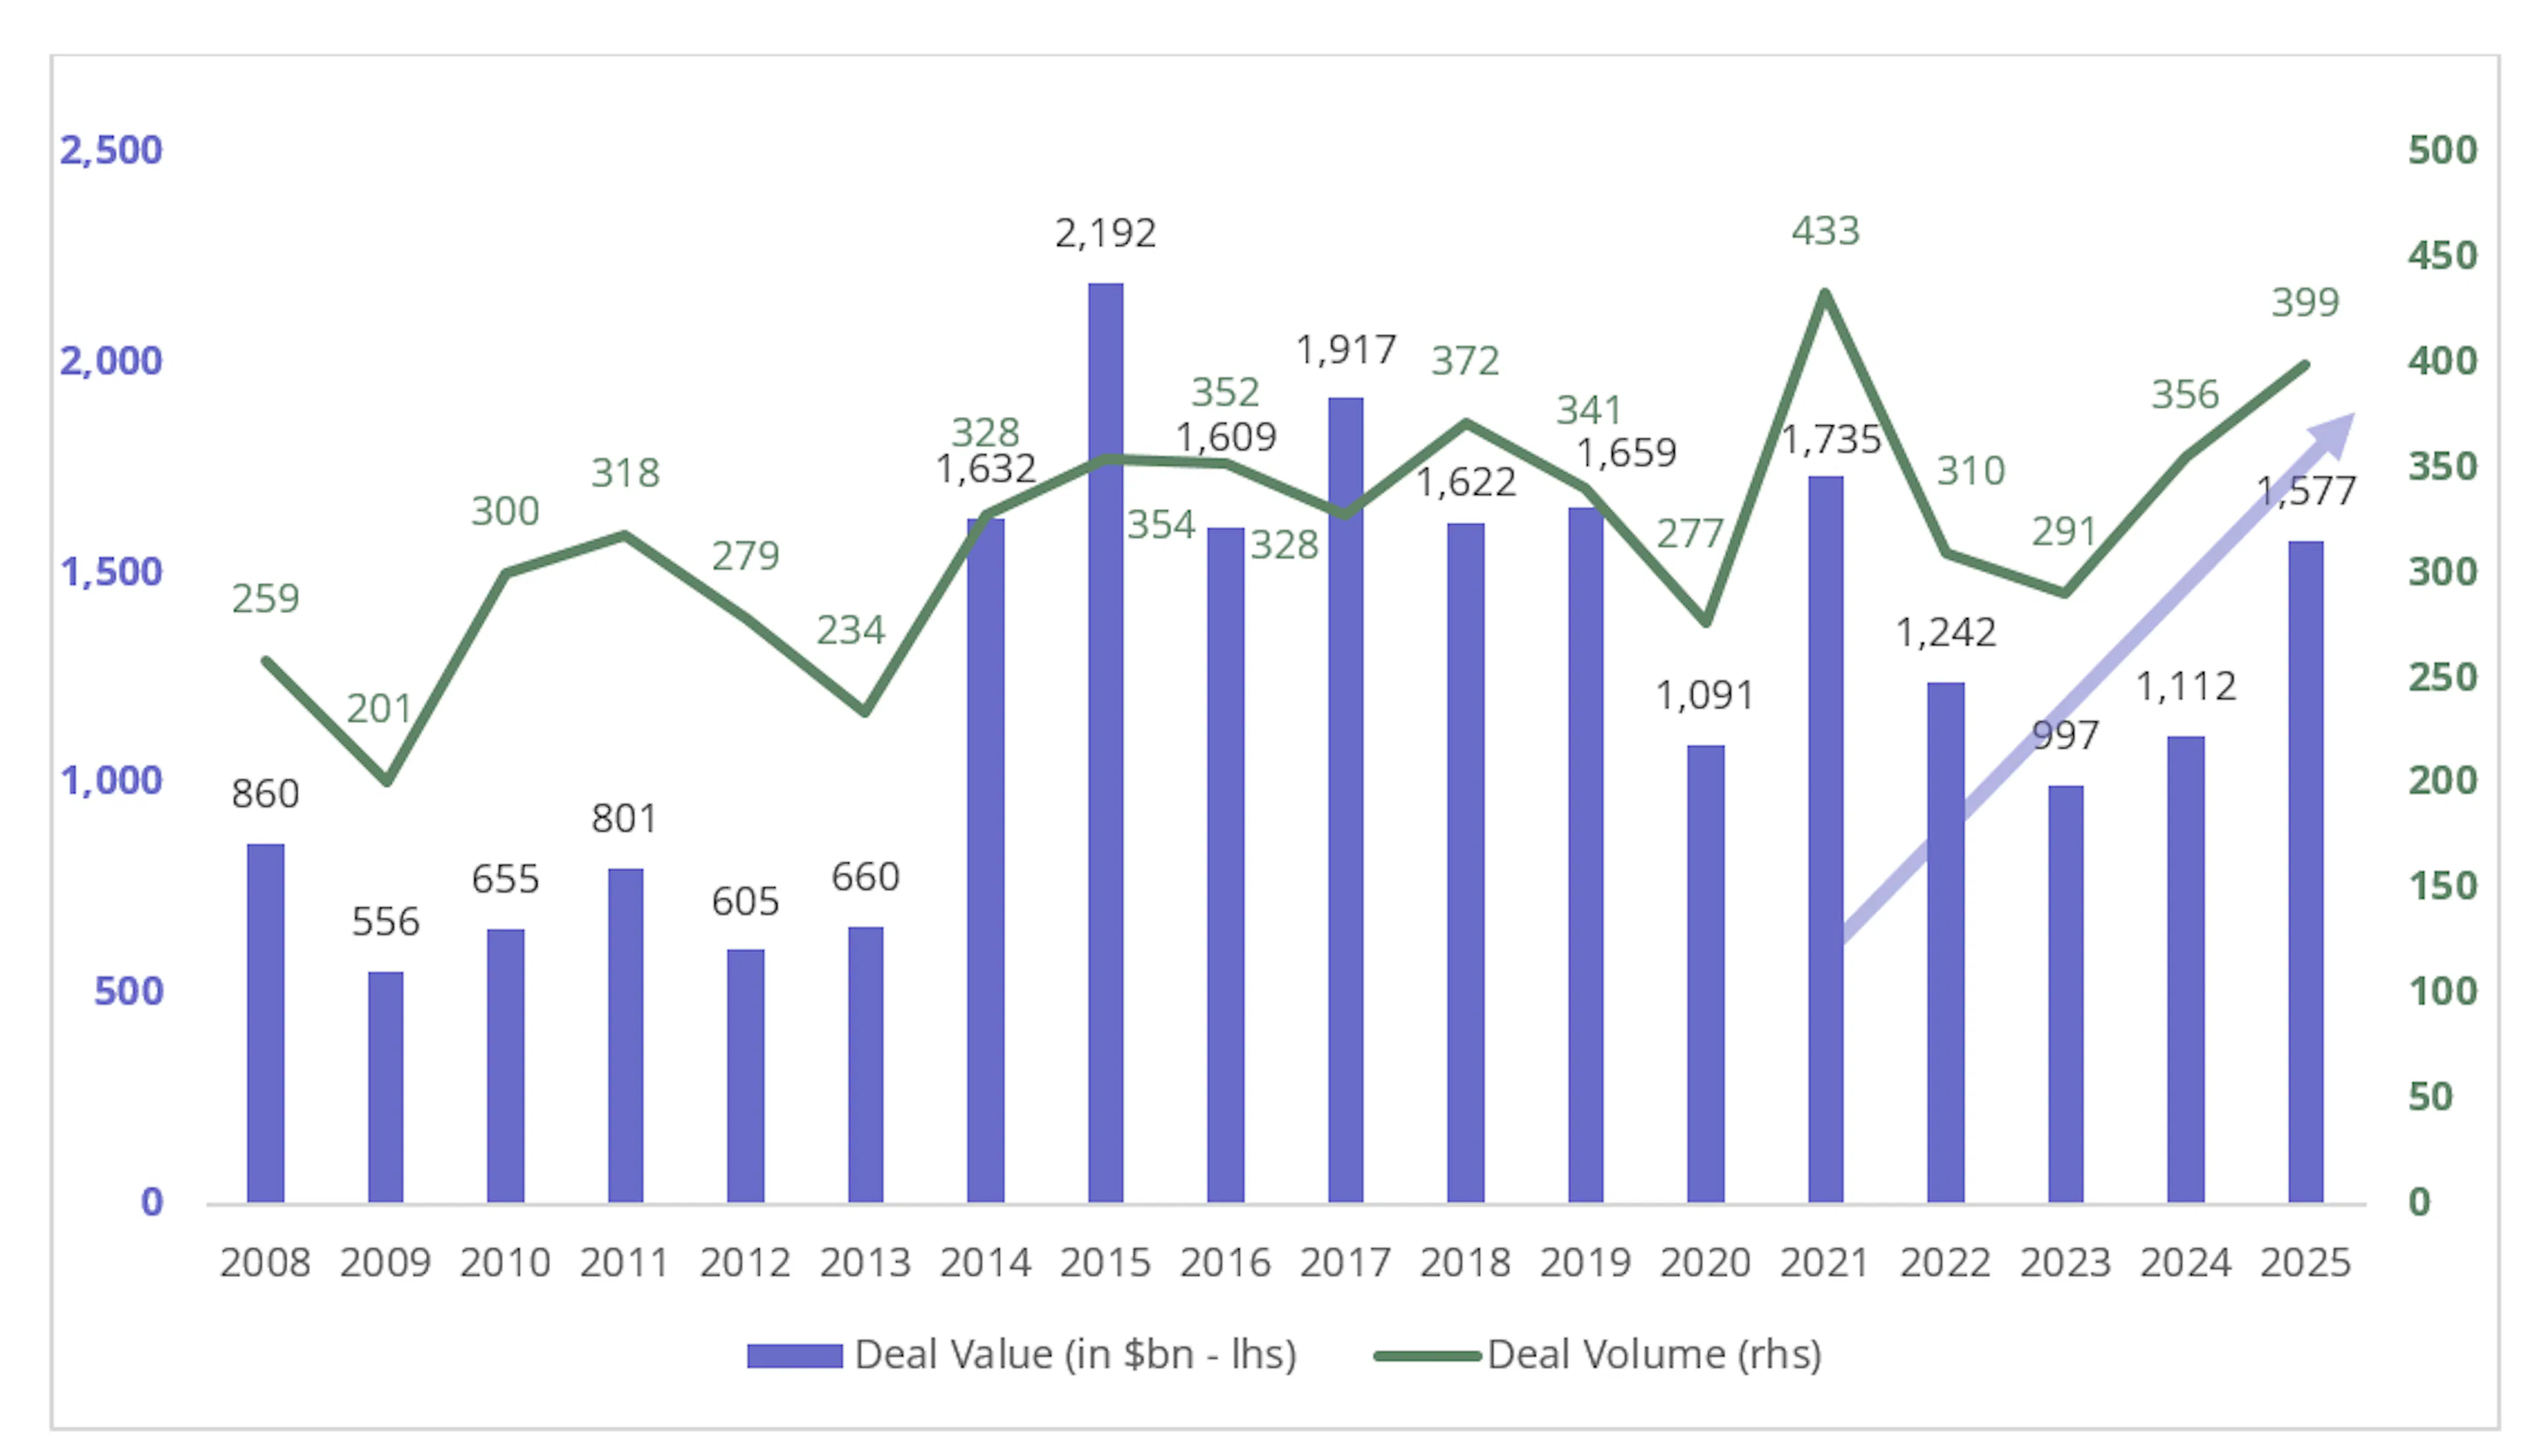
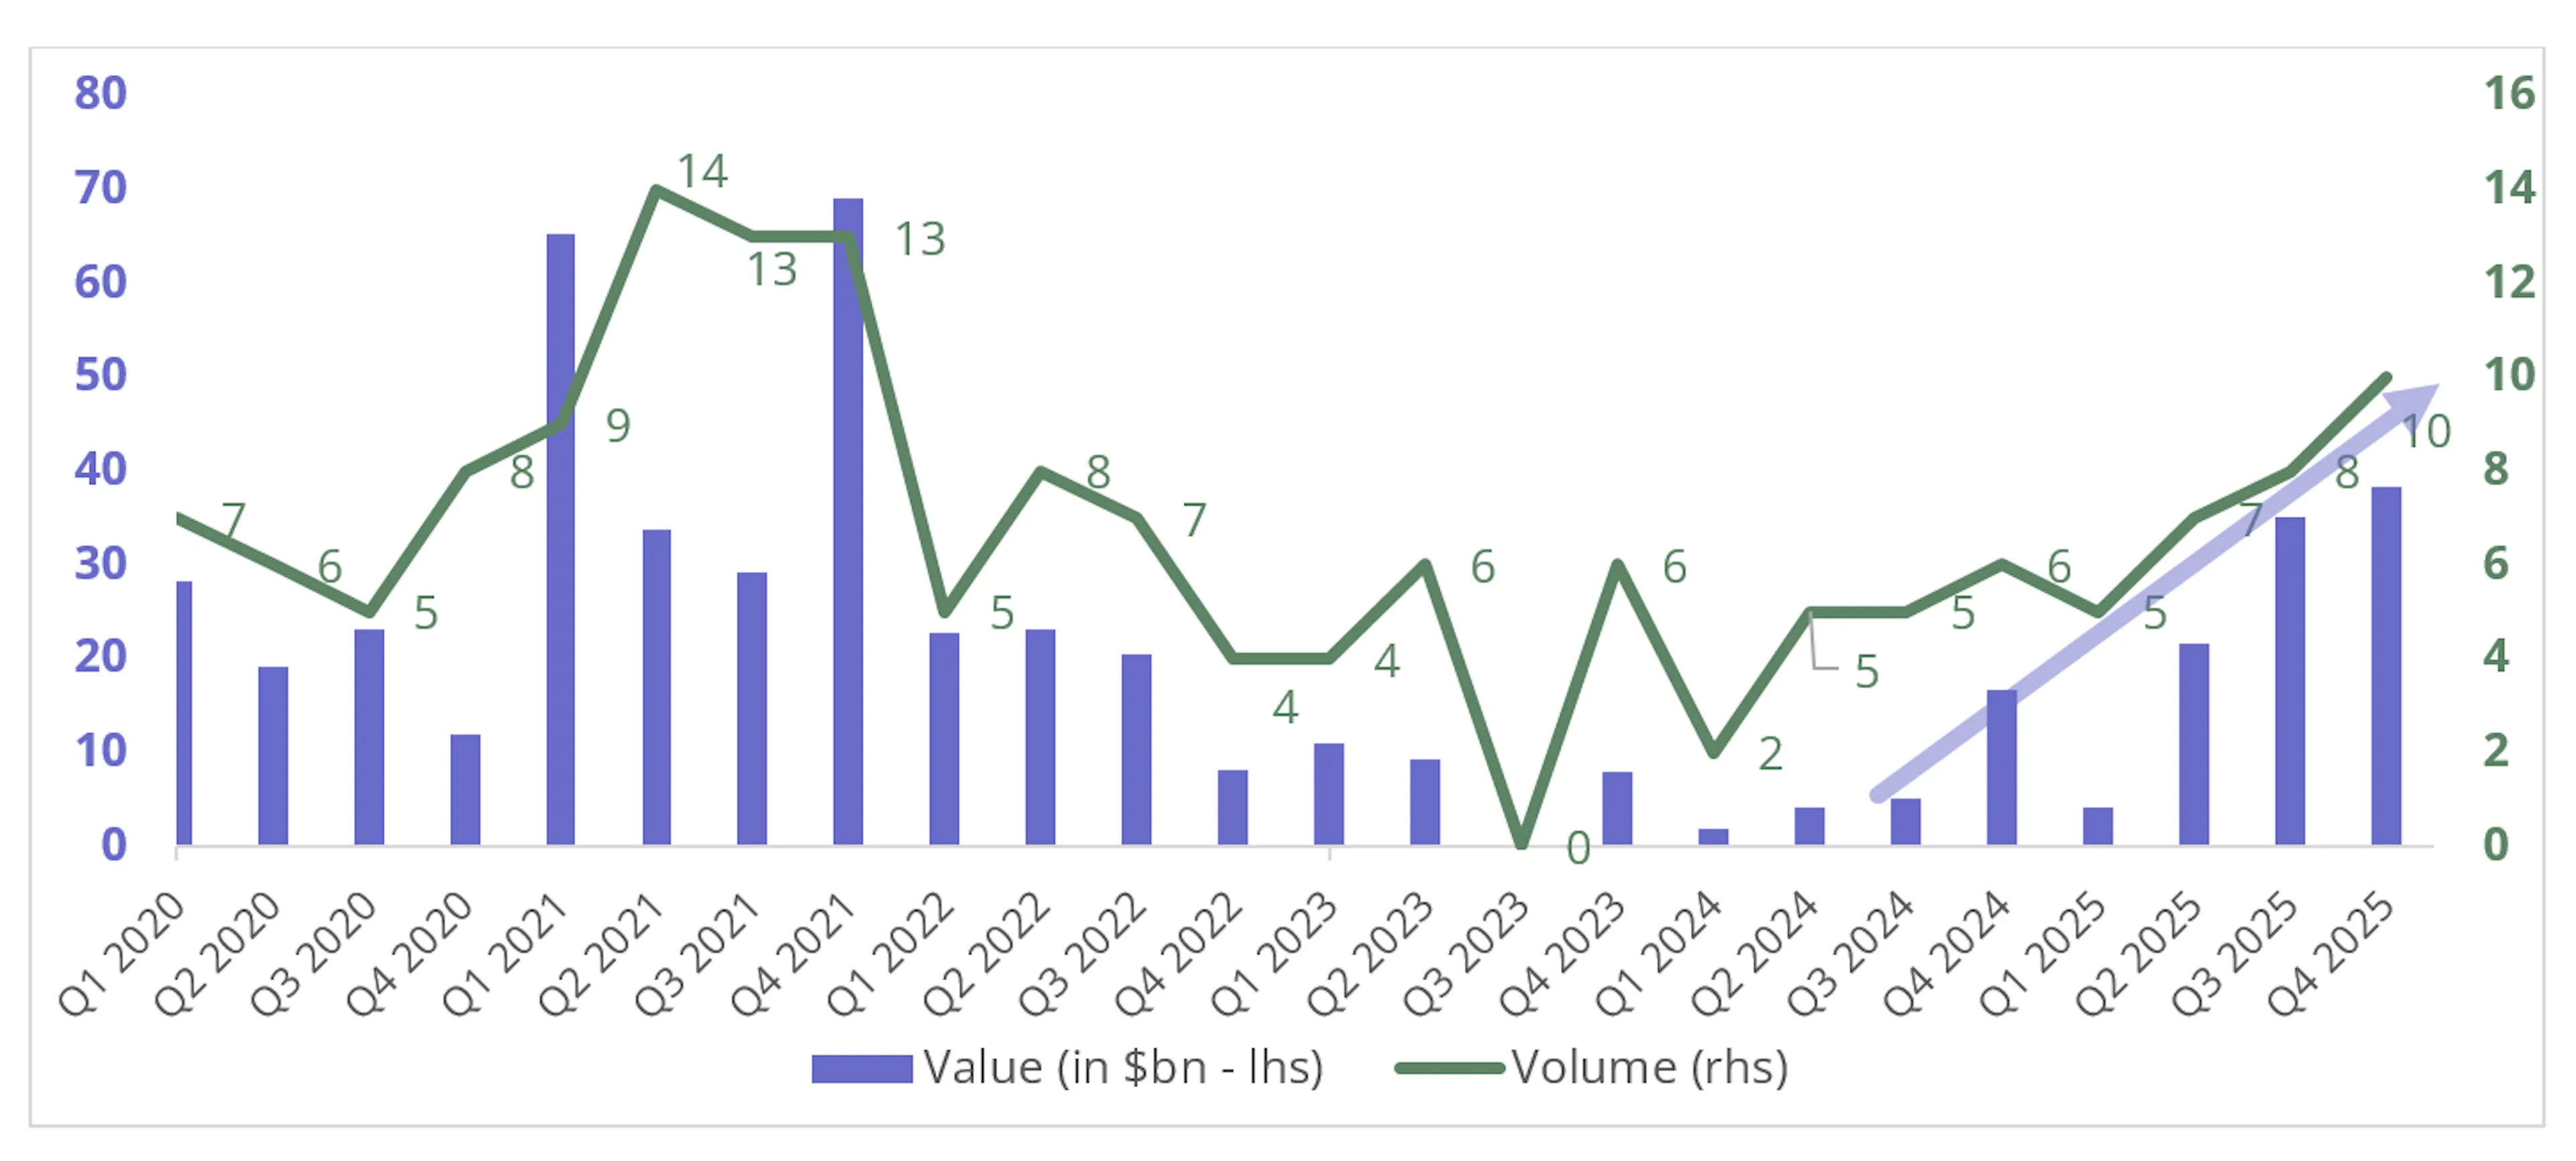
The M&A market has roared back. Global deal value surged 42%2 in 2025, the most active year since 2021 powered by a strong number of mega deals in the last two quarters. We expect a sustained deal activity in 2026, fuelled by AI-driven consolidation, private equity dry powder levels, and a friendlier regulatory backdrop on both sides of the Atlantic.
More deals mean more opportunities across tech megamergers, European consolidation and carve-outs. Critically, spreads remain attractive: UBS reported median annualised merger arbitrage spreads of ~4% in the US at end-20253. This dual dynamic is historically rare. Elevated deal activity typically compresses spreads as capital rushes in. Today, structural complexity cross-border financing conditions, regulatory friction, geopolitical overlays are keeping spreads wide even as activity accelerates. For investors, this creates a rare but favourable opportunity: more transactions and better remuneration.
A PROVEN DIVERSIFIER IN VOLATILE MARKETS
The strategy's edge lies in its independence. Merger arbitrage returns are driven by deal outcomes, not market direction and that distinction proved its worth in recent volatile markets. During Liberation Day and the Iran escalation, equity volatility spiked and correlations rose across while our traditional asset classes. Our portfolio showed resilience. That resilience is not accidental, it reflects a team with over 25 years of experience, a strict deal selection process, and rigorous and disciplined risk management. As markets consolidate and M&A activity continues to accelerate, this strategy stands out as a true diversifier with an improving fundamental backdrop.

COMPETITIVE DEAL DYNAMICS: BIDDING WARS AND IMPROVED TERMS
The cherry on the cake is optionality. The conditions for this are structurally favourable: deal terminations remain at historic lows, valuations are attractive enough to incentivise competing bids, and private equity firm are holding a significant amount of undeployed capital and actively looking to deploy. We can also highlight a more cooperative anti-trust over the globe, cross-border strategic appetite at multi-year highs and activist shareholders increasingly pushing boards to run competitive processes and the probability of a bump in any given position is meaningfully elevated. In other words, merger arbitrage offers not only resilience and decorrelation but also embedded upside when competitive dynamics push good deals to become even better deals.
Three years after launch, Carmignac Portfolio Merger Arbitrage Plus benefits from proven resilience and a rapidly improving opportunity set.
In a world of persistent uncertainty and elevated correlations, strategies driven by idiosyncratic corporate events offer a compelling alternative. The combination of increased deal flow, attractive spreads and embedded optionality makes this a particularly timely moment to consider merger arbitrage and we believe our Fund is well positioned to capture these opportunities.
1Source: Carmignac, Bloomberg Data as of 31/03/2026. The Fund was launched on 14/04/2023.
2Source: Carmignac, Bloomberg. Data as of 31/03/2026.
3Source: UBS Special Sits, Bloomberg as of 31/12/2025. Mergers with an equity value in excess of $400 million involving publicly-traded targets in the US. Arbitrage spreads are net spreads (net of dividends, optionality, short rebate) on a LIBOR-adjusted basis for definitive deals with more than 5 days to expected closing and where the annualized spread is between 0% and 30%.
Carmignac Portfolio Merger Arbitrage Plus
Carmignac Portfolio Merger Arbitrage Plus I EUR Acc
- Recommended minimum investment horizon
- 3 years
- Risk indicator*
- 3/7
- SFDR - Fund Classification**
- Article 8
*Risk Scale from the KIID (Key Investor Information Document). Risk 1 does not mean a risk-free investment. This indicator may change over time. **Sustainable Finance Disclosure Regulation (SFDR) 2019/2088. The SFDR classification of the Funds may change over time.
Main risks of the fund
Fees
- Maximum subscription fees paid to distributors
- -
- Redemption Fees
- -
- Conversion Fee
- -
- Ongoing Charges
- 1.12%
- Management Fees
- 1.00% MAX
- Performance Fees
- 20.00% of the outperformance to the reference indicator over the year. Performance fee is not charged until previous underperformance is offset
Footnote
Performance
| Carmignac Portfolio Merger Arbitrage Plus | +1.0 | +4.6 | +3.7 | +3.2 |
| Carmignac Portfolio Merger Arbitrage Plus | +4.5% | - | +4.2% |
Source: Carmignac at 31 Mar 2026.
Date of 1st NAV : 14/04/2023.
Past performance is not necessarily indicative of future performance. Performances are net of fees (excluding possible entrance fees charged by the distributor). The Fund presents a risk of loss of capital.
The return may increase or decrease as a result of currency fluctuations, for the shares which are not currency-hedged.
Reference Indicator: -