Sustainable bonds: an investment opportunity?
As an active investor who commits to integrate Environmental, Social and Governance (ESG) considerations into our portfolios, Carmignac invests in sustainable bonds.
What are sustainable bonds?
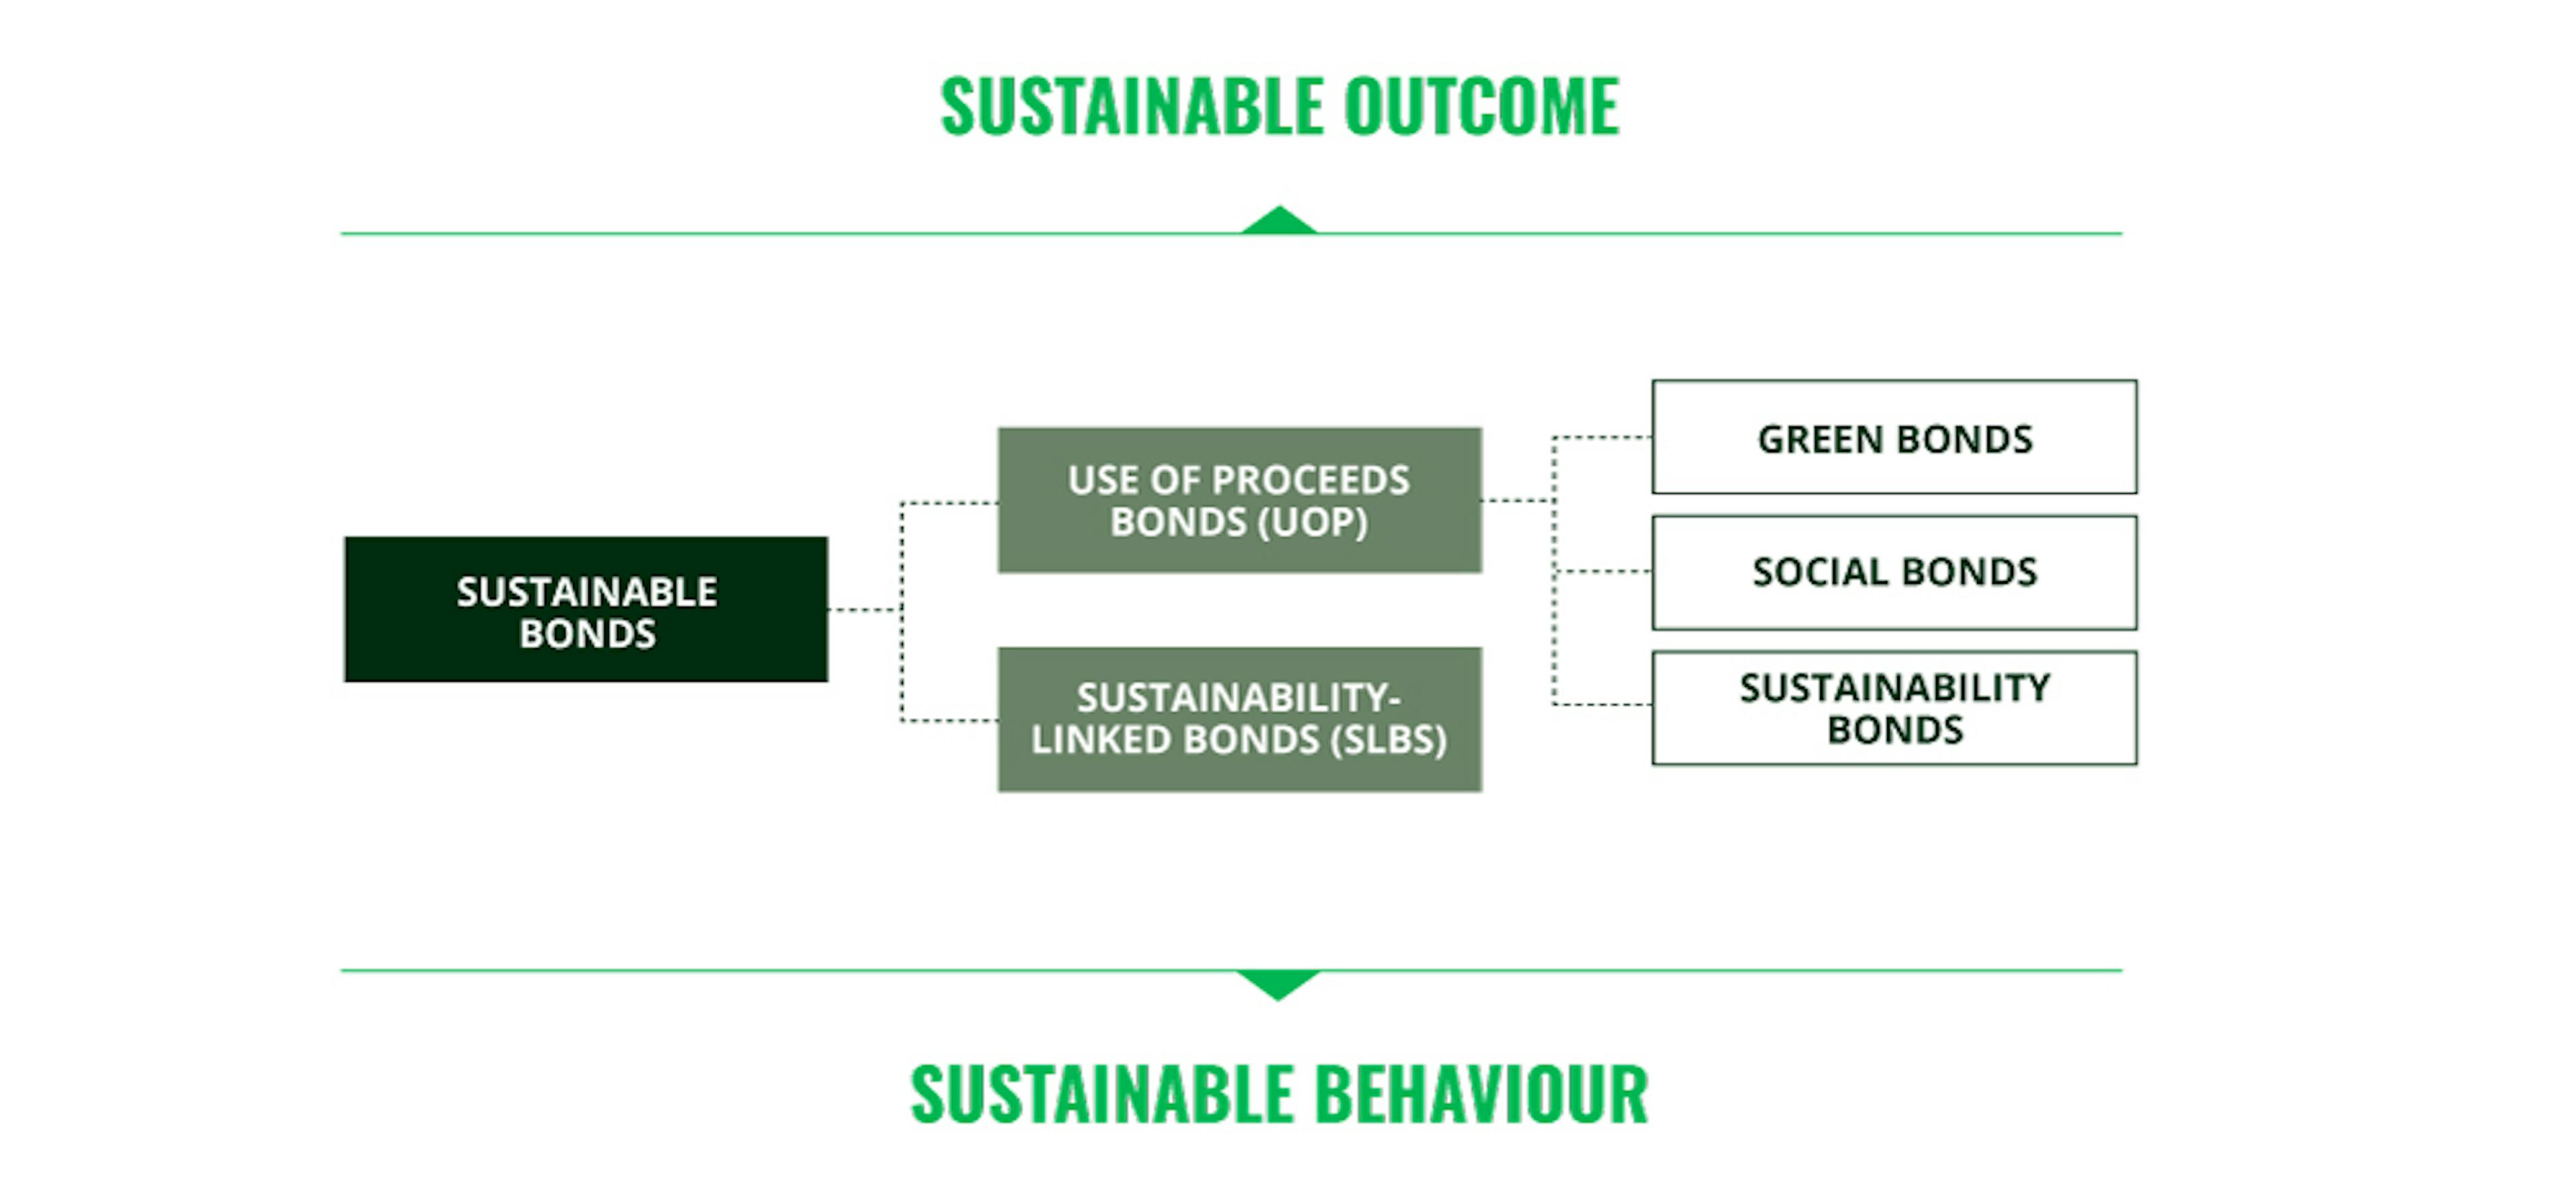
Used interchangeably with other terminologies such as “GSS+ bonds” (Green, Social, Sustainable and other labelled bonds) or “ESG bonds”, sustainable bonds are debt securities issued by public or private entities which integrate ESG considerations either through:
A “Use of Proceeds” approach (for UoP bonds): where the issuer commits to use the proceeds raised for a defined environmental and/ or social project. Under this category we mainly find green, social and sustainability bonds. Blue and transition bonds also fall under this category.
Sustainability targets (for SLBs): the proceeds raised are used for general corporate purposes and are not ring-fenced to any specific environmental and/ or social project. However, at the time of the issuance, the issuer chooses one or several sustainability “Key Performance Indicator(s)” (KPI) and “Sustainability Performance Target(s)” (SPT) which it commits to achieve by a “target observation date”. If the issuer misses the SPT, it is, most often, penalised by the triggering of a “coupon step-up” or “premium” for the rest of the life of the bond.
Are sustainable bonds here to stay?
We believe that sustainable bonds can play an important role in contributing to the allocation of capital towards defined environmental and/ or social goals (for UoP bonds) as well as in incentivising issuers to improve their behaviour by linking the cost of financing to sustainability commitments (for SLBs).
As indicated below, 2021 has so far been the peak year for the issuance of sustainable bonds. In 2023, we have observed a slight increase compared to 2022 (3%1), which experienced a significant drop compared to the high levels seen in 2021.
Global issuance of sustainable bonds:
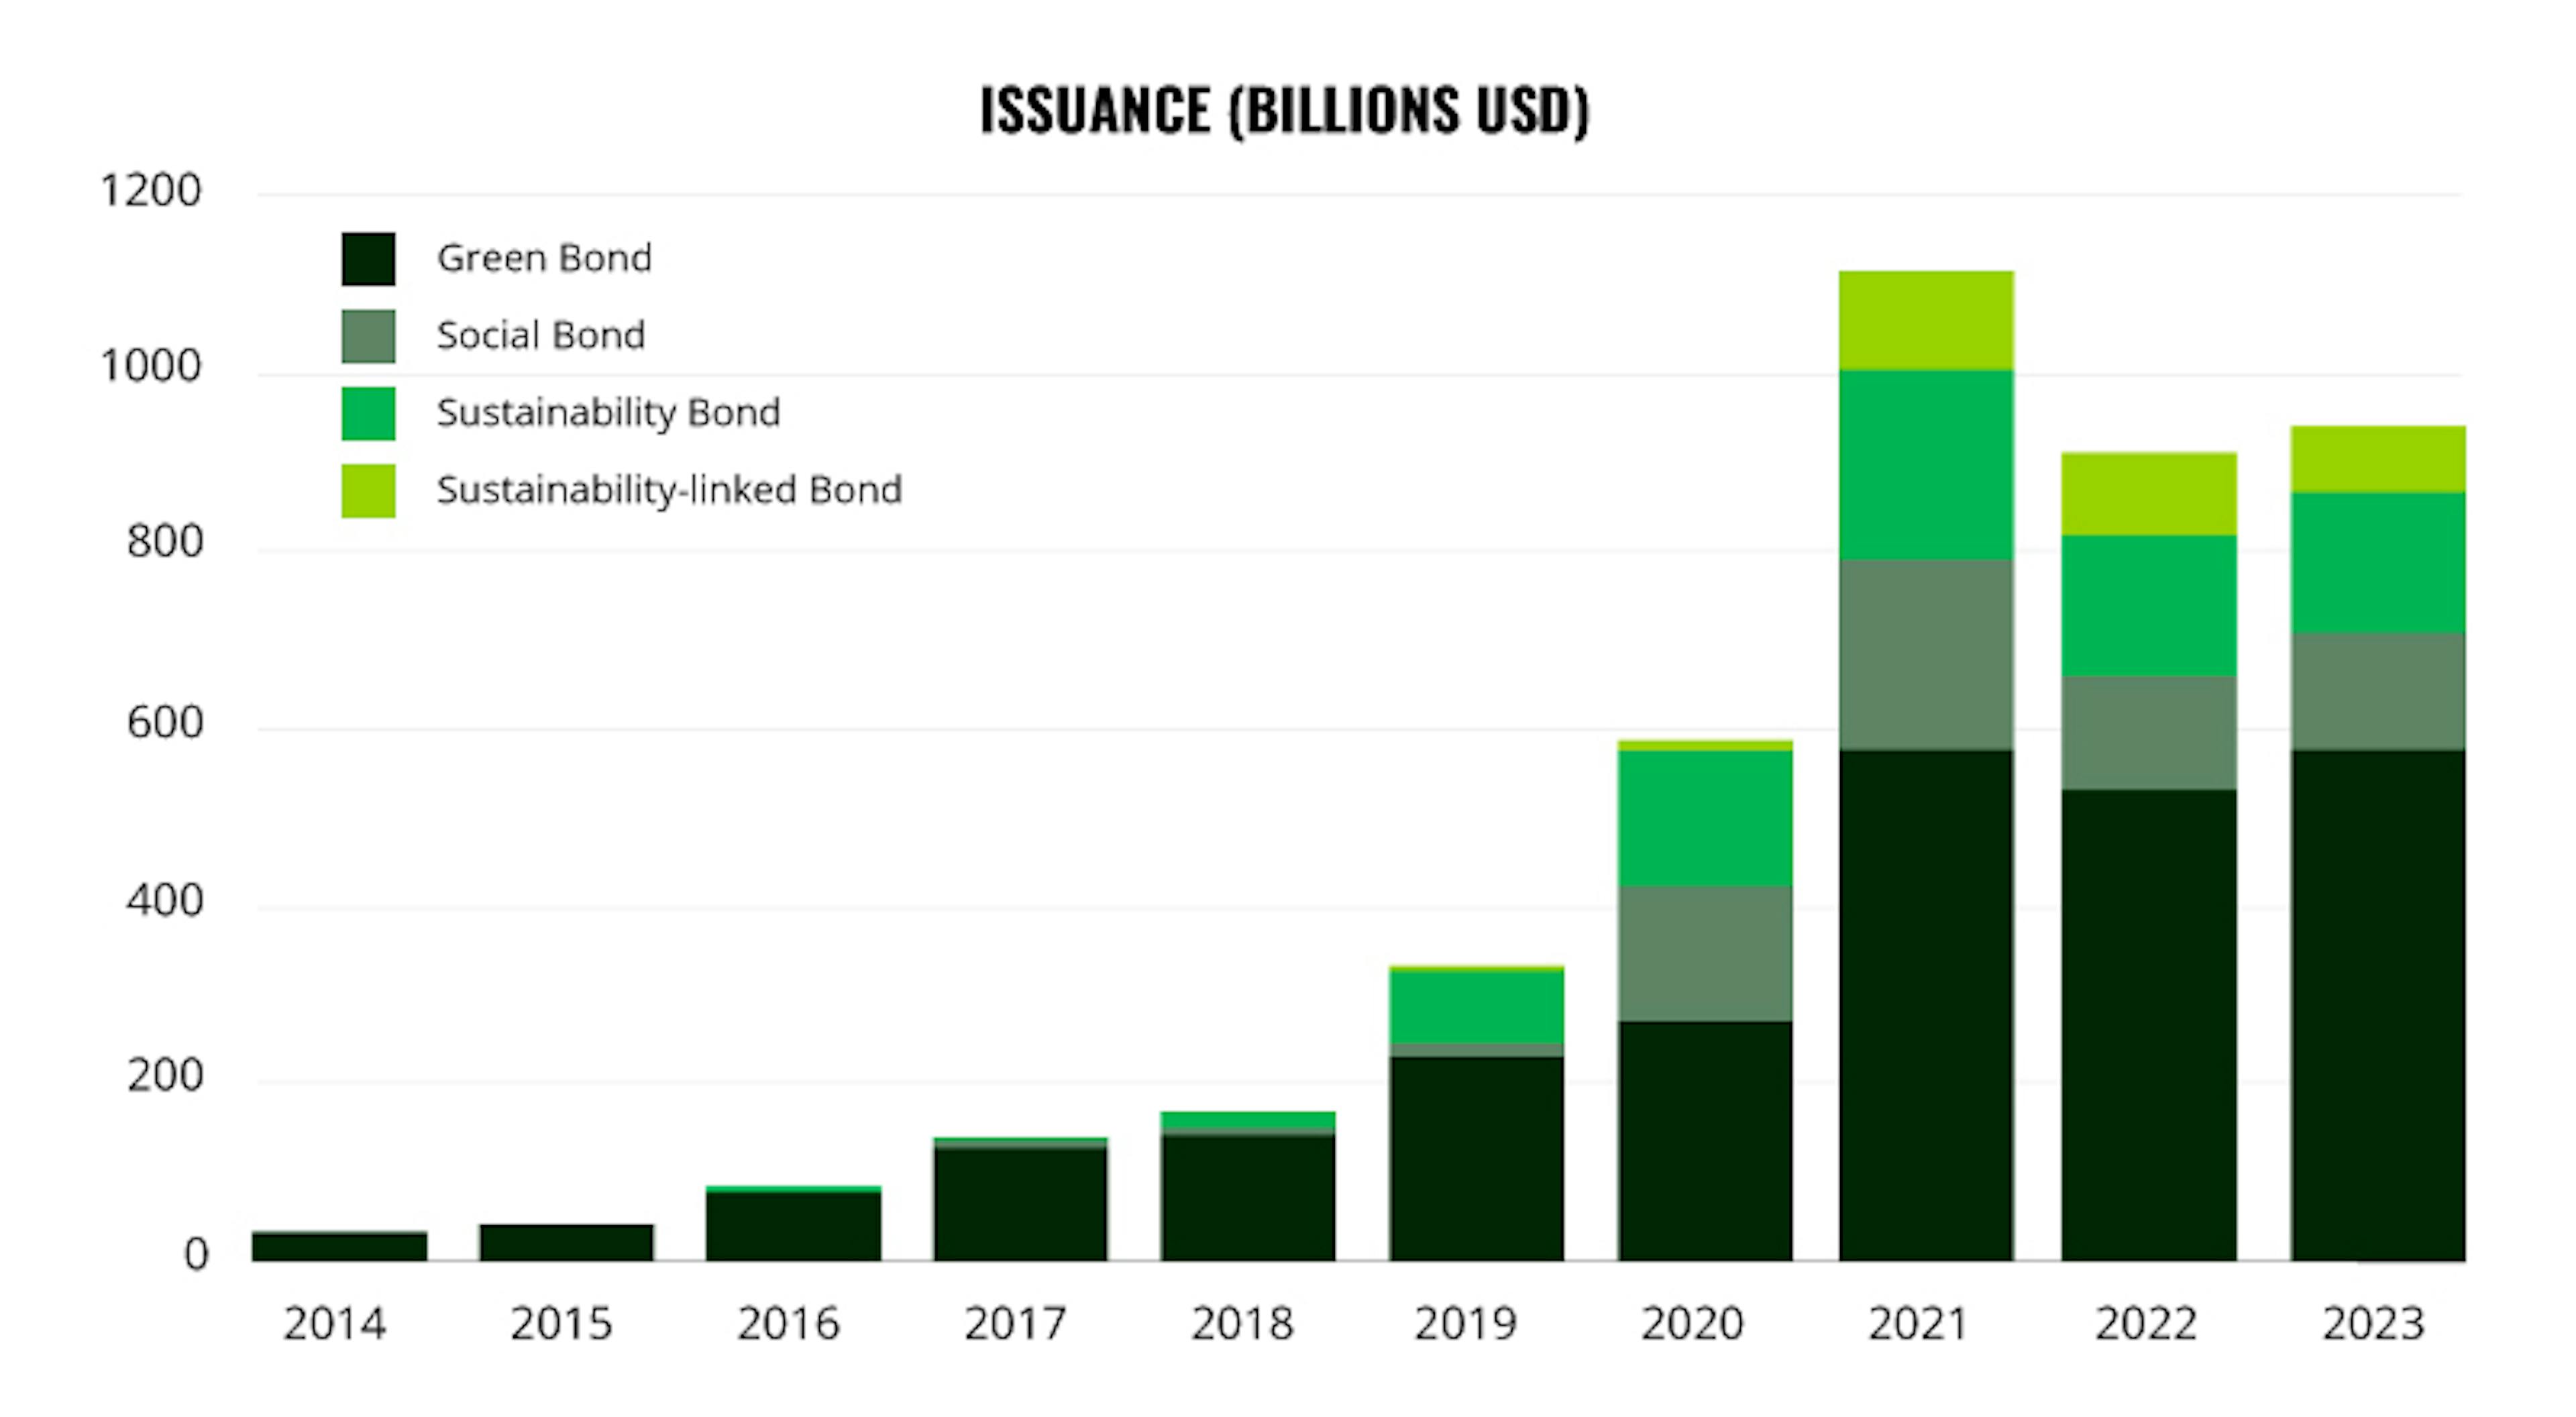
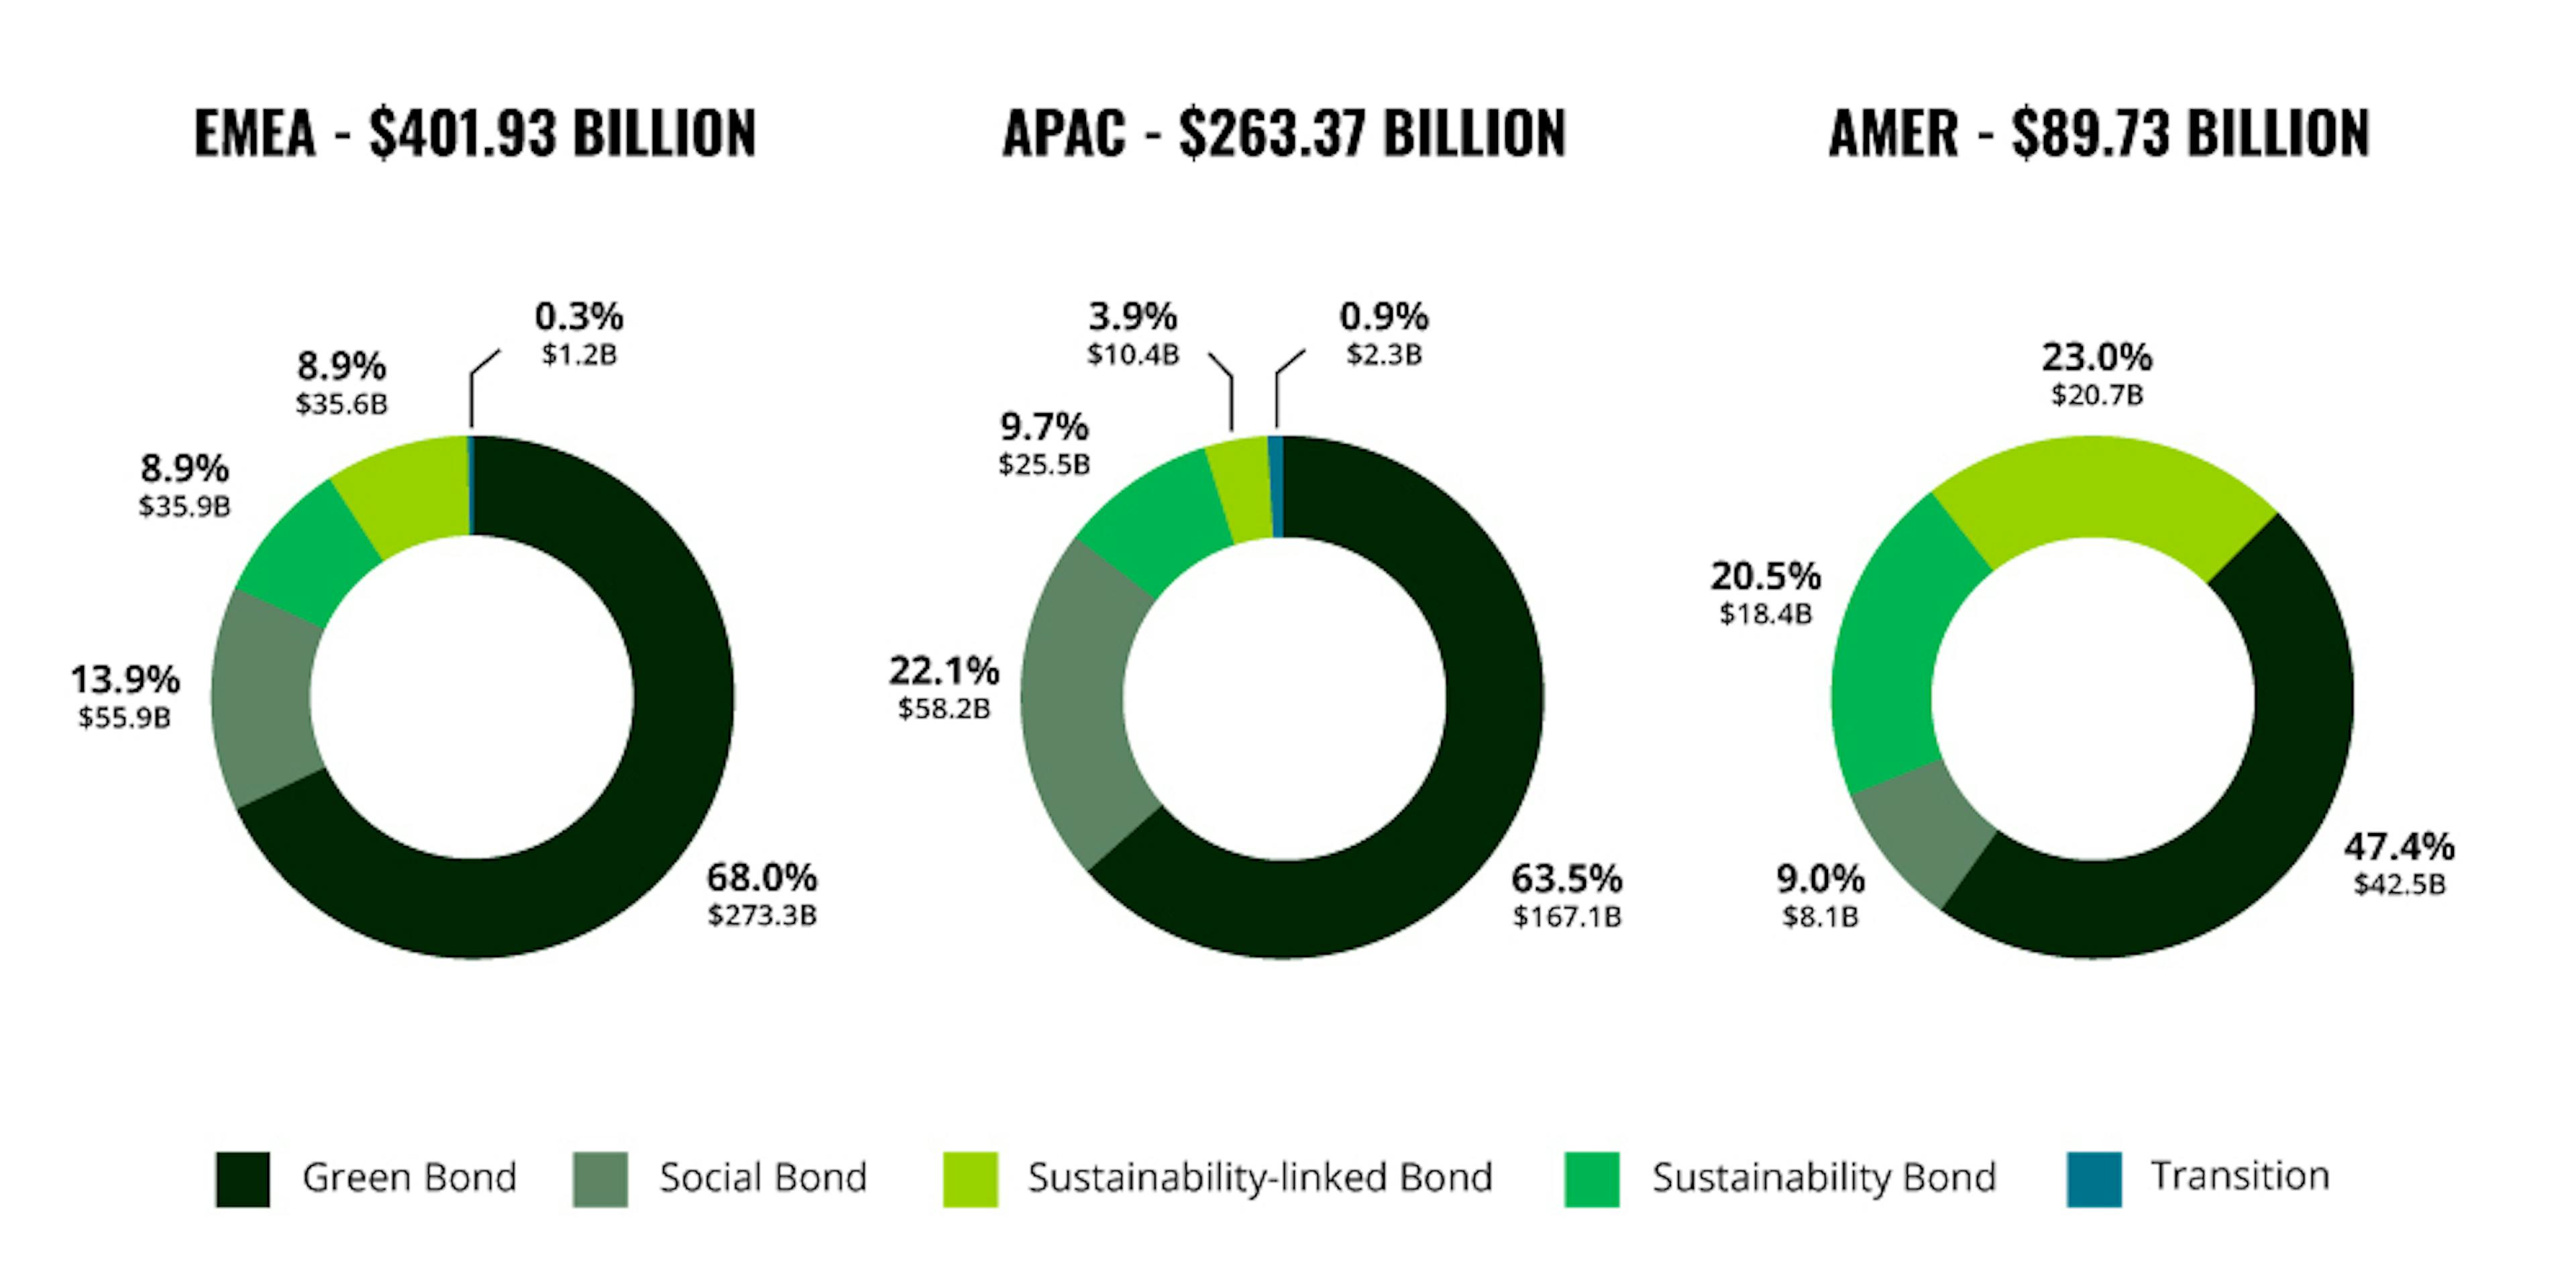
2023 data highlighted a record issuance of use of proceeds green bonds, which dominated issuance in EMEA, APAC and America and a large decrease in issuance volumes of SLBs.
According to Bloomberg, green bond sales from corporates and governments, climbed to USD 575 billion, a step up from 2022, beating 2021’s USD 573 billion figure. SLBs saw the largest decrease in issuance volumes in 2023, down 22% from the previous year, with USD 68 billion.
Issuance of sustainable bonds by region:
Our conviction in sustainable bonds
We believe that the issuance of sustainable bonds will continue in the future, considering the following factors:
There is a growing interest from investors, including Carmignac, who are increasingly incorporating ESG considerations into their investment strategies in response to client demand and in alignment with their own investment strategies;
Regulators are intervening to ensure the re-allocation of capital towards sustainability goals
Issuers continue to seek to demonstrate their commitment to sustainability considerations in their strategies, driven by regulators, investors, and other stakeholders.
While we see the development of sustainable bonds as a positive development, we must also recognise the imperfections of these thematic debt instruments. The market of sustainable bonds remains partly unregulated (except for green bonds taking into account the recent developments around the European Union Green Bond Standard or “EU GBS”) and therefore it is important that investors exercise sufficient diligence to ensure that the sustainability credentials of the instrument they invest in meets their expectations.