
Carmignac P. EM Debt: Letter from the Fund Managers
Carmignac P. EM Debt lost -1.88% in the third quarter of 2023, while its reference indicator1 was down -0.94%.
Market environment
The third quarter of 2023 has been characterized by higher global rates and a volatile environment. Indeed, despite the potential last rate hike from the European Central Bank (ECB) and a pause from the Federal Reserve (Fed), the hawkish speeches from central bankers pushed the 10-year Treasury from around 3.84% to over 4.57%, and the German 10-year from around 2.39% to over 2.84%, reaching the highest levels of the year. Indeed, energy, which was one of the main sources of disinflation, is therefore set to become a positive contributor to price rises again by the end of the year, following the decision by the OPEP (mainly driven by Russia and Saudi Arabia) to extend their production cuts. This will penalize household purchasing power, but will also slow inflation's return to the central banks' targets.
Germany and US 10-year rates evolution

Sources: Carmignac, Bloomberg, 30/09/2023
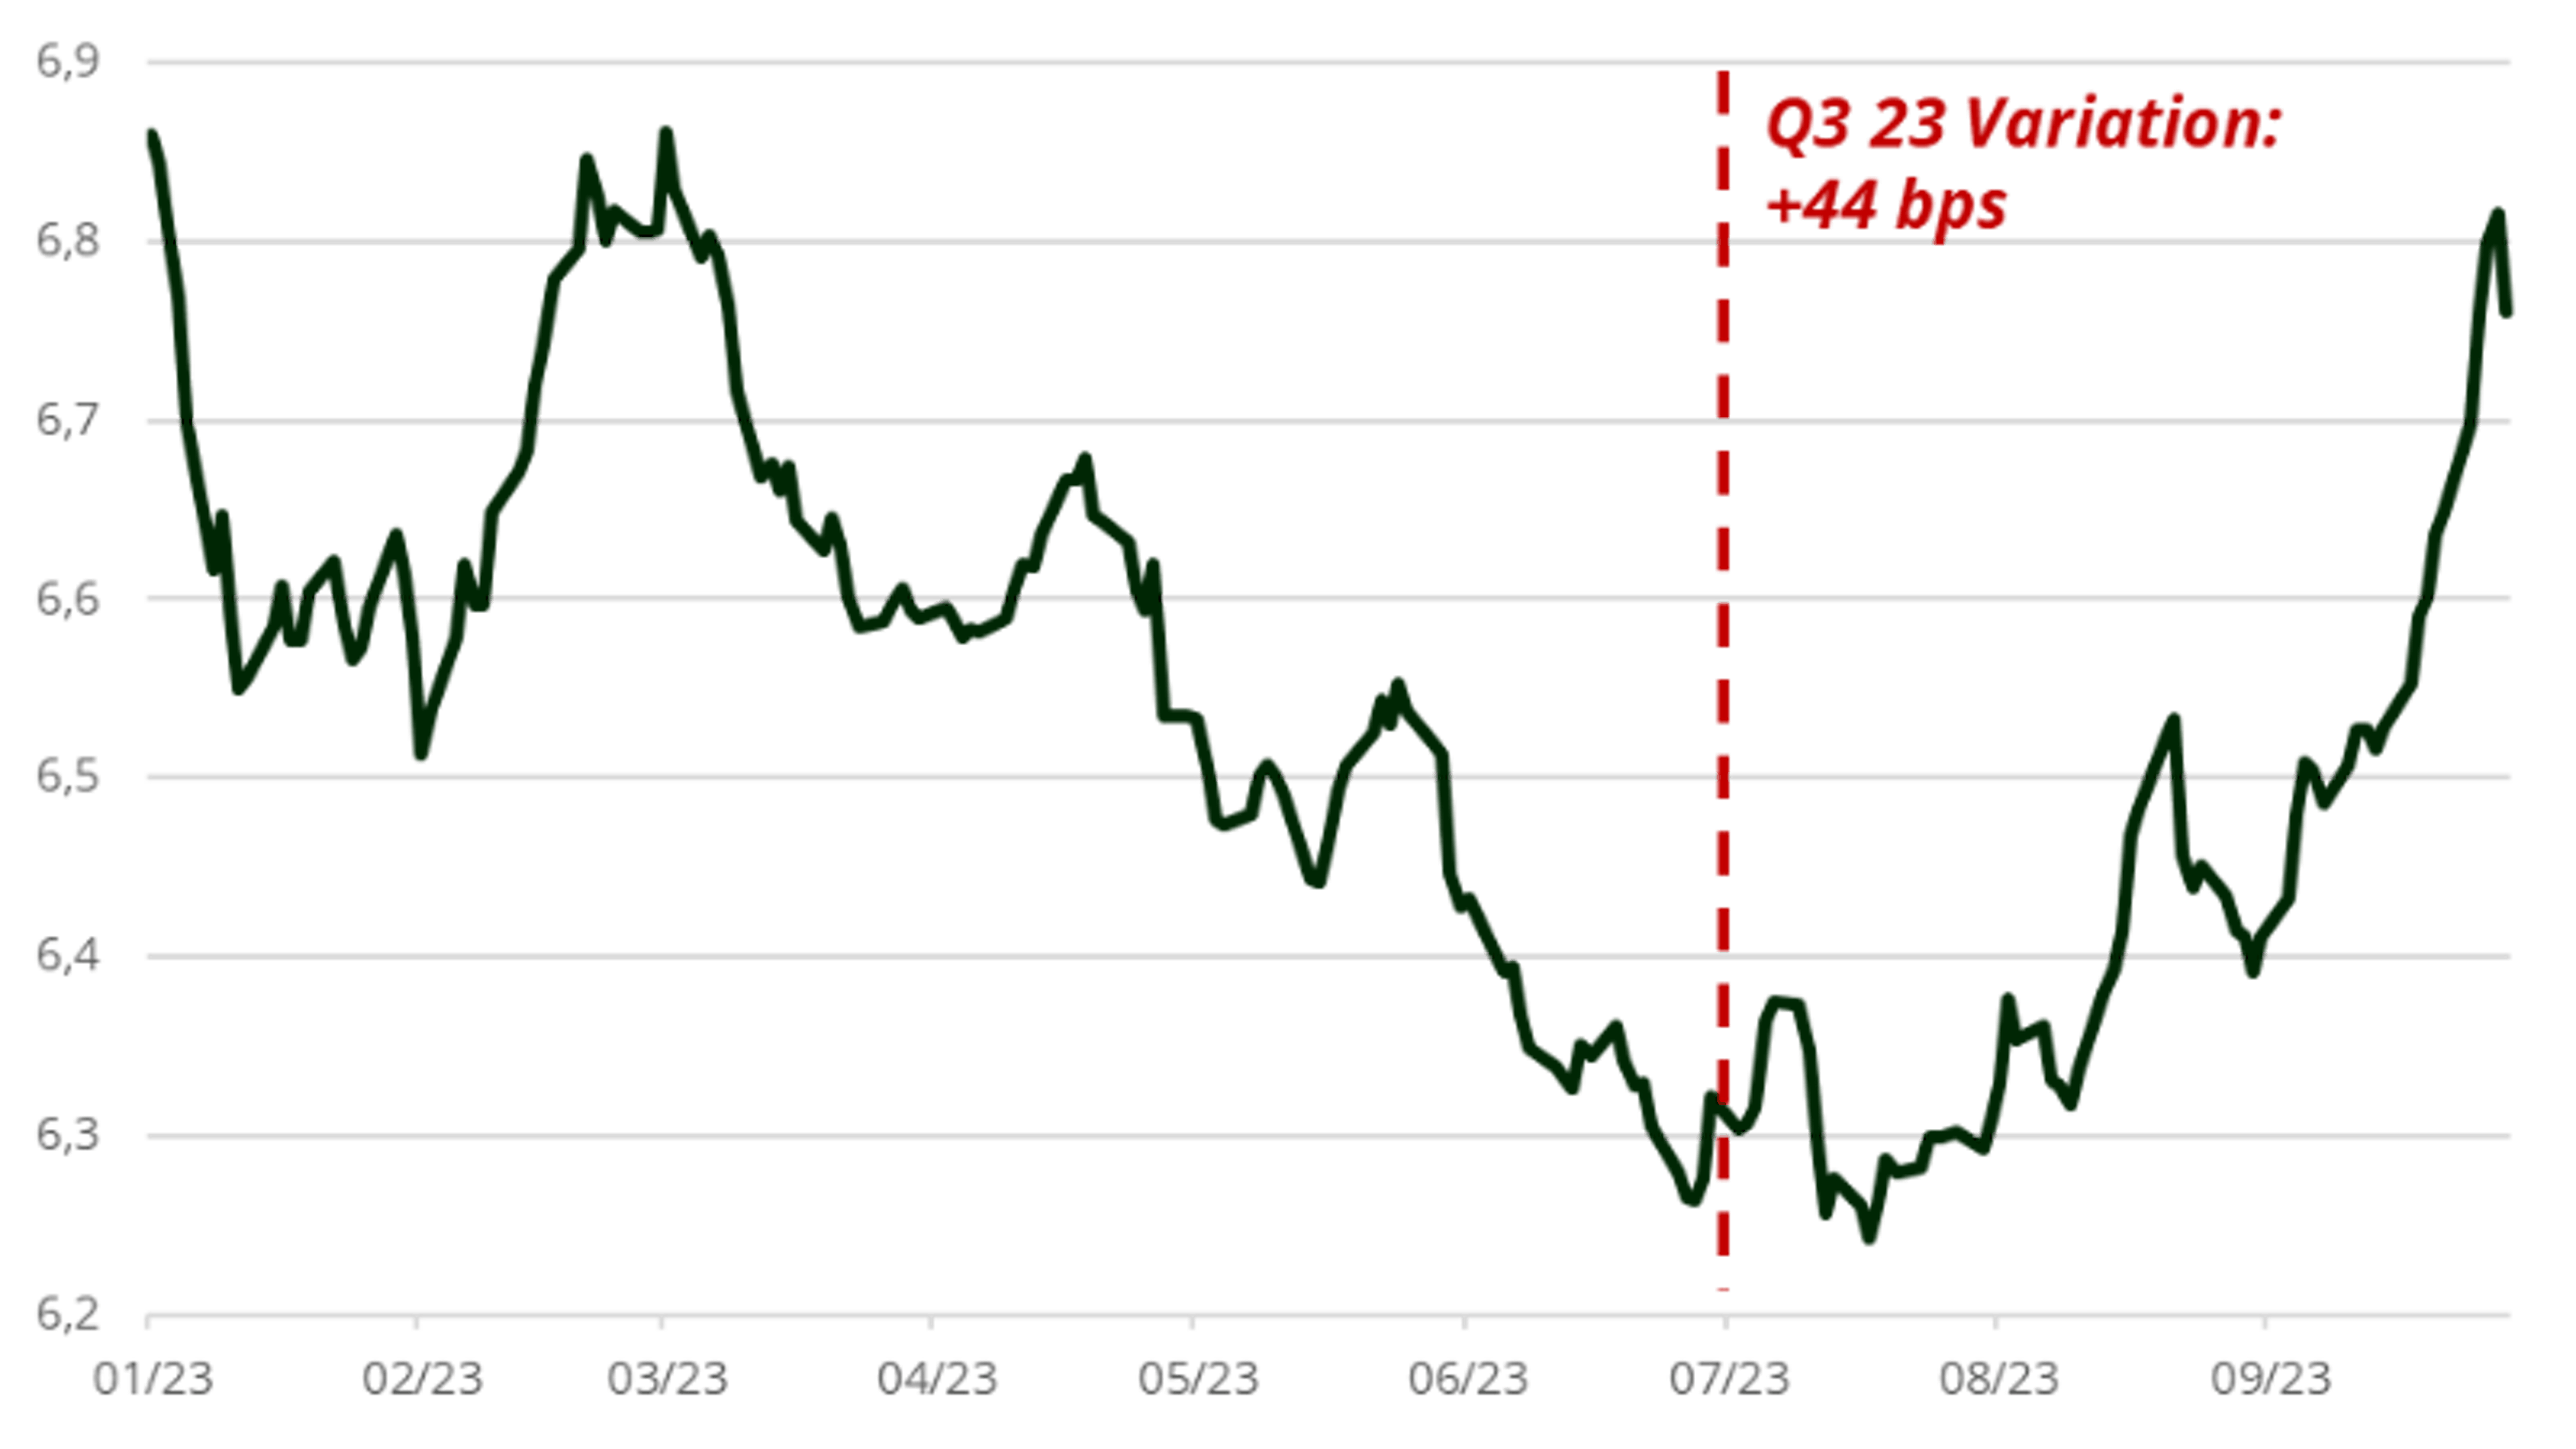
In terms of local rates, we continue to see rate cuts in the emerging market (EM) universe this quarter with notably Poland cutting by 75 basis points from 6.75% to 6%, surprising the market. The majority of Latin American countries have already begun to lower their rates, but they are doing so cautiously, as they are no longer in line with the Fed's policy of "higher rates for a longer period". In China, the disappointing reopening continues to linger. The country is faced with a more difficult international environment due to the desire of many nations to regain industrial sovereignty and the United States to hinder Chinese development. Investors grew more pessimistic about the country’s economic outlook.
GBI-EM Index (Local sovereign debt index) - Yield Evolution
Sources: Carmignac, Bloomberg, 30/09/2023
Furthermore on FX, EM currencies continued to attract investors. Commodity exporter currencies and high carry currencies like those in Latin America remained appealing. Nevertheless, a selective approach is still required, keeping an eye out for balance of payments and inflation trajectories. As an example, the CLP has experienced a decline for three consecutive months due to the challenges encountered by the Banco Central de Chile in maintaining stable interest rates, particularly in light of the rapid decline in inflation within the Chilean economy.
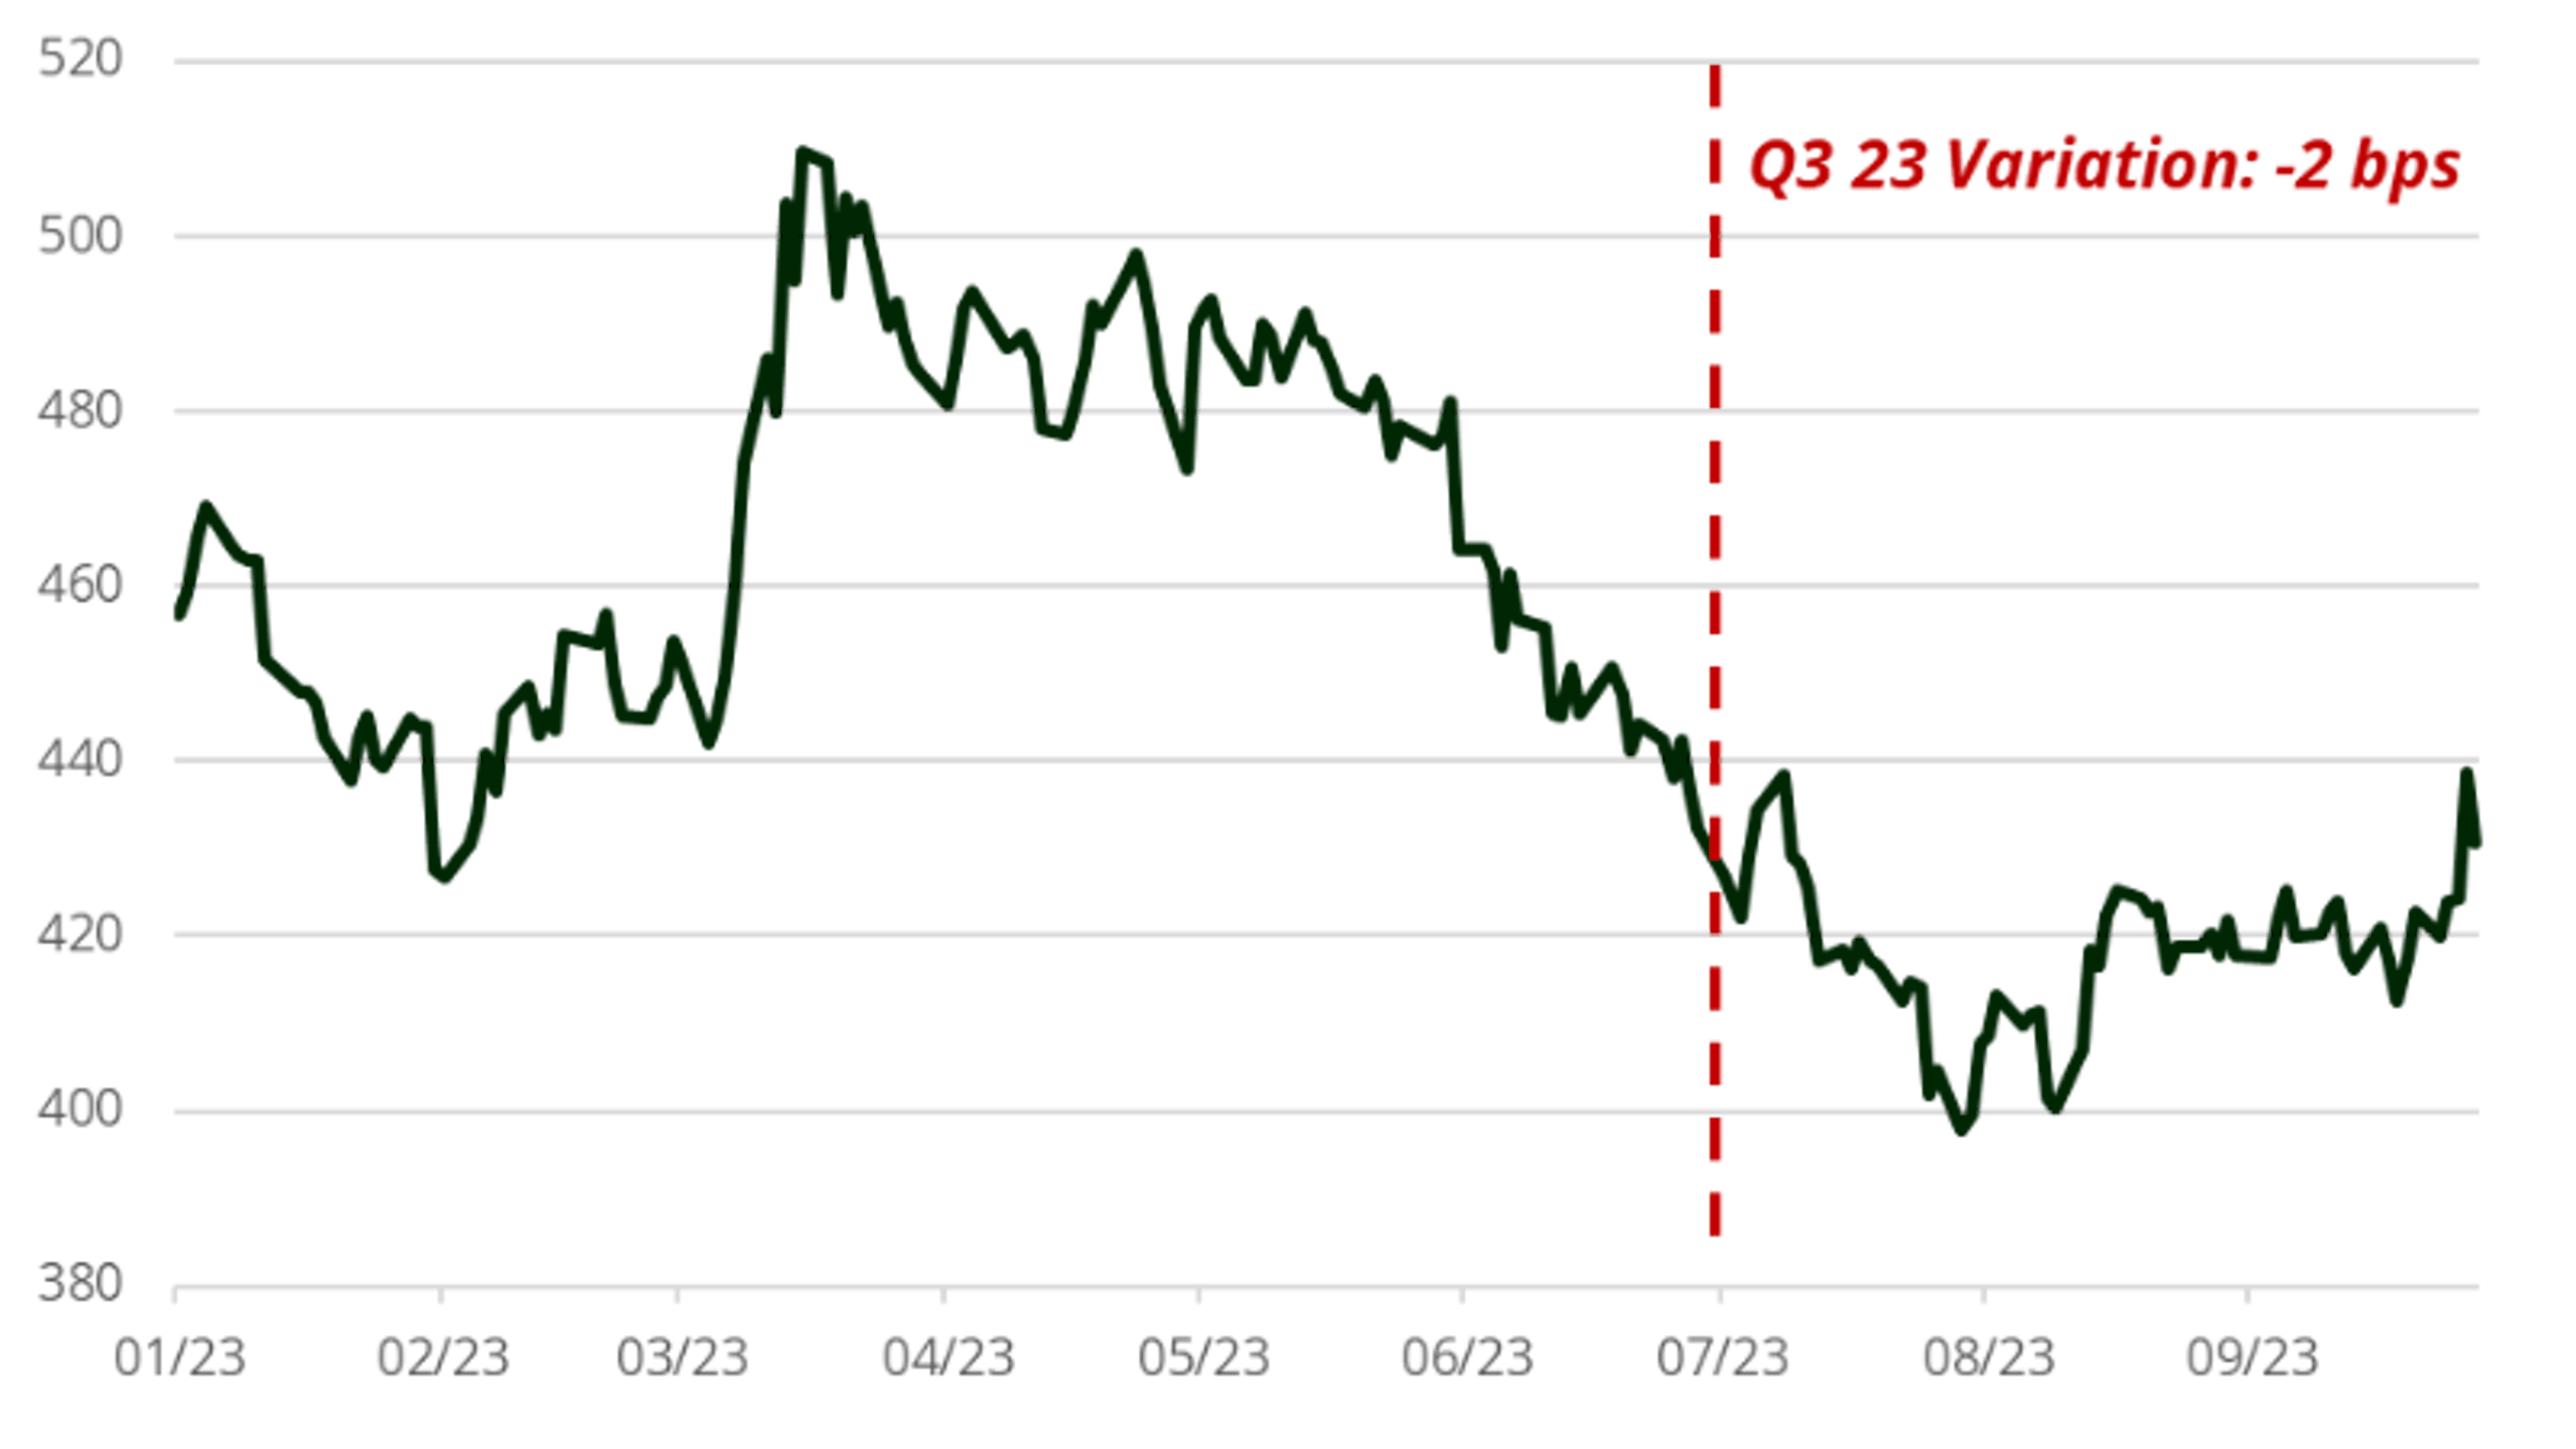
On sovereign credit, spreads remained stable over the period. Spreads were very tight in both the IG and HY spaces (distress names excluded) and the market kept a close eye on special situations such as in African countries. The sweet spot of this area remains in the BBs in which you can find the most attractive risk/reward opportunities.
J.P Morgan EMBIG diversified hedged EURO index (External sovereign debt index) - Spread
Sources: Carmignac, Bloomberg, 30/09/2023
What have we done in this context?
In this context we have mainly been impacted by our exposure to Local Rates in CZK, HUF, COP, MXN and CLP curves. The rise in US interest rates and the dollar, combined with the Chinese slowdown and rising inflation, have prompted us to reduce the risk in the portfolio. We notably reduced our exposure to the EMEA region, where valuations are not attractive as they were.
In the FX space we continue to enjoy the carry of EM FX currencies over the quarter. Nevertheless, on a risk management basis, we reduced our exposure to EM currencies and we continue to be selective and active in this segment. As an example, during the quarter we notably reduced our CZK exposure, which is directly impacted by oil imports. Following volatility peaks and increased in DM rates, we also increased our EUR exposure over the quarter.
On sovereign credit, we benefited from our exposure to the EMEA region, in particular through Romania. Lastly, over the period we increased on a tactical basis our exposure to Colombia as the country should benefit from the current trend on oil.
Outlook for the next months
Our view of recession and high rates is reflected in our portfolio construction, namely a large reduction of risky assets and a high level of CDS protections. We remain focused on duration with the view that a recession would force DM central banks to cut rates and thus enable further cuts in the EM world.
In Local Rates, we are closely monitoring EM Central banks to pursue their cutting cycles as the FED and ECB seem to have paused. We are ready to re-engage in countries which were among the most advanced in their rate hike cycle and in commodity exporters such as Colombia.
In Sovereign Credit, we continue to favour manufacturing countries that will benefit in the long term from the “nearshoring” phenomenon, i.e. the potential repatriation of production chains to closer and more stable countries (Romania, Poland, Mexico, etc.). Nevertheless, we remain cautious with protection against our HY names and will keep our positioning light and focused on the IG space.
Lastly, although we have reduced our global exposure to EM FX, we continue to favour a selection of currencies on a tactical/opportunist basis mainly in LATAM such as the Brazilian real and the Mexican peso.
Carmignac Portfolio EM Debt
Carmignac Portfolio EM Debt FW EUR Acc
- Empfohlene Mindestanlagedauer
- 3 Jahre
- Risikoskala*
- 3/7
- SFDR-Klassifizierung**
- Artikel 8
*Die Definition der Risikoskala finden Sie im KID/BIB (Basisinformationsblatt). Das Risiko 1 ist nicht eine risikolose Investition. Dieser Indikator kann sich im Laufe der Zeit verändern. **Die Offenlegungsverordnung (Sustainable Finance Disclosure Regulation - SFDR) 2019/2088. Die SFDR-Klassifizierung der Fonds kann sich im Laufe der Zeit ändern.
Hauptrisiken des Fonds
Kosten
- Einstiegskosten
- Wir berechnen keine Einstiegsgebühr.
- Ausstiegskosten
- Wir berechnen keine Ausstiegsgebühr für dieses Produkt.
- Verwaltungsgebühren und sonstige Verwaltungs- oder Betriebskosten
- 1,06 % des Werts Ihrer Anlage pro Jahr. Hierbei handelt es sich um eine Schätzung auf der Grundlage der tatsächlichen Kosten des letzten Jahres.
- Erfolgsgebühren
- Für dieses Produkt wird keine erfolgsabhängige Provision berechnet.
- Transaktionskosten
- 0,34 % des Werts Ihrer Anlage pro Jahr. Hierbei handelt es sich um eine Schätzung der Kosten, die anfallen, wenn wir die Basiswerte für das Produkt kaufen oder verkaufen. Der tatsächliche Betrag hängt davon ab, wie viel wir kaufen und verkaufen.
Performance
| Carmignac Portfolio EM Debt | +0,5 | +7,9 | +4,1 | +15,3 | −9,0 | +3,9 | +10,5 | +28,9 | −10,0 | +1,1 |
| Referenzindikator | +2,1 | +8,6 | +4,4 | +8,9 | −5,9 | −1,8 | −5,8 | +15,6 | −1,5 | +0,4 |
| Carmignac Portfolio EM Debt | +6,4 % | +3,9 % | +5,2 % |
| Referenzindikator | +6,3 % | +3,6 % | +2,5 % |
Quelle: Carmignac Stand 30. Okt 2026.
Datum des ersten NAV : 31/07/2017.
Die Wertentwicklung der Vergangenheit ist keine Garantie für die zukünftige Wertentwicklung. Sie verstehen sich nach Abzug von Gebühren (außer eventuellen Ausgabeaufschlägen, die von der Vertriebsstelle erhoben werden).
Bei den nicht währungsgesicherten Anteilen kann die Rendite aufgrund von Währungsschwankungen steigen oder fallen (bei Aktien, die nicht gegen das Währungsrisiko abgesichert sind).
Referenzindikator: 50% JPM GBI-EM Global Diversified Composite index + 50% JPM EMBI Global Diversified Hedged index. Häufigkeit der Neugewichtung: Quartalsweise