
Emerging markets are defined by high dispersion, structural inefficiency and information asymmetry. For active managers, these are features that can be exploited. For passive investors, they are a problem that an index fund cannot solve.
Emerging markets delivered their strongest annual return since 2017 in 2025. The headline figure was impressive but what lay beneath could be more instructive.
Korea surged 97% in US dollar terms, South Africa rose 73%, Mexico gained 50% and Brazil 40%. Meanwhile, Saudi Arabia, Indonesia, Argentina and the Philippines all posted negative returns for the year. The same asset class in the same calendar year, but outcomes separated by more than 100 percentage points1.
That dispersion is not a quirk of 2025 but a common characteristic of emerging markets as an asset class. And it is the most straightforward argument against passive exposure: buying the index means buying all of it, the leaders and the laggards, without the ability to distinguish between them.
What passive emerging market exposure actually gives you
Emerging market indices are constructed by market capitalisation, which means they systematically overweight whatever has already performed well and underweight what has not yet been recognised. By the time a company becomes large enough to warrant meaningful index weight, much of its return has already been captured by those who identified it earlier. In a sense, the passive investor arrives late.
According to Naomi Waistell, co-fund manager of Carmignac Emergents: "Performance benchmarks are really backward looking barometers of performance rather than telling us about how we want to position for the future."
The construction problem runs deeper than timing. Passive strategies in emerging markets include state-owned enterprises whose objectives often diverge from those of minority shareholders, companies with governance ratings at the bottom of the scale and businesses on exclusion lists for weapons manufacturing, coal extraction or regulatory violations.
An index fund cannot screen any of these out but an active manager can and arguably must.
The inability to respond when an investment case changes is equally costly. When Samsung Electronics failed to obtain Nvidia certification for its most advanced memory chips, its competitive position in the high-bandwidth memory market deteriorated materially but an index fund continued to hold the stock at its market-cap weight.
An active manager who identified the shift in competitive dynamics could exit the position and redeploy into SK Hynix, which had the technological lead and Nvidia’s qualification. And when Samsung obtained the certification active managers could then reinitiate a position in the stock. That was a real-life example that drove some of Carmignac Emergents’ recent outperformance.
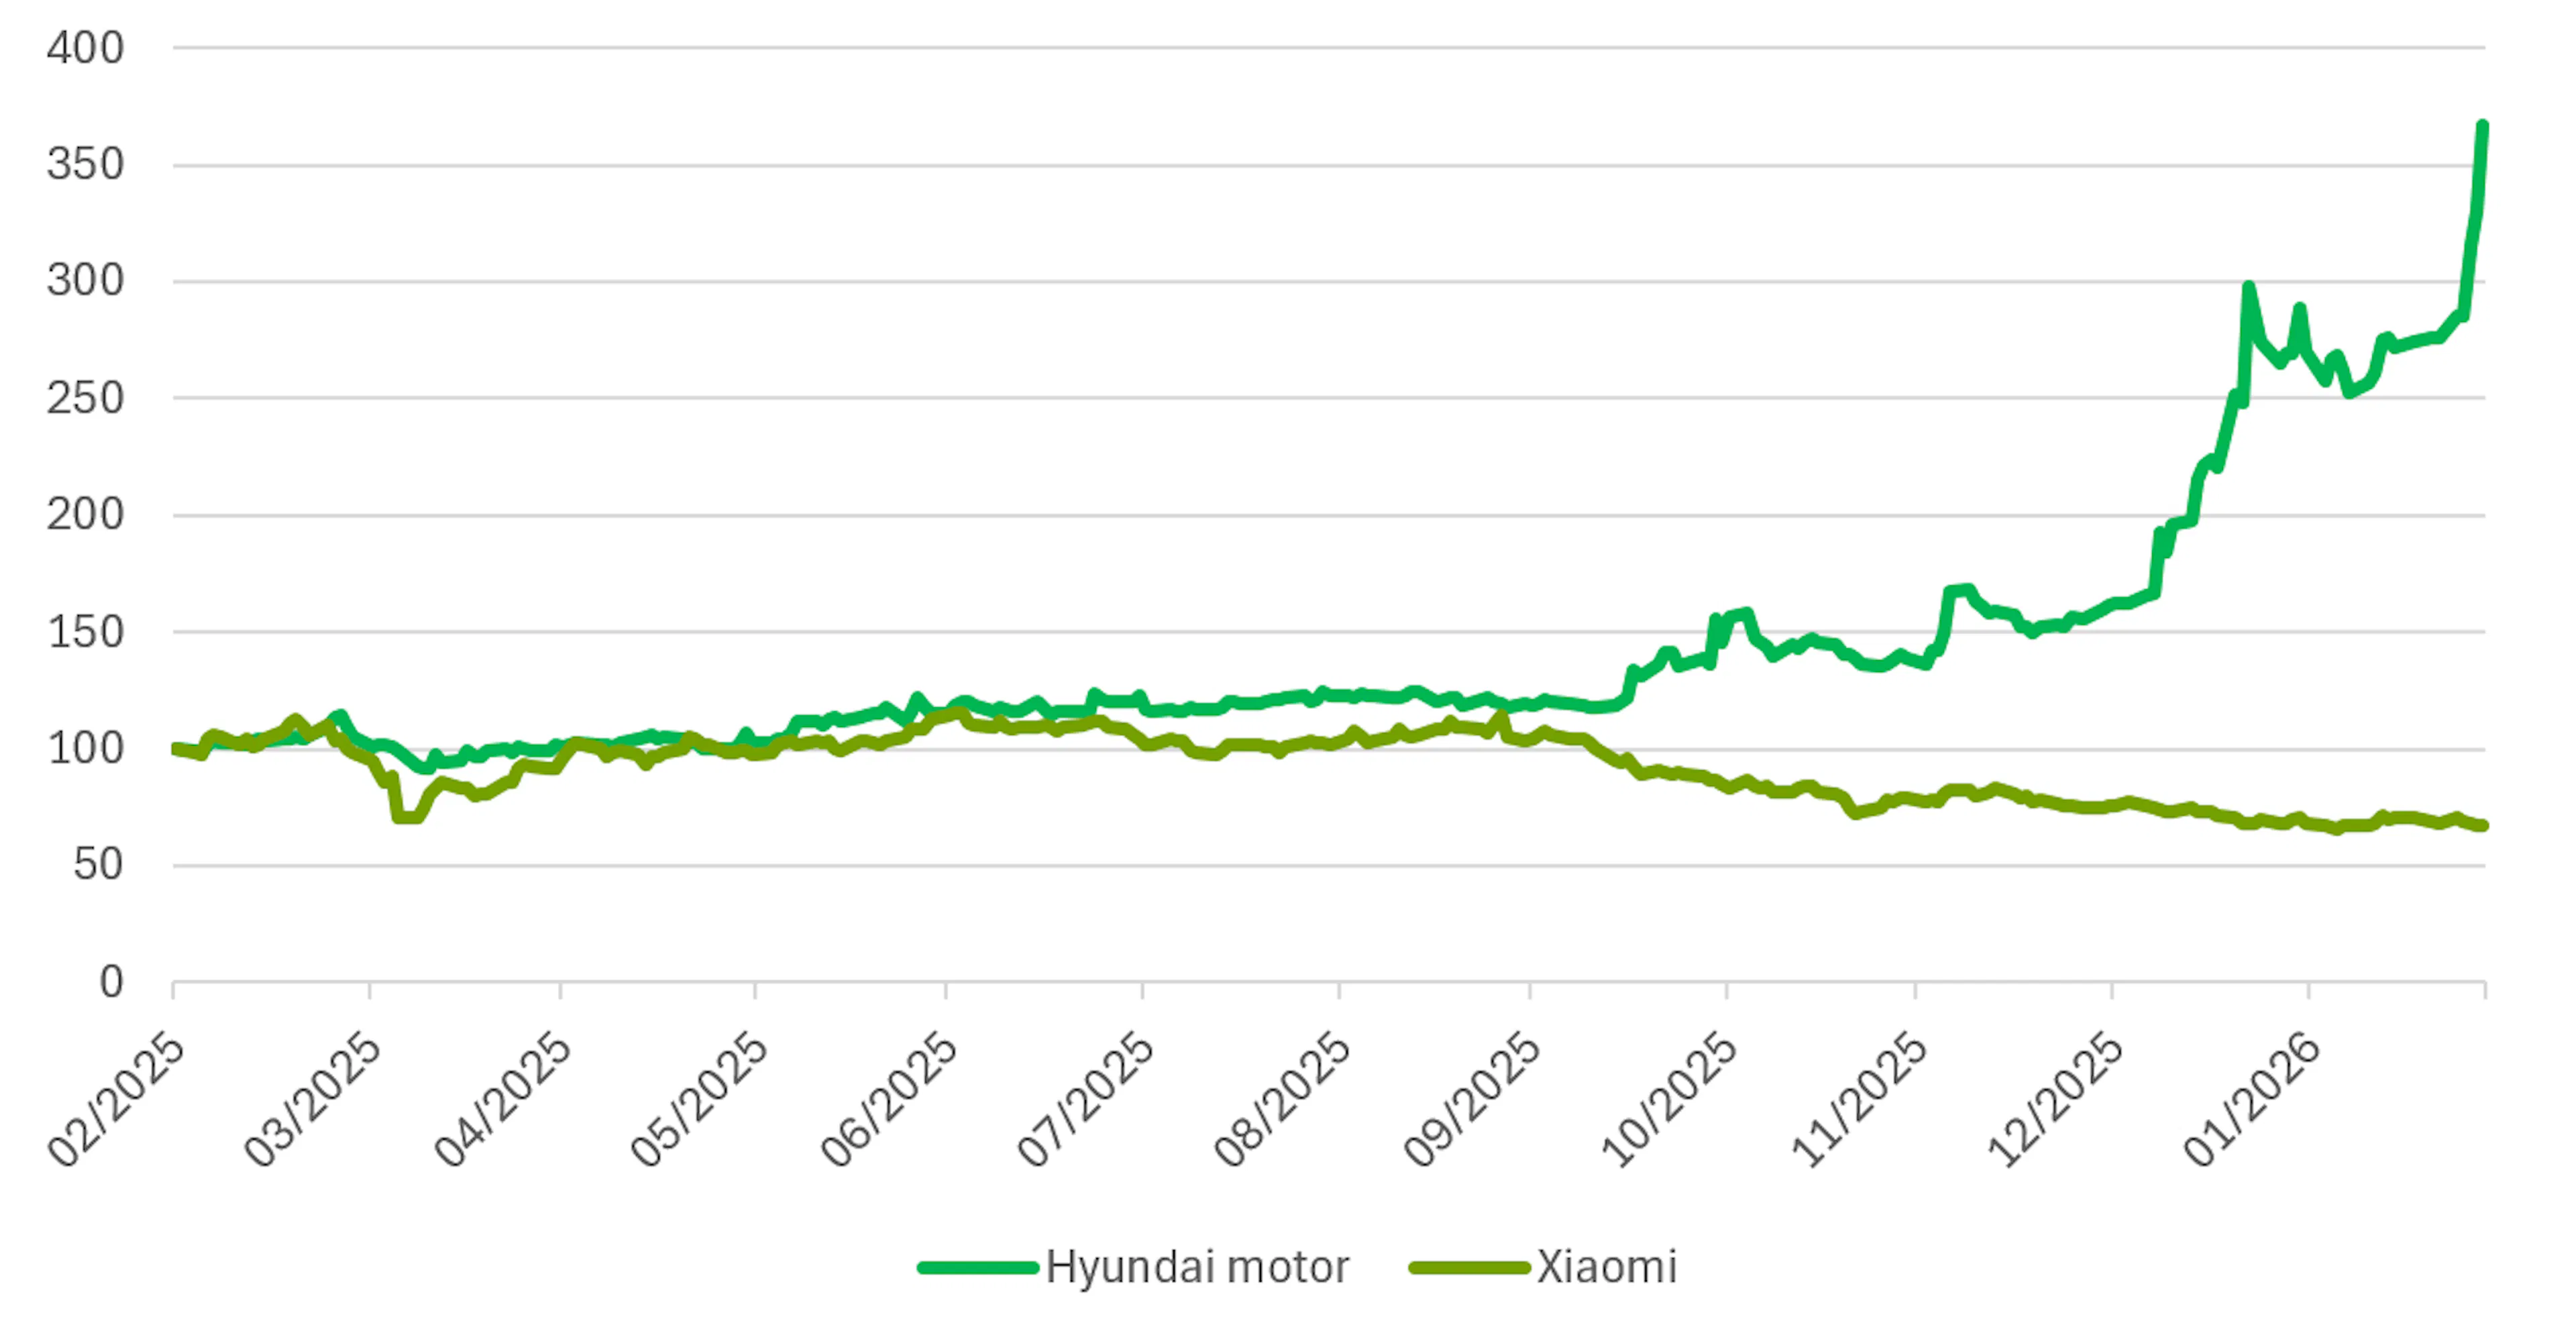
A similar dynamic can be observed in the automotive sector. In emerging market indices, Xiaomi has rapidly become one of the largest auto-related weights following the market’s enthusiasm around its entry into electric vehicles. From a passive perspective, its growing market capitalisation automatically translates into a higher index allocation.
However, an active approach leads to a different conclusion. Rather than following index weights, we prefer companies where fundamentals and long-term competitive advantages appear stronger. In this case, we favour Hyundai. Beyond its established automotive business, Hyundai is investing heavily in robotics through its participation in Boston Dynamics, a technological capability that we believe could meaningfully enhance productivity and strengthen its competitive positioning over time.
The performance divergence illustrates the value of this approach. Over the rolling twelve months to the end of February 2026, Hyundai — which we hold in the portfolio — delivered a return of +267%, while Xiaomi declined by -33% over the same period.
This type of dispersion highlights why fundamental research and active decision-making matter in emerging markets: the largest weight in the index is not necessarily the most compelling investment opportunity.
Why emerging markets specifically reward active management
The conditions that make passive strategies attractive in developed markets, namely high liquidity, standardised disclosure, efficient price discovery and relatively uniform governance, are substantially less prevalent in emerging markets. Information asymmetry is higher, financial statements are sometimes non-standardised and local dynamics require on-the-ground knowledge that cannot be derived from a screen.
Waistell describes these conditions not as obstacles but as sources of opportunity: "Emerging markets are volatile by nature. They always have been. And sometimes we can actually use that volatility, the extra inefficiencies in emerging markets to our advantage when we're investing."
Carmignac Emergents co-fund manager Xavier Hovasse added: "In emerging markets, there's a lot of volatility and sometimes stocks go up way too much. So, we take that opportunity to trim or they go down way too much, which is an opportunity to buy more at a very good price."
The cost of getting country and sector allocation wrong in emerging markets is also substantially higher than in developed markets, where broad economic trends tend to lift all boats to a similar degree. In emerging markets, country selection alone can swing returns by a substantial margin, as 2025 demonstrated.
Hovasse, who is Carmignac’s Head of Emerging Equities, said: "When you invest in emerging markets, both top down and bottom up are very important. In terms of the chronology, you start with the top-down thinking. You need to find the best countries, the best sectors, the best businesses, and only after that you need to try to find the best vehicles to play that."
The shift from beta to alpha
The 2025 emerging market equity rally was primarily beta-driven. As macro conditions improved and investor sentiment turned positive, price/earnings multiples expanded across the asset class. Broad exposure worked because everything was rising.
The next phase could be different. With emerging markets now trading at around 12.5x forward 2026 earnings, elevated relative to recent history, further multiple expansion is less certain. Emerging market equities are forecast to deliver mid-to-high-teens EPS growth in 2026 and returns from here are more likely to be determined by which companies actually deliver the expected earnings than by a broad re-rating of the asset class2.
Waistell elaborated: "A weaker US dollar, historically high real rates and stable inflation provide EM central banks with room to gradually ease monetary policy, creating meaningful tailwinds. However, we are entering a phase of rising dispersion, where returns are likely to be driven more by earnings growth than multiple expansion, making selectivity more important than index exposure."
How Carmignac approaches the opportunity
Carmignac Emergents is a direct counterpoint to passive exposure. The portfolio holds 35-45 stocks, selected through a combination of top-down country and sector analysis and rigorous bottom-up stock picking. Active share stood at 80% as of end-March 2026, meaning the portfolio is substantially different from the reference indicator it is measured against.
The fund managers also work closely with a dedicated Front Office Risk Management team to better understand the portfolio’s sensitivity to different market variables, for example by assessing its sensitivity to oil prices, US real rates and to a value vs growth bias. Understanding these underlying sensitivity and bases of the fund enables the fund managers to make more informed investment decisions and adjust the portfolio if needed and illustrates the value added by active management compared with passive strategies.
Sustainability is integrated as an investment discipline rather than a constraint. As Waistell explained: "We think that sustainability is actually value accretive and alpha seeking in its own right. We're just putting more information, more fundamental analysis into stock prices upfront."
Since the fund's launch in February 1997, it has returned 893%3 against a reference indicator return of 285%4, net of fees as at the end of March 2026.
Waistell concludes: “The other thing that's key is to have a clear process and follow that process through the long term. That avoids being buffeted by some of the short-term factors. Yes, we can be agile if we need to and make bold decisions when that's called for, but ultimately what we're trying to do is drive the best risk-adjusted returns.”
1Source: Bloomberg, MSCI, 31/12/2025.
2Sources: Carmignac, CLSA Research, Bloomberg, 12/01/2026.
3Performance of Carmignac Emergents A EUR Acc.
4Reference Indicator: MSCI EM NR index.

Carmignac Emergents
Carmignac Emergents A EUR Acc
- Aanbevolen minimale beleggingstermijn*
- 5 jaar
- Risicoschaal**
- 4/7
- SFDR-fondscategorieën***
- Artikel 9
*Aanbevolen minimale beleggingstermijn: Dit deelnemingsrecht/deze klasse is mogelijk niet geschikt voor beleggers die voornemens zijn hun inleg voor afloop van de aanbevolen termijn op te nemen. Deze verwijzing naar een beleggersprofiel is geen beleggingsadvies. Welk bedrag redelijkerwijs in een ICBE kan worden belegd hangt af van uw persoonlijke situatie en moet worden bekeken in relatie tot uw totale portefeuille. **Het profiel kan variëren van 1 tot 7, waarbij categorie 1 overeenkomt met een lager risico en een lager potentieel rendement, en categorie 7 met een hoger risico en een hoger potentieel rendement. De categorieën 4, 5, 6 en 7 impliceren een hoge tot zeer hoge volatiliteit, met grote tot zeer grote prijsschommelingen die op korte termijn tot latente verliezen kunnen leiden. ***De Sustainable Finance Disclosure Regulation (SFDR) 2019/2088. De SFDR-classificatie van de fondsen kan in de loop van de tijd veranderen.
Voornaamste risico's van het Fonds
Kosten
- Instapkosten
- 4,00 % van het bedrag dat u betaalt wanneer u in deze belegging instapt. Dit is het hoogste bedrag dat u in rekening zal worden gebracht. Carmignac Gestion brengt geen instapkosten in rekening. De persoon die verantwoordelijk is voor de verkoop van het product zal u informeren over de feitelijke kosten.
- Uitstapkosten
- Wij brengen voor dit product geen uitstapkosten in rekening.
- Beheerskosten en andere administratie - of exploitatiekos ten
- 1,80 % van de waarde van uw belegging per jaar. Dit is een schatting op basis van de feitelijke kosten over het afgelopen jaar.
- Prestatievergoedingen
- 20,00 % max. van de meerprestatie als het rendement sinds het begin van het boekjaar hoger is dan dat van de referentie-indicator en er geen minderprestatie uit het verleden meer moet worden goedgemaakt. Het feitelijke bedrag zal variëren naargelang van de prestaties van uw belegging. De schatting van de totale kosten hierboven omvat het gemiddelde over de afgelopen vijf jaar, of sinds de introductie van het product als dat minder dan vijf jaar geleden is.
- Transactiekosten
- 0,35 % van de waarde van uw belegging per jaar. Dit is een schatting van de kosten die ontstaan wanneer we de onderliggende beleggingen voor het product kopen en verkopen. Het feitelijke bedrag zal variëren naargelang hoeveel we kopen en verkopen.
- Roerende voorheffing
- Belasting van dividend en rente op jaarbasis (via de simulator)
- Roerende voorheffing bij verkoop
- ─
- Taks op beursverrichtingen (TOB)
- ─
- Conversiekosten
- 0%
Rendement
| Carmignac Emergents | +2,1 | +23,1 | +4,6 | +9,5 | −15,6 | −10,7 | +44,7 | +24,7 | −18,6 | +18,8 |
| Referentie-indicator | +1,8 | +17,8 | +14,7 | +6,1 | −14,9 | +4,9 | +8,5 | +20,6 | −10,3 | +20,6 |
| Carmignac Emergents | +11,1 % | +1,1 % | +6,9 % |
| Referentie-indicator | +12,6 % | +4,1 % | +7,7 % |
Bron: Carmignac op 31 mrt. 2026.
Het beheer van dit deelnemingsrecht/deze klasse is niet gebaseerd op de indicator. In het verleden behaalde resultaten en waarden bieden geen garantie voor toekomstige resultaten en waarden. De vermelde rendementen zijn netto na aftrek van alle kosten, met uitzondering van eventuele in- en uitstapkosten, en worden verkregen na aftrek van kosten en belastingen die van toepassing zijn op een gemiddelde detailhandelsklant die als natuurlijke persoon woonachtig is in België. Wanneer de valuta afwijkt van uw eigen valuta, bestaat er een valutarisico dat kan resulteren in een waardedaling. De referentievaluta van het fonds/subfonds is de EUR. Het fonds houdt een risico op kapitaalverlies in.
Het rendement kan stijgen of dalen als gevolg van valutaschommelingen voor de aandelen die niet valutadekkend zijn.
Referentie-indicator: MSCI EM NR index