
Carmignac P. EM Debt: Letter from the Fund Managers
indicator’s performance in the 4th quarter of 2023 for JP Morgan GBI – Emerging Markets Global Diversified Composite Unhedged EUR Index.
Carmignac P. EM Debt gained +6.12% in the fourth quarter of 2023, while its reference indicator1 rose by +3.79%. Over 2023, the Fund realized a positive performance of +15.26% versus +8.89% for its reference indicator1.
Market environment
The fourth quarter of 2023 has been characterized by a strong rally of global rates and a volatile environment. Indeed, having completed their rate hikes, both the Federal Reserve (Fed) and the European Central Bank (ECB) are now in a position where they can take a pause and assess the impact of their previous monetary policy tightening. Developed country yields eased sharply over the quarter, with the German Bund falling from 2.84% to 2.02% and the US 10-Year from 4.57% to 3.88%, after hitting the 5% level for the US. Regarding commodities, crude oil prices continued to decline, with Brent and WTI close to $75/b. Doubts about the credibility of OPEC+ production cuts and continued increased supply have contributed to the drop, which helps to allay fears of a spike in oil prices by 2024.
Germany and US 10-year rates evolution
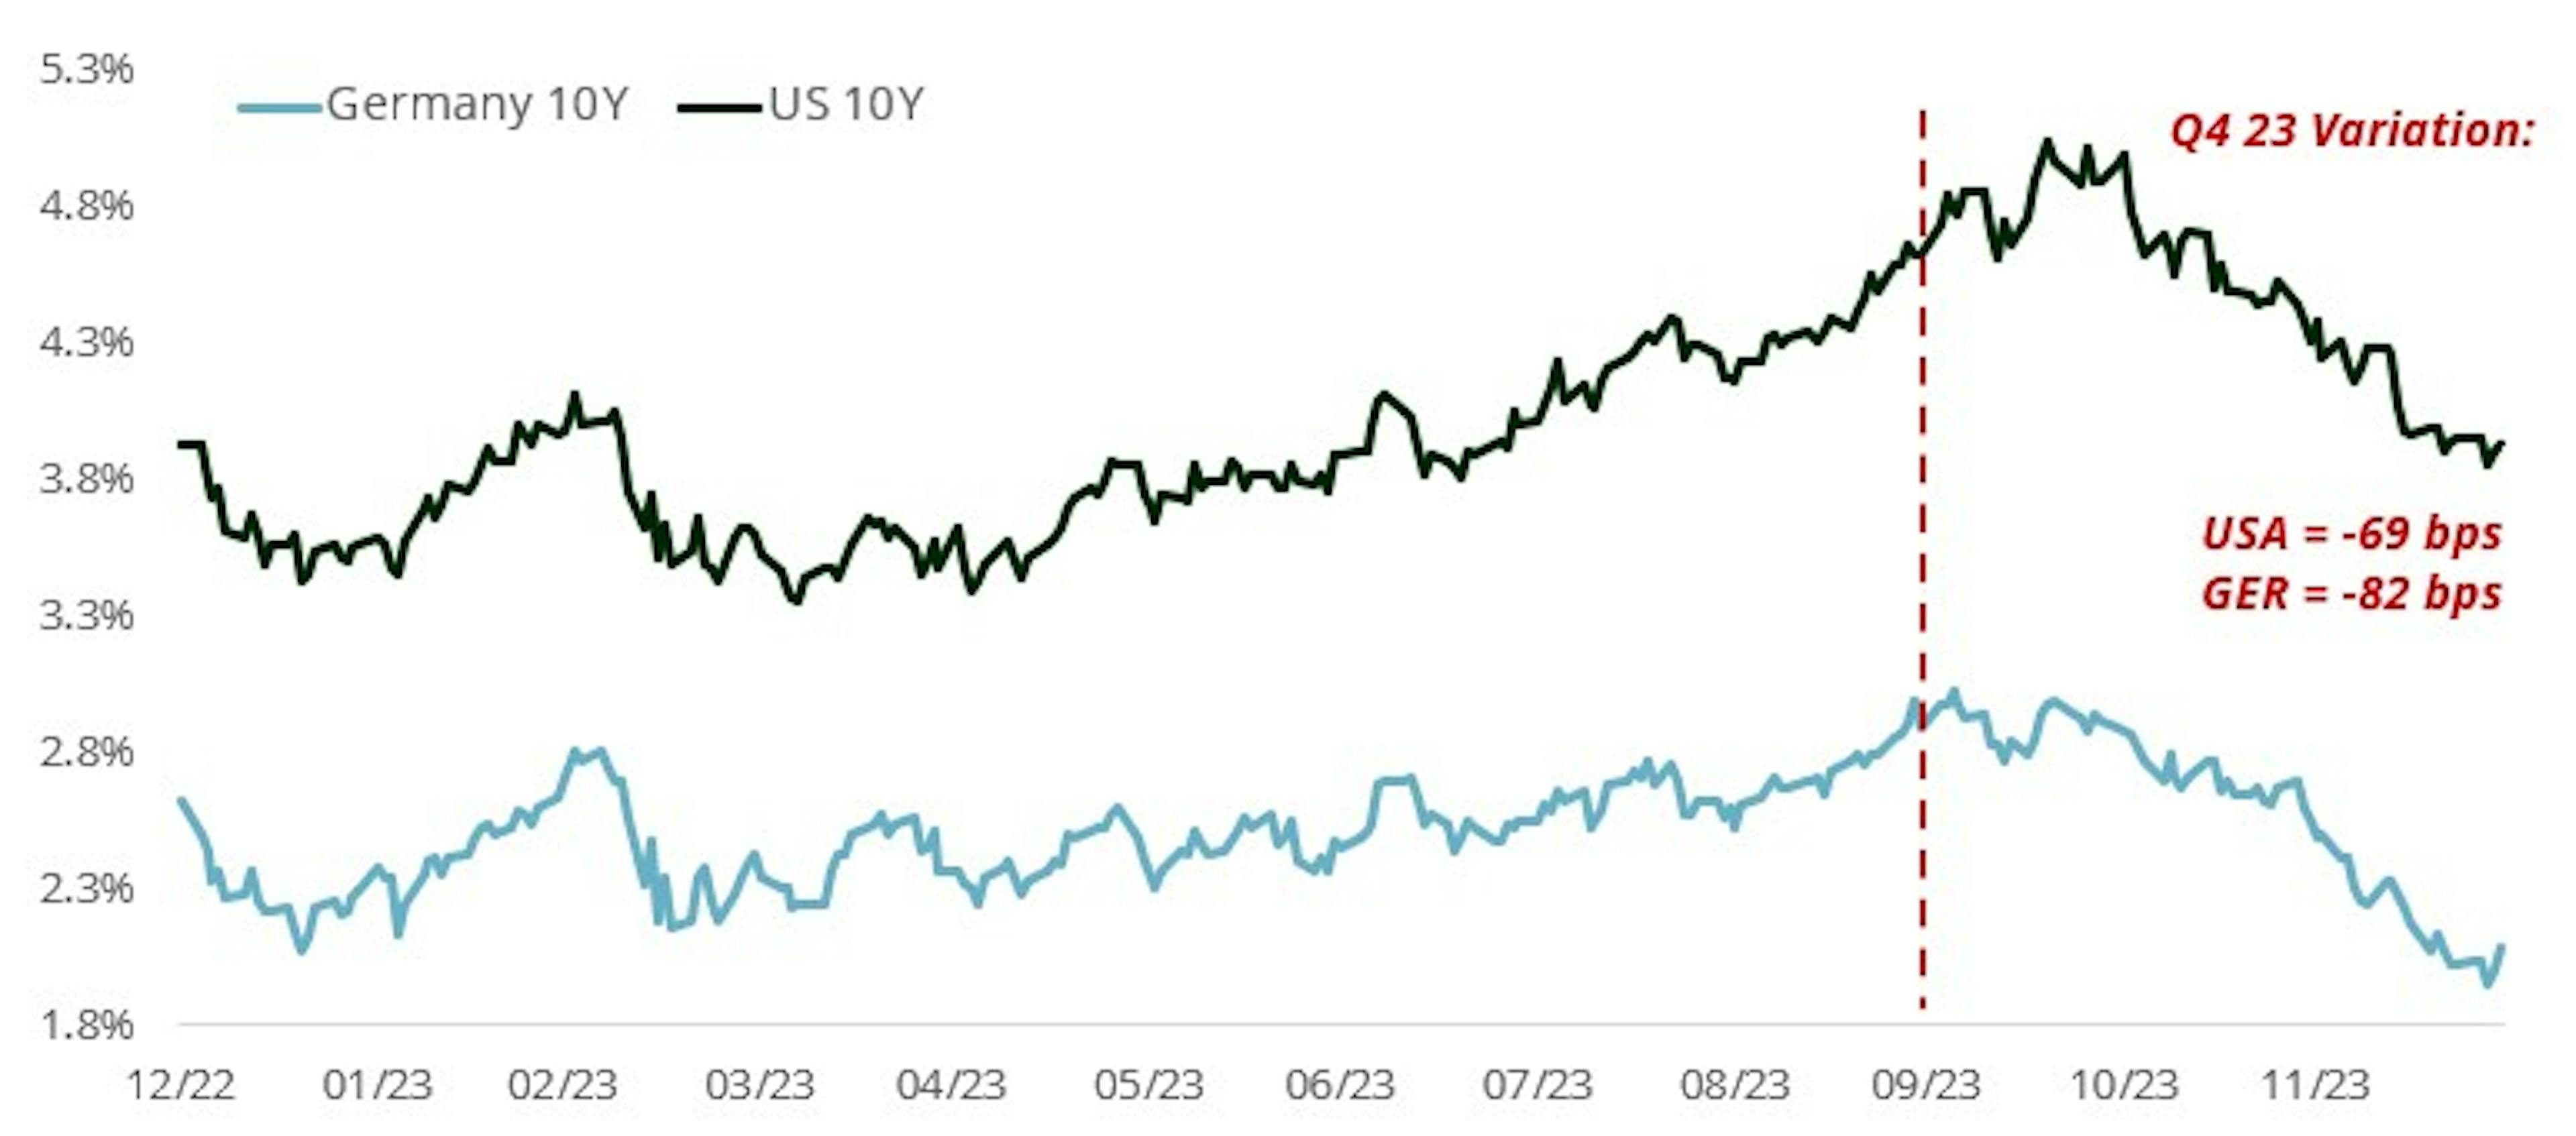
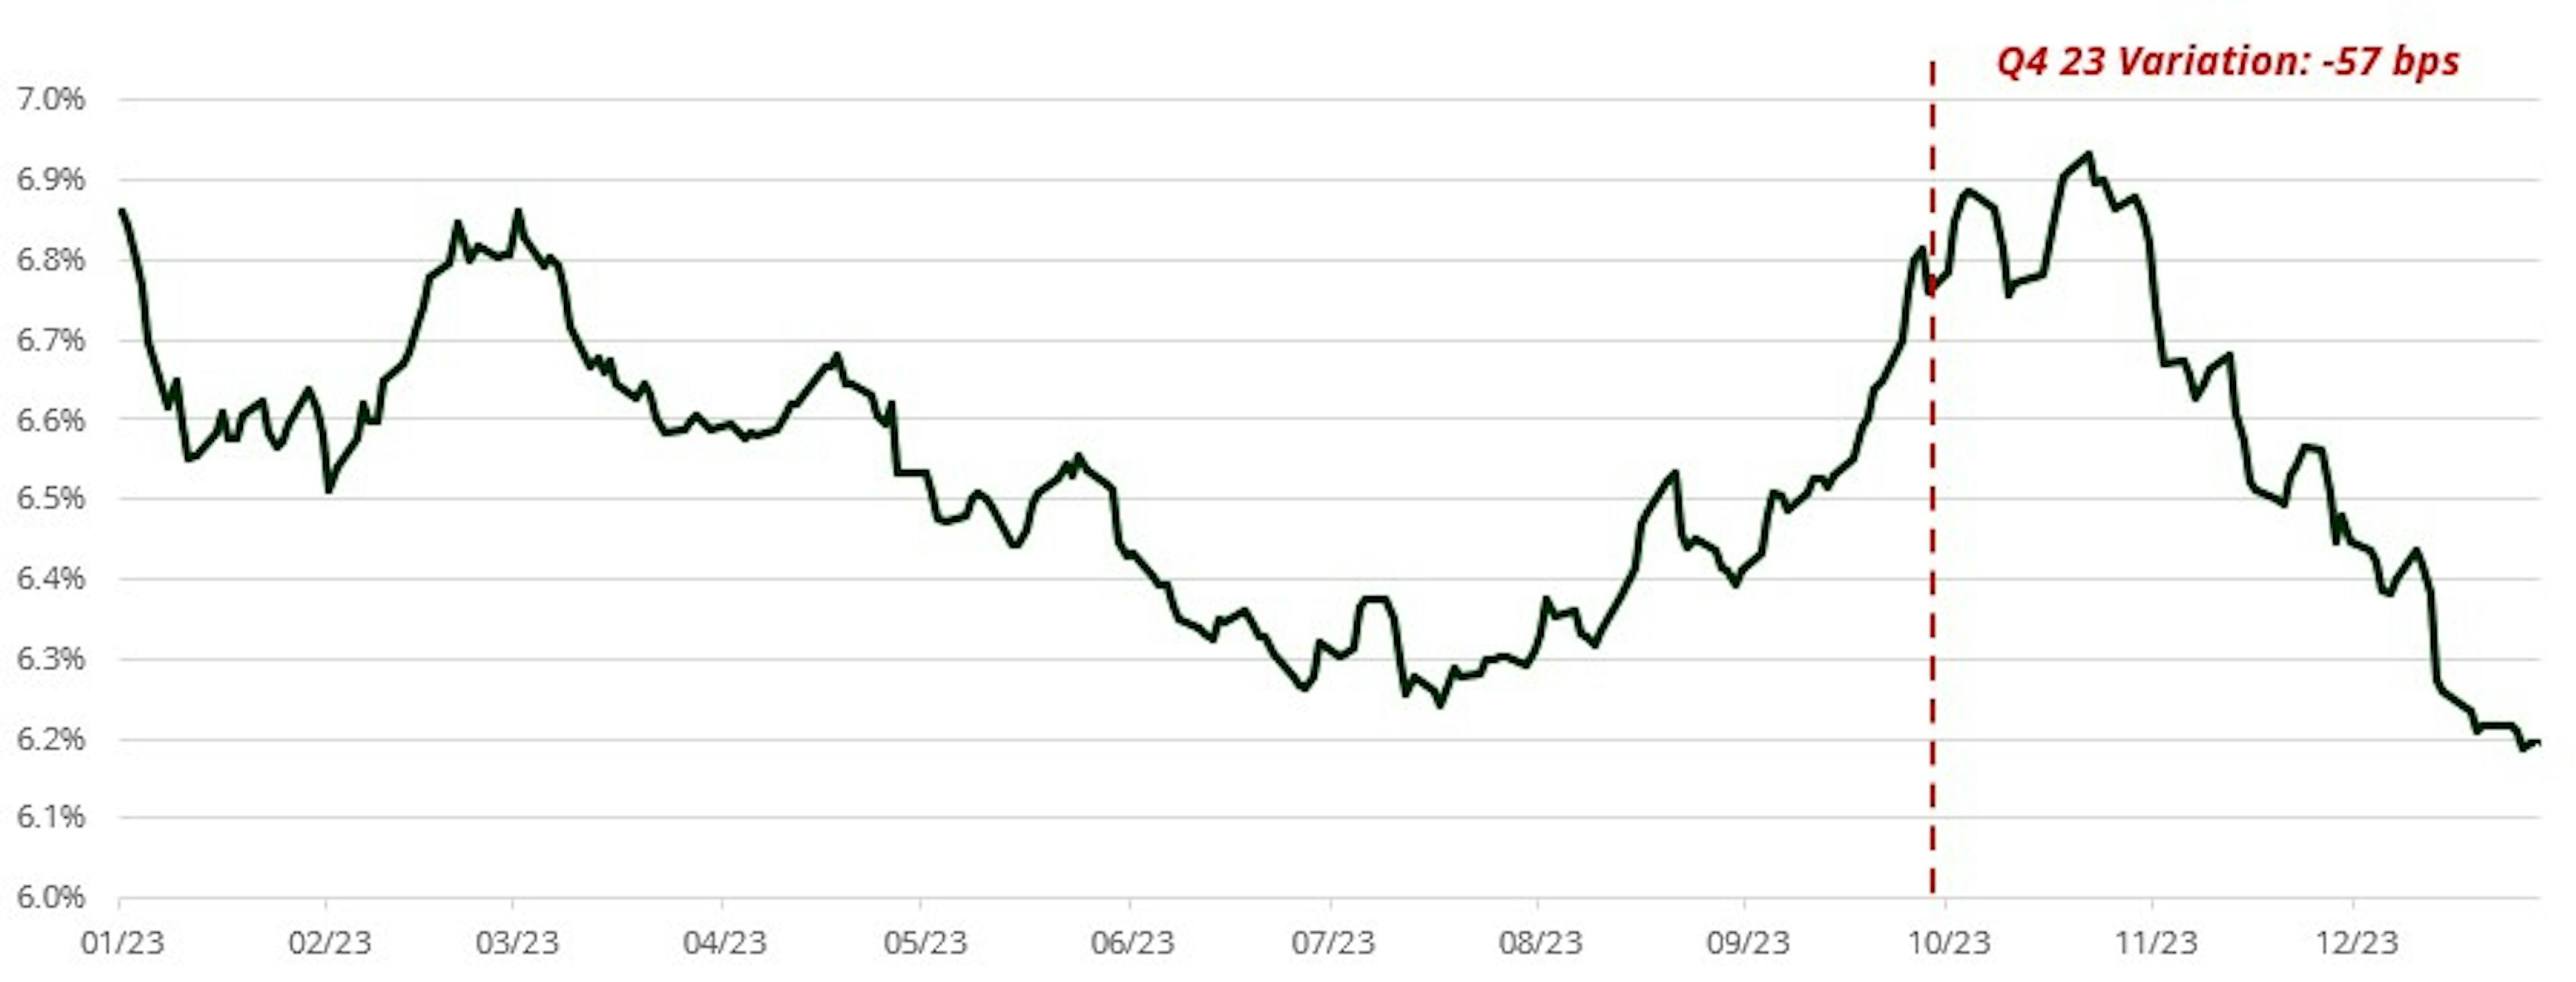
In terms of local rates, we continue to see rate cuts in the emerging market (EM) universe this quarter, both in LATAM and in EMEA, including Hungary (-75 basis points), Chile (-75 basis points), Brazil (-50 basis points) and Peru (-25 basis points), but also new joiners such as Czech Republic (-25 basis points) and Colombia (-25 basis points). Although inflation remains above central bank targets for the time being, it is continuing to slow convincingly. Indeed, the disinflation process in EM is very powerful and central banks are expected to continue their rate-cutting cycles. In China, the disappointing reopening continues to linger. Country’s activity is stabilizing but at low levels and investors grew more pessimistic about the country’s economic outlook.
GBI-EM Index (Local sovereign debt index) - Yield Evolution
Furthermore on FX, EM currencies continued to attract investors. Commodity exporter and high carry currencies like those in Latin America remained appealing. Nevertheless, a selective approach is still required, keeping an eye out for balance of payments and inflation trajectories. As an example, in Brazil the trade surplus is currently near historic highs and it has the highest real yield in the world close to 6%. Note that as the FED ended its hiking cycle, we should see downward pressure on the USD over the coming months, which should benefit to EM FX.
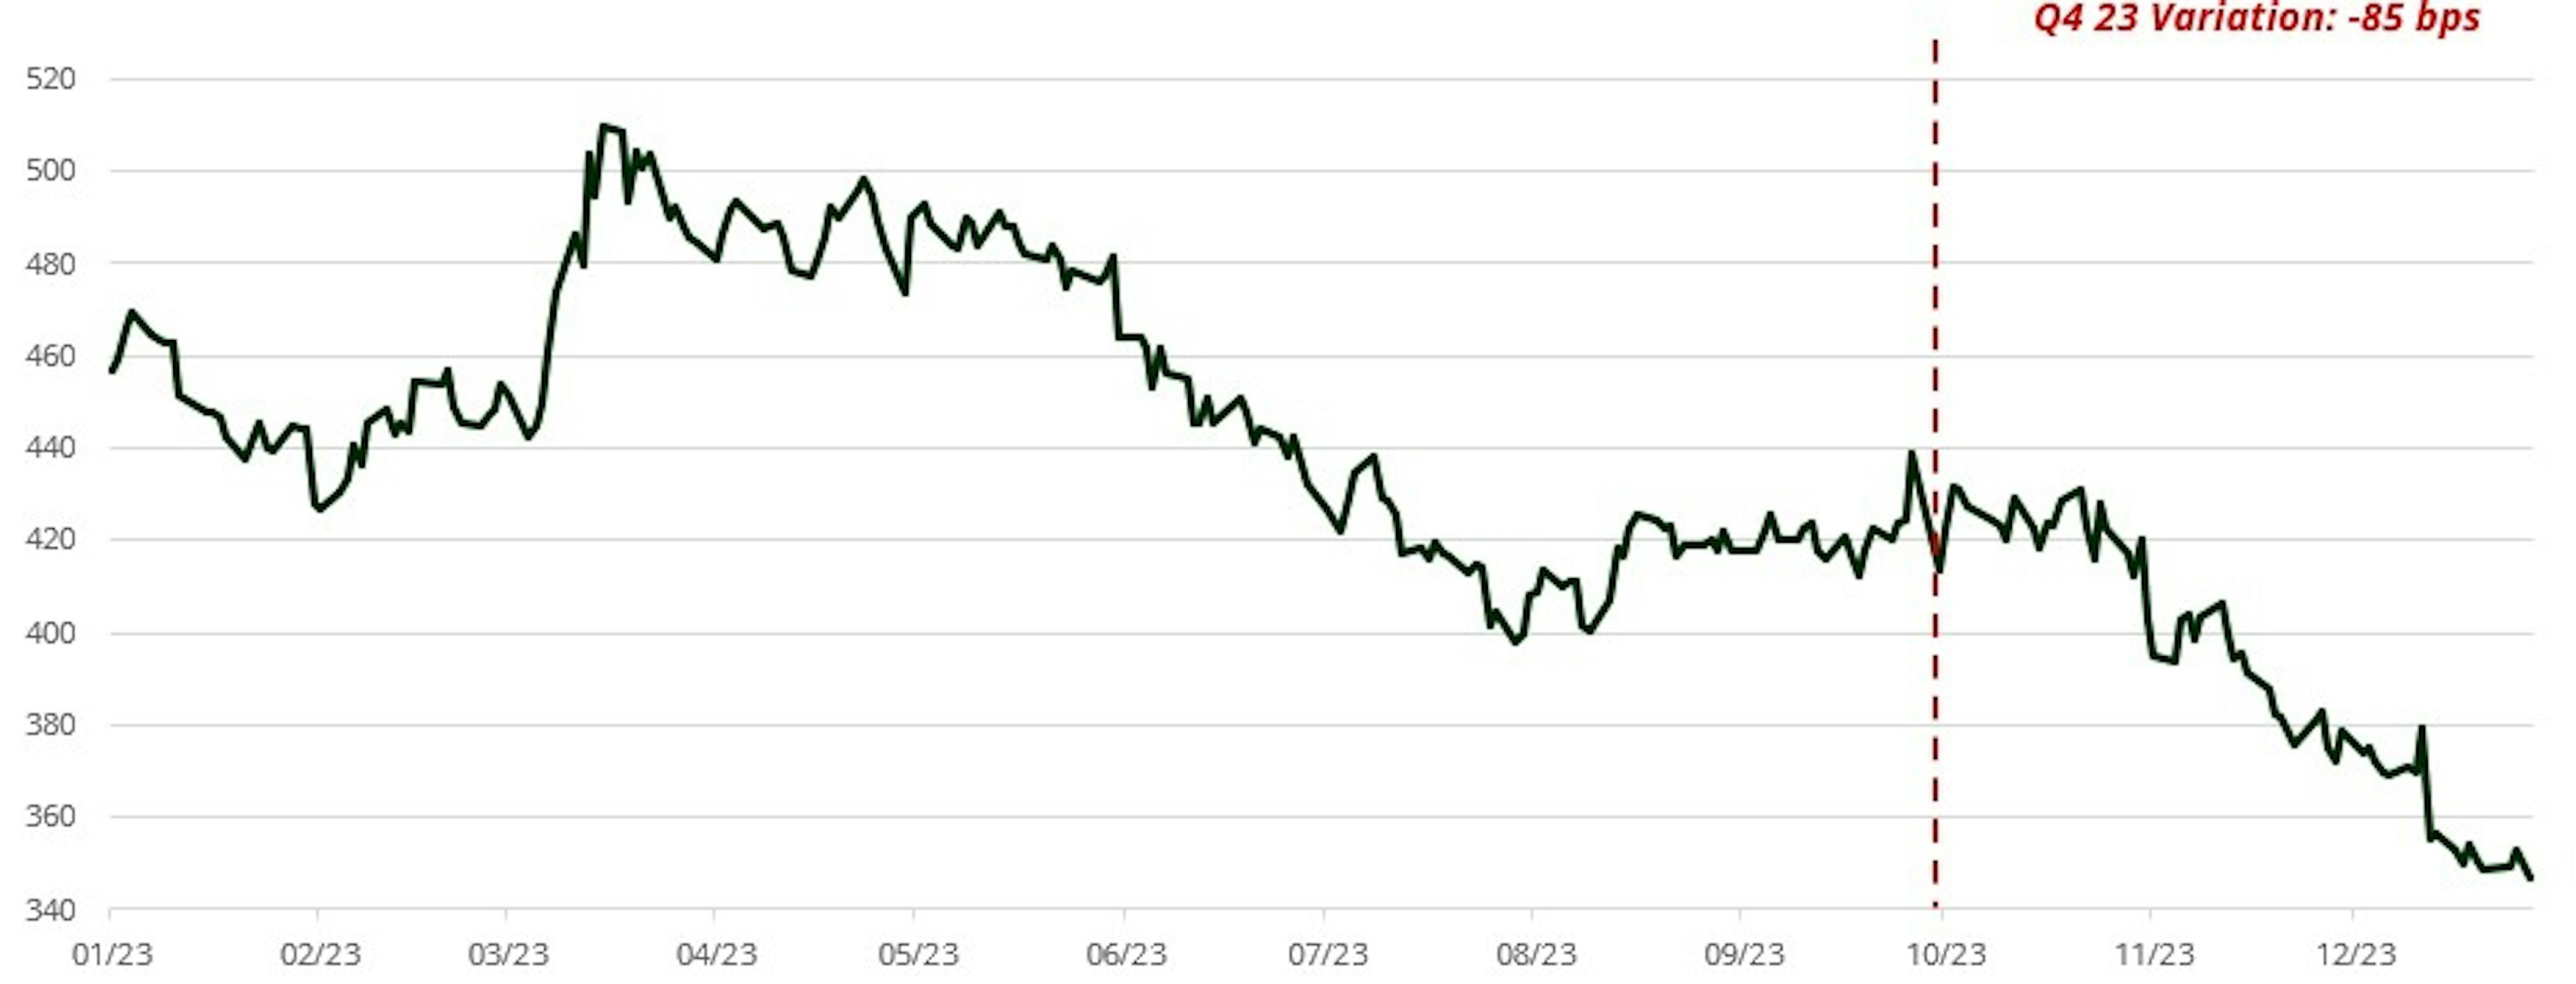
On sovereign credit, EM spreads tightened sharply during the quarter. Spreads are currently near historical tights especially in the investment grade space. The same is true for spreads in countries that have not defaulted or that are not at risk of default and the market kept a close eye on special situations such as in African countries.
J.P Morgan EMBIG diversified hedged EURO index (External sovereign debt index) - Spread
What have we done in this context?
After being very long in terms of duration, close to 800 basis points, and therefore benefiting from the rally in rates, we decided to reduce it close to 350 basis points. In this context, the fund has benefited from its exposure to local rates in countries like Czech Republic, Mexico, Colombia, Brazil, Peru and South Africa.
In the FX space we continue to enjoy the strong carry of EM FX currencies over the quarter. Nevertheless on a risk management basis, we reduced our exposure to EM currencies and we continue to be selective and active in this segment. As an example, at the end of the quarter we reinforced our exposure to the Japanese yen and the US dollar while taking some profits on our LATAM currencies such as the Brazilian real, Chilean Peso and Mexican Peso.
On sovereign credit, we benefited from our exposure to the EMEA and LATAM regions, in particular through Mexico, Colombia Romania and Egypt. Nevertheless, we reduced our exposure to this external debt over the period, following the rally and the expensive valuations.
Outlook for the next months
We are in the process of significant disinflation from the very high levels seen in the middle of last year in both the US and the Eurozone. Even if the Fed and ECB disappoint market expectations, we see there is an asymmetric potential for returns. We expect a very good year for EM returns given our base case scenario of either stability in yields or monetary easing.
In Local Rates, we are closely monitoring EM Central banks to pursue their cutting cycles as the FED and ECB have paused. We continue to like countries such as Brazil (due to commodities), Mexico (a key beneficiary of manufacturing diversification away from China) where real interest rates remain very high. For emerging markets debt denominated in local currency, yields in countries such as Brazil and Mexico are close to 10%.
In Sovereign Credit, we continue to favour idiosyncratic higher yielding stories and countries that will benefit in the long term from the “nearshoring” phenomenon, i.e. the potential repatriation of production chains to closer and more stable countries (Romania, Mexico, etc.). Nevertheless, we remain cautious and have added protection against our HY names.
Lastly, although we have reduced our global exposure to EM FX, we continue to favour a selection of currencies on a tactical/opportunist basis mainly in LATAM such as the Brazilian real.
1JP Morgan GBI – Emerging Markets Global Diversified Composite Unhedged EUR Index. Performance of the FW EUR acc share class.
Carmignac Portfolio EM Debt
Carmignac Portfolio EM Debt FW EUR Acc
- Empfohlene Mindestanlagedauer
- 3 Jahre
- Risikoskala*
- 3/7
- SFDR-Klassifizierung**
- Artikel 8
*Die Definition der Risikoskala finden Sie im KID/BIB (Basisinformationsblatt). Das Risiko 1 ist nicht eine risikolose Investition. Dieser Indikator kann sich im Laufe der Zeit verändern. **Die Offenlegungsverordnung (Sustainable Finance Disclosure Regulation - SFDR) 2019/2088. Die SFDR-Klassifizierung der Fonds kann sich im Laufe der Zeit ändern.
Hauptrisiken des Fonds
Kosten
- Einstiegskosten
- Wir berechnen keine Einstiegsgebühr.
- Ausstiegskosten
- Wir berechnen keine Ausstiegsgebühr für dieses Produkt.
- Verwaltungsgebühren und sonstige Verwaltungs- oder Betriebskosten
- 1.06% des Werts Ihrer Anlage pro Jahr. Hierbei handelt es sich um eine Schätzung auf der Grundlage der tatsächlichen Kosten des letzten Jahres.
- Erfolgsgebühren
- Für dieses Produkt wird keine erfolgsabhängige Provision berechnet.
- Transaktionskosten
- 0.34% des Werts Ihrer Anlage pro Jahr. Hierbei handelt es sich um eine Schätzung der Kosten, die anfallen, wenn wir die Basiswerte für das Produkt kaufen oder verkaufen. Der tatsächliche Betrag hängt davon ab, wie viel wir kaufen und verkaufen.
Performance
| Carmignac Portfolio EM Debt | +0.5 | +7.9 | +4.1 | +15.3 | −9.0 | +3.9 | +10.5 | +28.9 | −10.0 | +1.1 |
| Referenzindikator | +2.1 | +8.6 | +4.4 | +8.9 | −5.9 | −1.8 | −5.8 | +15.6 | −1.5 | +0.4 |
| Carmignac Portfolio EM Debt | +6.4% | +3.9% | +5.2% |
| Referenzindikator | +6.3% | +3.6% | +2.5% |
Quelle: Carmignac Stand 30. Okt 2026.
Datum des ersten NAV : 31/07/2017.
Wertentwicklungen der Vergangenheit lassen keine Rückschlüsse auf zukünftige Wertverläufe zu. Wertentwicklung nach Gebühren (keine Berücksichtigung von Ausgabeaufschlägen die durch die Vertriebsstelle erhoben werden können) Der Fonds ist mit einem Kapitalverlustrisiko verbunden.
Bei den nicht währungsgesicherten Anteilen kann die Rendite aufgrund von Währungsschwankungen steigen oder fallen.
Referenzindikator: 50% JPM GBI-EM Global Diversified Composite index + 50% JPM EMBI Global Diversified Hedged index. Häufigkeit der Neugewichtung: Quartalsweise