Equity strategies
FP Carmignac Emerging Markets
Share Class
GB00BK1W2P36
Risk Indicator
6 / 7
Recommended Minimum Investment Horizon
5 years
Cumulative Performance since launch
Cumulative Performance 10 YearsCumulative Performance 5 YearsCumulative Performance 3 YearsCumulative Performance 12 Months
From 15/05/2019
To 22/10/2026
+ 121.3 %
-
+ 31.0 %
+ 50.3 %
+ 13.4 %
Calendar Year Performance 2016Calendar Year Performance 2017Calendar Year Performance 2018Calendar Year Performance 2019Calendar Year Performance 2020Calendar Year Performance 2021Calendar Year Performance 2022Calendar Year Performance 2023Calendar Year Performance 2024Calendar Year Performance 2025
-
-
-
+ 13.6 %
+ 63.0 %
- 15.6 %
- 9.5 %
+ 7.2 %
+ 0.9 %
+ 28.9 %
Net Asset Value
£2.21
Asset Under Management
125 M £
Net Equity Exposure30/09/2026
97.8%
FP Carmignac Emerging Markets fund performance
Fund performance vs. reference indicator (basis 100 - net of fees)
Data as of: 25 Oct 2026.Calendar Year Performance (as %)
Calendar Year Performance (as %)
Data as of: 30 Sep 2026.- FP Carmignac Emerging Markets - A GBP ACC
- Comparator Benchmark: MSCI EM NR index
| FP Carmignac Emerging Markets A GBP ACC | +24.6% | +0.6% | −3.7% | +31.1% | +66.6% | +44.8% | - |
| Comparator Benchmark | +24.9% | +1.4% | −0.5% | +30.9% | +75.6% | +55.7% | - |
| Category Average | +23.5% | +1.1% | −1.2% | +29.0% | +68.9% | +46.2% | - |
| Ranking (quartile) | 3 | 4 | 4 | 2 | 3 | 3 | - |
Past performance is not necessarily indicative of future performance. Performances are net of fees (excluding possible entrance fees charged by the distributor). The Fund presents a risk of loss of capital.
Morningstar Rating™ : © Morningstar, Inc. All Rights Reserved. The information contained herein: is proprietary to Morningstar and/or its content providers; may not be copied or distributed; and is not warranted to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information.
Source: Carmignac at 30/09/2026.
Statistics (%)
These measures are used to assess a Fund's risk-adjusted performance. A well-performing Fund should ideally have a solid return (measured by the Sharpe ratio and alpha) relative to its risk (measured by volatility), while being well aligned with market expectations (measured by beta relative to the reference indicator).
Volatility
Data as of: 30 Sep 2026.| Fund | +15.4 | +16.3 | +17.8 |
| Comparator Benchmark | +14.4 | +14.7 | +15.3 |
Calculation : Weekly basis
Ratio
Data as of: 30 Sep 2026.| Sharpe Ratio | +0.9 | +0.2 | +0.5 |
| Beta | +1.0 | +1.0 | +1.0 |
| Alpha (annualised) | +0.1 | +0.6 | +0.9 |
Calculation : Weekly basis
Comparator Benchmark: MSCI EM NR index
Source: Carmignac at 30 Sep 2026.
Monthly Gross Performance Contribution
The contribution to performance demonstrates the different sources of returns. The sum of these elements is equal to the performance before the deduction of management fees applicable to the portfolio for the period in question. Fees payable for the period account for the difference between the gross performance and the net performance.
Monthly Gross Performance Contribution
Data as of: 30 Sep 2026.Equity portfolio+1.0%
Mutual fund+0.1%
Total+1.0%
Comments from the Investment Team
Read the Investment team's analysis below.
FP Carmignac Emerging Markets Monthly comments
Data as of: 30 Sep 2026.The Investment team
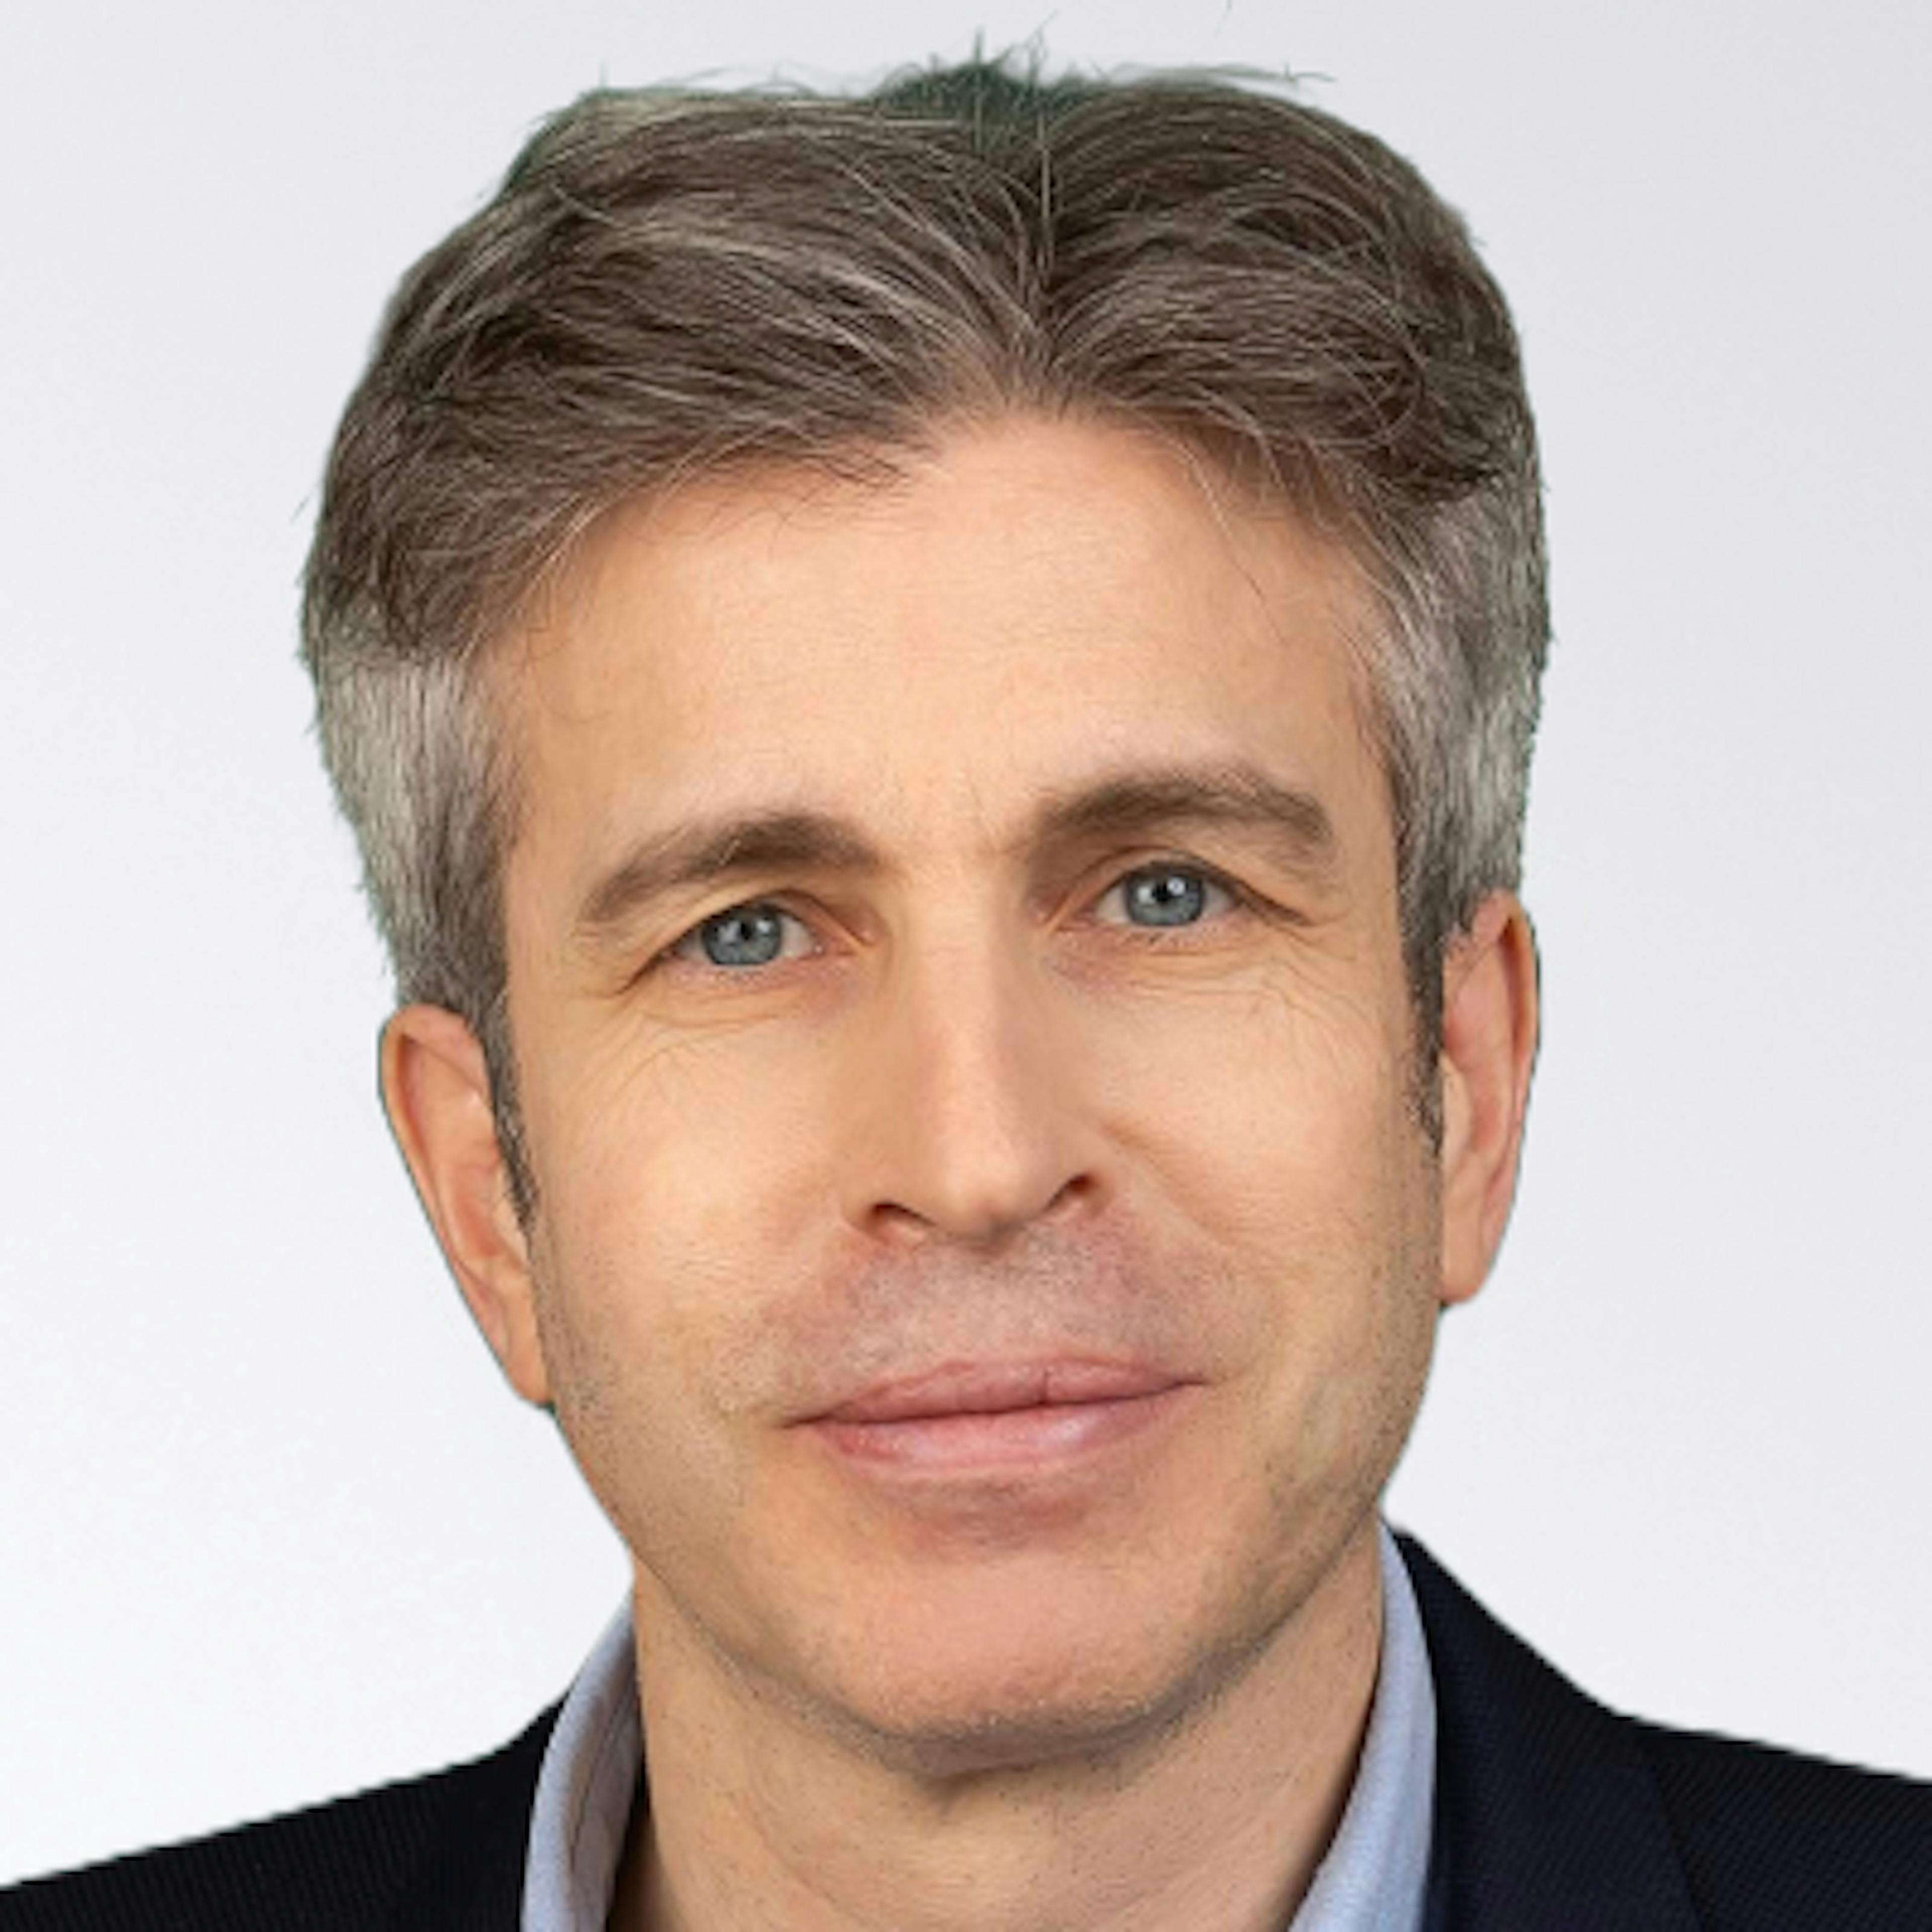
Xavier HOVASSE
Fund Manager

Performance Commentary
- The Fund delivered a positive absolute return in September but underperformed its reference indicator.
- Korea and Taiwan were the main contributors, led by SK Square, Samsung Electronics, TSMC and SK Hynix. Semiconductor stocks benefited from renewed enthusiasm around AI infrastructure and persistent demand for high-bandwidth memory. TSMC reported a 53% year-on-year increase in August revenues, reflecting continued strong AI-chip demand, while Korean memory names rallied as expectations for AI-related memory requirements strengthened further.
- Brazilian utilities also supported performance. Axia Energia benefited from an increasingly shareholder-friendly capital allocation policy, including several preferred-share redemptions announced during September, effectively returning billions of reais to shareholders. Equatorial Energia was supported by a favourable regulatory backdrop, including a 6.9% tariff adjustment for its Pará distribution business.
- Conversely, Chinese stock selection detracted. CATL fell sharply as investors reacted to speculation of production cuts, lower unit profitability and growing efforts by Chinese automakers to diversify battery suppliers away from CATL. Shenzhen Han’s CNC also corrected after a very strong year-to-date rally; with the shares having more than doubled despite strong earnings growth, the September decline appeared largely driven by valuation normalisation and profit-taking.
Outlook and Investment Strategy
- We remain constructive on emerging-market equities, while maintaining a selective approach and strict valuation discipline. The asset class continues to benefit from stronger earnings growth than developed markets, attractive relative valuations and exposure to structural trends ranging from AI and advanced manufacturing to electrification and power infrastructure.
- AI hardware remains a core conviction, but our focus is increasingly shifting towards the next bottlenecks in the investment cycle. We continue to diversify beyond memory and compute towards areas such as power, cooling, connectivity, advanced packaging and semiconductor equipment, while retaining exposure to our highest-conviction technology leaders. During the month, we trimmed Asia Vital Components following a strong run since August.
- We also continue to broaden the Fund’s sources of alpha beyond AI and technology. In Latin America, we increased our position in the Peruvian bank Credicorp while maintaining our decent exposure to Brazilian utilities ahead of general elections in October, where potential political change with a shift towards greater fiscal orthodoxy could support equity markets.
- In India, where we remain selective, however we are slightly increasing exposure by adding to areas where we see attractive opportunities. We notably participated to the long-awaited IPO of NSE (National Stock Exchang of India) gaining exposure to the continued deepening of Indian capital markets.
- Recent portfolio activity therefore reflects our continued willingness to recycle capital towards our highest-conviction opportunities to maintain diversification across geographies and structural growth drivers.
- Portfolio balance, position sizing and valuation discipline continues to remain central to our approach.
Articles that may interest you
Webconference • 22 October 2026 • English
Emerging Markets beyond the rebound: stronger fundamentals and mispriced growth opportunities
Strategies insights • 15 October 2026 • English
FP Carmignac Emerging Markets: Letter from the Fund Managers - Q3 2026
6 minute(s) read
Did you enjoy the fund page?
Reference to certain securities and financial instruments is for illustrative purposes to highlight stocks that are or have been included in the portfolios of funds in the Carmignac range. This is not intended to promote direct investment in those instruments, nor does it constitute investment advice. The Management Company is not subject to prohibition on trading in these instruments prior to issuing any communication. The portfolios of Carmignac funds may change without previous notice.
The reference to a ranking or prize, is no guarantee of the future results of the UCIS or the manager.
The information presented above is not contractually binding and does not constitute investment advice. Past performance is not a reliable indicator of future performance. Performance is shown net of fees (excluding any subscription fees payable to the distributor). Investors may lose some or all of their capital, as the capital in the UCI is not guaranteed. Access to the products and services presented herein may be restricted for some individuals or countries. Taxation depends on the situation of the individual. The risks, fees and recommended investment period for the UCI presented are detailed in the KIDs (key information documents) and prospectuses available on this website. The KID must be made available to the subscriber prior to purchase.
The information presented above is not contractually binding and does not constitute investment advice. Past performance is not a reliable indicator of future performance. Performances are net of fees (excluding possible entrance fees charged by the distributor), where applicable. Investors may lose some or all of their capital, as the capital in the UCI is not guaranteed. Access to the products and services presented herein may be restricted for some individuals or countries. Taxation depends on the situation of the individual. The risks, fees and recommended investment period for the UCI presented are detailed in the KIDs (key information documents) and prospectuses available on this website. The KID must be made available to the subscriber prior to purchase.). The reference to a ranking or prize, is no guarantee of the future results of the UCITS or the manager.
Market Environment